Providing professional advice or services comes with responsibility. Even highly skilled professionals can face claims alleging mistakes, negligence, missed deadlines, inaccurate advice, or failure to deliver promised services. Defending against these claims can be expensive, even when the allegations are unfounded.
What you’ll understand
- Business Insurance Risk Explorer
- What Is Professional Liability Insurance?
- Why Professional Liability Insurance Matters
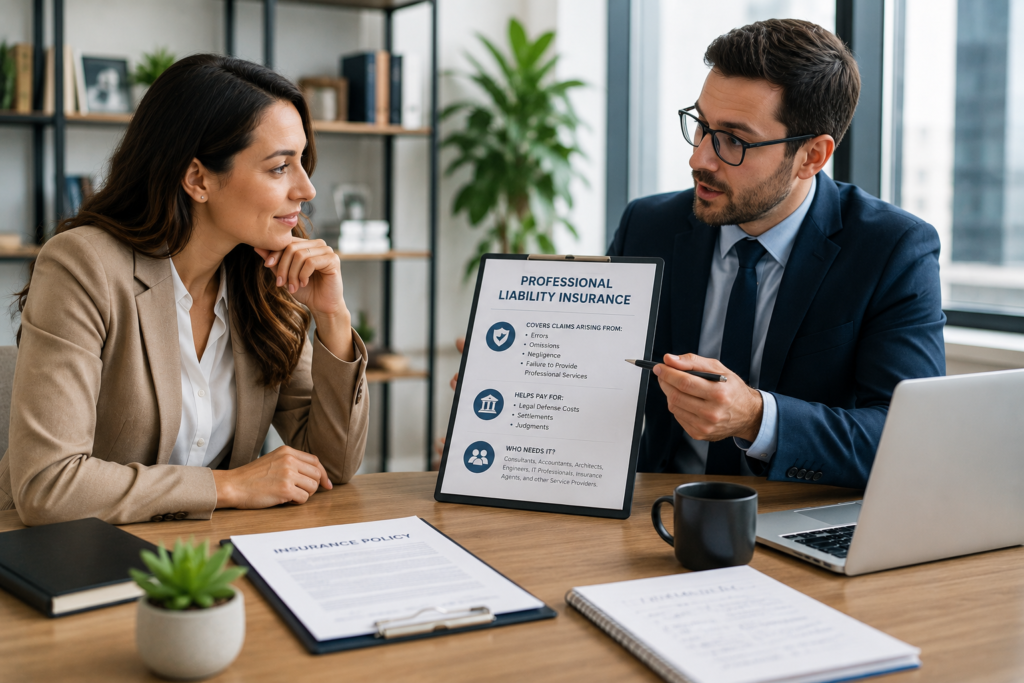
Professional Liability Insurance—also known in many industries as Errors and Omissions (E&O) Insurance—is designed to help protect professionals and businesses from certain financial losses arising from claims related to professional services.
Whether you’re a consultant, accountant, architect, insurance agent, marketing agency, healthcare professional, IT consultant, or engineer, understanding how professional liability insurance works is an important part of managing business risk.
This guide explains what professional liability insurance covers, who may need it, common exclusions, factors affecting premiums, and how to choose the right policy.
Business Insurance Risk Explorer
Select the exposures that apply to your business.
This is an educational risk-mapping tool, not a coverage recommendation. Requirements and suitable limits depend on the business, contracts, jurisdiction and policy terms.
What Is Professional Liability Insurance?
Professional liability insurance is a business insurance policy designed to help protect professionals against claims alleging financial harm caused by errors, omissions, negligence, or failure to provide professional services as expected.
Unlike general liability insurance, which primarily focuses on bodily injury, property damage, and certain advertising injuries, professional liability insurance addresses risks arising from professional advice or services.
Depending on the policy, coverage may help pay for:
- Legal defense costs
- Court expenses
- Settlements
- Judgments, subject to policy limits
- Investigation costs, where covered
Coverage always depends on the specific policy terms, exclusions, and limits.
Why Professional Liability Insurance Matters
Even experienced professionals can face allegations such as:
- Incorrect professional advice
- Missed project deadlines
- Errors in reports
- Design mistakes
- Data handling mistakes
- Contract disputes involving professional services
- Failure to meet professional standards
A claim does not have to be valid to create significant legal expenses. Professional liability insurance may help with covered defense costs even if the claim is ultimately dismissed.
Who Should Consider Professional Liability Insurance?
Many service-based professionals may benefit from evaluating this coverage, including:
- Consultants
- Accountants
- Architects
- Engineers
- Insurance agents
- Financial advisors
- Marketing agencies
- Graphic designers
- Software developers
- IT consultants
- Real estate professionals
- Business coaches
- Healthcare providers (subject to profession-specific policies)
- Attorneys (through legal malpractice policies where applicable)
Businesses that primarily provide expertise rather than physical products often face professional liability exposures.
What Does Professional Liability Insurance Typically Cover?
Coverage varies by insurer and policy, but may include:
Professional Errors
Claims alleging mistakes while providing professional services.
Negligence
Claims alleging that professional standards were not met.
Errors and Omissions
Coverage for certain financial losses resulting from unintentional mistakes or failure to perform professional duties.
Legal Defense Costs
Attorney fees and court costs for covered claims may be included, even if the allegations are ultimately not proven.
Settlements and Judgments
If a covered claim is resolved through settlement or a court judgment, the policy may contribute up to the applicable policy limits.
Common Examples
A client alleges that:
- A consultant’s advice caused financial loss.
- An accountant made an error in financial statements.
- An architect’s design required costly revisions.
- A software developer failed to deliver agreed functionality.
- A marketing agency missed a major campaign deadline.
- An insurance broker recommended unsuitable coverage.
- An engineer’s calculation error delayed construction.
Whether coverage applies depends on the facts of the claim and the policy language.
Professional Liability vs. General Liability Insurance
| Feature | Professional Liability | General Liability |
|---|---|---|
| Covers professional mistakes | ✔ | ✘ |
| Covers bodily injury claims | ✘ | ✔ |
| Covers property damage to others | ✘ | ✔ |
| Covers financial loss from professional services | ✔ | ✘ |
| Covers legal defense for covered claims | ✔ | ✔ |
Many businesses purchase both policies because they address different types of risk.
What Professional Liability Insurance Usually Does Not Cover
Most policies contain exclusions. Common exclusions may include:
- Intentional or fraudulent acts
- Criminal conduct
- Bodily injury (unless specifically covered)
- Property damage
- Employment-related disputes
- Contractual liabilities beyond the policy’s scope
- Claims arising before the policy’s retroactive date (where applicable)
Always review the policy wording carefully to understand exclusions.
Claims-Made Policies
Many professional liability policies are written on a claims-made basis. This generally means coverage depends on when the claim is made and reported, along with other policy conditions such as retroactive dates and continuous coverage.
Understanding how claims-made coverage works is important before purchasing or changing policies.
How to Choose the Right Professional Liability Insurance
Selecting a professional liability policy involves more than comparing premiums. The policy should reflect the type of services you provide, the size of your business, and the financial risks associated with your profession.
Consider the following before purchasing coverage.
1. Evaluate Your Professional Risks
Ask yourself:
- Do clients rely on your advice or recommendations?
- Could an error result in financial loss for a client?
- Do you sign professional contracts?
- Do you manage confidential client information?
- Could a missed deadline create financial consequences?
The answers can help determine whether professional liability insurance is appropriate for your business.
2. Review Coverage Limits
Coverage limits determine the maximum amount the insurer may pay for covered claims.
When choosing limits, consider:
- Size of your projects
- Value of client contracts
- Potential legal defense costs
- Industry requirements
- Client expectations
Higher-risk professions may require higher coverage limits.
3. Understand the Deductible
Many professional liability policies include a deductible.
A higher deductible may reduce premiums but increases your out-of-pocket responsibility if a covered claim occurs.
Choose a deductible that your business could reasonably afford.
4. Check Retroactive Dates
Because many professional liability policies are claims-made, the retroactive date is an important feature.
Changing insurers without maintaining appropriate prior acts coverage could leave gaps in protection for services performed in the past.
5. Review Policy Exclusions
Before purchasing a policy, understand:
- What is covered.
- What is excluded.
- Whether optional endorsements are available.
- Whether industry-specific risks require additional coverage.
Factors That Affect Premiums
Professional liability insurance premiums vary depending on several factors, including:
- Profession
- Industry
- Annual revenue
- Number of employees
- Years in business
- Claims history
- Coverage limits
- Deductible selected
- Geographic location
- Types of services offered
Businesses with higher exposure to professional negligence claims generally pay higher premiums.
Industries That Frequently Purchase Professional Liability Insurance
Professional liability insurance is common among:
- Accounting firms
- Consulting businesses
- Engineering companies
- Architectural firms
- Marketing agencies
- Technology companies
- Insurance agencies
- Real estate professionals
- Healthcare providers
- Financial advisors
- Design studios
- Management consultants
Many client contracts require proof of professional liability coverage before work begins.
Professional Liability Insurance vs. Errors & Omissions Insurance
In many industries, Professional Liability Insurance and Errors & Omissions (E&O) Insurance refer to the same general type of coverage.
However, terminology may differ depending on the profession or insurer.
Examples include:
- Technology companies often refer to it as Technology E&O.
- Insurance agents may purchase Insurance Agents E&O.
- Real estate professionals may obtain Real Estate E&O.
- Architects and engineers often have profession-specific professional liability policies.
Although names vary, policy terms and covered risks differ by insurer and occupation.
Risk Management Tips
Insurance is only one part of protecting your business.
Consider these best practices:
- Use detailed written contracts.
- Clearly define project scope.
- Document client communications.
- Maintain accurate records.
- Follow professional standards.
- Review work before delivery.
- Keep client information secure.
- Maintain continuing education and professional certifications where applicable.
Good business practices may reduce the likelihood of disputes and claims.
Common Mistakes to Avoid
Assuming General Liability Covers Professional Advice
General liability insurance generally does not cover claims arising from professional errors, omissions, or negligent advice.
Buying the Lowest Coverage Limit
A policy with insufficient limits may leave your business responsible for costs that exceed the policy maximum.
Allowing a Claims-Made Policy to Lapse
A break in claims-made coverage could affect protection for services provided before the lapse, depending on the policy and retroactive date.
Ignoring Contract Requirements
Many clients specify minimum insurance requirements. Review contracts carefully before accepting new work.
Failing to Report Claims Promptly
Claims-made policies often require timely reporting. Delayed notification could affect coverage.
Frequently Asked Questions
Is professional liability insurance legally required?
Requirements vary by profession, state, licensing authority, and client contracts. Some professions must carry professional liability insurance, while others purchase it voluntarily as part of their risk management strategy.
Does professional liability insurance cover legal fees?
Many policies include legal defense costs for covered claims, subject to the policy’s terms, limits, and exclusions.
Is professional liability insurance the same as general liability insurance?
No. Professional liability insurance focuses on claims involving professional services, while general liability insurance generally covers bodily injury, property damage, and certain advertising injuries.
Can freelancers purchase professional liability insurance?
Yes. Many insurers offer professional liability policies designed for freelancers, consultants, and self-employed professionals.
Does professional liability insurance cover intentional misconduct?
Generally, no. Most policies exclude intentional, fraudulent, or criminal acts.
Final Thoughts
Professional liability insurance is an important form of protection for businesses and individuals who provide professional advice, expertise, or specialized services. Even experienced professionals can face allegations of negligence, errors, or omissions that result in costly legal proceedings.
By understanding your professional risks, selecting appropriate coverage limits, maintaining continuous coverage where applicable, and following sound business practices, you can better protect your business from the financial impact of covered professional liability claims.
Key terms in this guide
Tap a term to review the plain-English meaning while you read.
Premium
The amount charged for insurance coverage, usually paid monthly, quarterly or annually.
Deductible
The amount you may need to pay toward a covered loss before the insurer pays under the policy, subject to the policy terms.
Policy Limit
The maximum amount an insurer may pay for a covered loss or category of loss under the policy.
Exclusion
A policy provision that removes specified situations, causes, property, people or losses from coverage.
Endorsement
A document that changes, adds to or removes terms from the standard insurance policy.
Claim
A request for payment or benefits under an insurance policy after an event that may be covered.
Did the guide make sense?
Answer two quick questions. Your score stays in this browser.
Verify Current Rules
Insurance rules, benefits and product terms can change. These official resources are useful starting points for checking current requirements; they do not replace your policy documents or jurisdiction-specific advice.
Thanks — your response is saved in this browser.
Continue learning, not just scrolling
Follow a practical path from understanding the idea to comparing options and preparing for real-world decisions.
 StartCopays vs. Coinsurance Explained: What’s the Difference and Which Costs You More?Build the foundation →
 CompareCyber Insurance 2.0: Why Your 2026 Policy Now Requires “Proof of Defense”Compare your options →
 PlanMedicare Advantage 2026: A Plan-Comparison Checklist for Networks, Drugs, and CostsUnderstand the numbers →
 ActInvisible and Autoimmune Disability Claims: Building Evidence Around FunctionBe ready for a claim →
Leave a Comment
Share a helpful question or experience. Your email address will not be published.