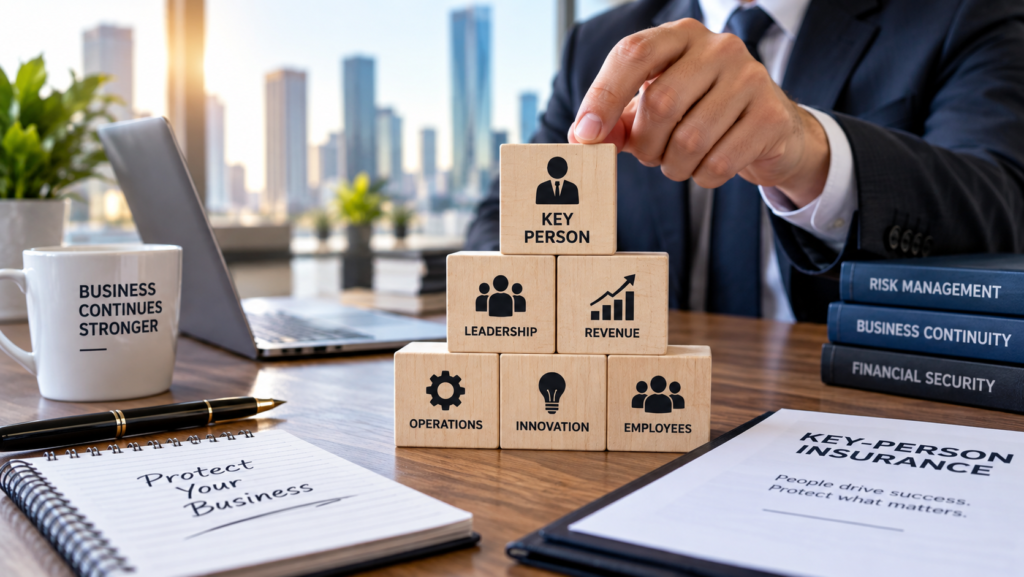
A business can survive the loss of equipment more easily than the loss of the one person who brings in its largest customers, holds critical technical knowledge, leads fundraising, manages a professional practice or keeps lenders and investors confident.
What you’ll understand
- Key-Person Insurance in 60 Seconds
- Key Person Exposure Planner
- What Is Key-Person Insurance?
That concentration of dependence is key-person risk. Key-person insurance—also called key-man or key-employee insurance—is commonly structured as life insurance owned by a business on a person whose death could create a material financial loss. The business generally owns the policy, pays the premium and is the beneficiary. Disability coverage can be considered separately when the concern is a long absence rather than death.
The useful question is not simply “Should we buy key-person insurance?” It is: What financial problem would the loss of this person create, how long would that problem last, and what combination of insurance, cash reserves and succession planning would help the business absorb it?
Key-Person Insurance in 60 Seconds
| Question | Practical answer |
|---|---|
| Who can be a key person? | A founder, executive, salesperson, technical specialist, licensed professional, partner or other person whose loss could materially affect revenue, operations, financing or continuity. |
| Who normally owns the policy? | In a typical arrangement, the business owns the policy. |
| Who is insured? | The individual whose loss creates the business exposure. |
| Who normally receives the death benefit? | The business, when it is the named beneficiary and the claim is payable. |
| What can proceeds help with? | Recruitment, transition costs, lost revenue, debt obligations, liquidity and business-continuity needs. |
| Does life insurance cover disability? | Not simply because the person cannot work. Key-person disability coverage is a separate issue to investigate. |
Key Person Exposure Planner
Estimate how much financial disruption one key person could create for the business.
This is an educational continuity-planning estimate, not an insurance recommendation or quote. A policy amount should be based on the business's actual financial exposure, insurable interest, underwriting limits, ownership structure, tax considerations and advice from qualified professionals.
What Is Key-Person Insurance?
The National Association of Insurance Commissioners defines key-person insurance as a policy purchased by and for the benefit of a business that insures personnel integral to business operations. In practice, the phrase describes the business purpose and ownership structure of the coverage rather than one single standardized product.
A common arrangement looks like this:
- Policy owner: the business.
- Insured: the key employee, owner or executive.
- Premium payer: the business.
- Beneficiary: the business.
If the insured person dies while the policy is in force and the claim is payable, the business receives the applicable death benefit. That money does not replace leadership, expertise or relationships, but it can create time and liquidity while the company responds.
Who Is Actually a Key Person?
A key person does not have to be the CEO or highest-paid employee. The better test is whether the business would suffer a material financial or operational shock if the person suddenly became unavailable.
Founder or owner
A founder may hold customer relationships, institutional knowledge, intellectual property, financing relationships and decision-making authority that have never been distributed across the team.
Top salesperson or relationship manager
If one salesperson is responsible for a large share of recurring revenue, customer retention or channel partnerships, their loss can create an immediate revenue problem even if their salary is modest compared with the value of the relationships they manage.
Technical or product specialist
A technology, engineering, manufacturing or scientific business may depend on one person who understands a critical system, patent, production process or customer implementation.
Licensed professional
Medical, dental, legal, accounting, architecture, engineering and other professional firms may depend heavily on an individual whose license, reputation or client relationships drive the practice.
Executive tied to financing
Lenders or investors may view a specific founder or executive as central to repayment capacity, fundraising, strategy or enterprise value. In those situations, key-person risk is also a financing and governance issue.
A Realistic Business Scenario
Imagine a software company with $5 million in annual revenue. One founder leads the product roadmap, manages the three largest customers and is central to investor discussions. Management estimates that roughly 35% of revenue is meaningfully exposed to disruption if that person is lost and that it could take 12 to 18 months to recruit and transition a replacement.
The company could face executive-search fees, lost or delayed sales, customer attrition, temporary consulting costs, debt-service pressure and a decline in confidence among employees and investors. A key-person policy would not solve those operational problems, but a death benefit could give the company additional liquidity while it executes a continuity plan.
What Can the Death Benefit Be Used For?
The policy proceeds are generally paid to the beneficiary under the contract. A business may use available funds for needs such as:
- Recruiting and executive-search costs.
- Temporary leadership or specialist support.
- Training and transition costs.
- Replacing lost revenue or margin during disruption.
- Maintaining payroll and essential operating expenses.
- Managing debt or lender obligations.
- Providing liquidity while the board or owners decide whether to continue, sell or restructure the business.
The purpose should be defined before coverage is selected. “We want $2 million because it sounds reasonable” is weaker than documenting the actual economic exposure the company is trying to finance.
How Much Key-Person Coverage Might a Business Evaluate?
There is no universal formula that produces the right amount. A useful analysis combines several methods and then checks the result against the business’s actual continuity plan and what an insurer is willing to underwrite.
Method 1: Revenue-at-risk approach
Estimate the annual revenue meaningfully dependent on the key person and how long the business expects the disruption to last. This method is especially useful for founders, major sales producers and relationship managers.
Method 2: Profit-contribution approach
Estimate how much annual profit or contribution margin is attributable to the person and multiply that by the expected replacement or transition period. Add recruiting and transition expenses.
Method 3: Replacement-cost approach
Estimate executive-search fees, signing incentives, temporary consultants, training, relocation and the cost of operating below normal capacity until a replacement is effective.
Method 4: Debt and financing exposure
If lenders or investors have identified the person as central to the business, include the liquidity that could be needed to satisfy covenants, repay debt, reassure creditors or preserve runway.
The exposure planner above combines these ideas for educational purposes. It should be treated as a discussion tool, not a recommendation for a specific face amount.
Key-Person Life Insurance vs. Key-Person Disability Insurance
Death is not the only way a business can lose access to a critical person. A founder could survive a serious illness or injury but be unable to work for months or years.
| Issue | Key-person life insurance | Key-person disability coverage |
|---|---|---|
| Primary trigger | Covered death of the insured person | Covered disability under the policy’s definition |
| Typical business concern | Permanent loss, transition, debt, liquidity | Extended absence, temporary replacement, lost productivity or revenue |
| Timing | Death benefit after an eligible claim | May involve an elimination/waiting period and defined benefit period |
| Policy details to scrutinize | Term, amount, ownership, beneficiary, underwriting | Definition of disability, waiting period, benefit amount, duration and exclusions |
Key-Person Insurance vs. Personal Life Insurance
Personal life insurance protects personal beneficiaries such as a spouse, children or other dependents. Key-person insurance protects the business. A founder can therefore have personal life insurance for family needs and a separate business-owned policy addressing the company’s exposure.
Key-Person Insurance vs. Buy-Sell Funding
These concepts are often confused. Key-person insurance addresses the economic damage caused by losing an important person. Insurance used to fund a buy-sell agreement addresses an ownership-transfer obligation after an owner’s death.
The same individual can create both problems. If a 50% owner also produces 60% of sales, the company may need to address both business continuity and how that owner’s interest will be transferred. The legal agreements and policy ownership should be coordinated rather than treated as interchangeable.
Term vs. Permanent Life Insurance for a Key Person
Term insurance can fit a temporary risk—for example, while a loan is outstanding, a founder is central to a growth phase or succession planning is being developed. Permanent insurance may remain in force longer and can include cash-value features, but it is generally more complex and can be materially more expensive.
The business should start with the duration of the risk rather than choosing a product first. If the exposure is expected to decline as management depth improves, a long permanent structure may not solve the actual problem efficiently.
Employee Notice and Consent Matter
Employer-owned life insurance has federal tax rules that deserve attention before a policy is issued. IRS guidance under Internal Revenue Code section 101(j) describes written notice and consent requirements for employer-owned life insurance contracts. The employee must generally be notified in writing that the employer intends to insure the employee, informed of the maximum face amount, consent in writing, and be told that the employer will be a beneficiary.
The IRS also explains that owner-employees are not automatically exempt from these written notice and consent requirements. Businesses should coordinate the process with their tax and legal advisers and keep the documentation with the policy records.
Form 8925 and Employer-Owned Life Insurance Reporting
The IRS uses Form 8925 to report information about certain employer-owned life insurance contracts issued after August 17, 2006, including the number of employees insured and the total amount of insurance in force. This is one reason key-person insurance should not be treated as a simple “buy a policy and forget it” transaction.
Are Key-Person Premiums Tax Deductible?
Do not assume the premiums are deductible simply because the policy serves a business purpose. IRS Publication 334 explains that a business generally cannot deduct life-insurance premiums when it is directly or indirectly a beneficiary under the contract. That rule is highly relevant to the typical key-person structure where the business is beneficiary.
Death-benefit tax treatment can also involve special rules for employer-owned contracts, including section 101(j). Because ownership, consent, transfer and use of proceeds can matter, tax conclusions should be confirmed for the actual policy and business structure rather than copied from a generic article.
What Determines the Cost?
Pricing depends on the insured person and policy design. Underwriting can consider age, health, medical history, tobacco use, occupation and other risk factors. The requested face amount, policy type and duration also matter.
That is why a single “average key-person insurance cost” is often not very useful. A healthy 35-year-old executive seeking 10-year term coverage can present a very different risk from an older executive seeking a larger permanent policy.
What If the Key Person Leaves the Company?
This should be discussed before purchase. Depending on the contract and business objectives, the company may consider keeping the policy, reducing coverage, cancelling it, allowing it to lapse, or transferring ownership when permitted and appropriate. Permanent policies can add cash-value and transfer considerations.
Do not improvise a transfer after the employee leaves without reviewing policy, tax and legal consequences.
Insurance Is Not a Substitute for Succession Planning
A death benefit creates cash. It does not recreate knowledge, leadership or customer trust. The strongest key-person strategy also reduces dependence on one individual.
- Cross-train employees: critical responsibilities should have backup coverage.
- Document processes: key operating procedures, client history and decision logic should not live only in one person’s memory.
- Diversify relationships: important customers, suppliers, lenders and investors should know more than one representative of the company.
- Create interim authority: decide who can approve payments, sign contracts and make emergency decisions.
- Protect credentials and access: critical systems should not become inaccessible because one person is unavailable.
- Build management depth: develop successors before a crisis.
When to Review the Coverage
Key-person exposure changes as a company grows. Review the analysis after major events such as:
- Large revenue growth or decline.
- New loans or lender requirements.
- Fundraising or a new investor.
- Acquisition or expansion.
- Ownership or executive changes.
- A major customer becoming concentrated with one employee.
- Successful cross-training that reduces dependence on the insured person.
Key-Person Insurance Checklist
- Identify the people whose loss could materially affect the business.
- Estimate revenue, profit, debt and customer relationships exposed to each person.
- Estimate realistic replacement and transition time.
- Calculate recruiting, consulting and training costs.
- Review available cash reserves and credit lines.
- Separate death risk from disability risk.
- Decide whether the risk is temporary or long-term.
- Coordinate policy ownership and beneficiary design with legal documents.
- Complete required employee notice and consent before issuance where applicable.
- Review tax reporting, including Form 8925 where applicable.
- Build succession and knowledge-transfer plans alongside insurance.
- Recalculate the exposure at renewal and after major business changes.
Questions to Ask an Insurance or Financial Professional
- What business exposure are we trying to insure, and how was the amount calculated?
- Why is this policy type and term appropriate for that exposure?
- What underwriting evidence will the insurer require to justify the face amount?
- Who should own the policy and who should be beneficiary?
- What notice and consent documentation is required before issue?
- What tax reporting applies to this employer-owned contract?
- What happens if the insured employee leaves, retires or changes roles?
- Should disability exposure be addressed separately?
- How often should the business re-evaluate the amount?
Official Sources to Verify
For definitions and current regulatory context, see the NAIC insurance glossary. For federal employer-owned life-insurance notice, consent and reporting rules, review IRS Notice 2009-48, Form 8925 guidance, and the IRS small-business tax guidance relevant to life-insurance premiums.
Bottom Line
Key-person insurance is most useful when it is tied to a clearly documented business-continuity problem. Identify what would be lost, estimate how long disruption could last, compare that exposure with available reserves, then decide whether insurance should finance part of the gap.
The strongest plan combines appropriate coverage with succession planning, shared customer relationships, documented processes and management depth. Insurance can provide liquidity; continuity planning determines how effectively the business uses it.
This article is general educational information, not individualized insurance, legal or tax advice. Policy terms, insurable-interest requirements, notice and consent rules, tax treatment and reporting obligations can depend on the facts and jurisdiction. Review the actual contract and coordinate material decisions with qualified insurance, tax and legal professionals.
Key terms in this guide
Tap a term to review the plain-English meaning while you read.
Premium
The amount charged for insurance coverage, usually paid monthly, quarterly or annually.
Deductible
The amount you may need to pay toward a covered loss before the insurer pays under the policy, subject to the policy terms.
Exclusion
A policy provision that removes specified situations, causes, property, people or losses from coverage.
Beneficiary
The person, trust or organization designated to receive eligible policy proceeds, such as a life-insurance death benefit.
Underwriting
The process an insurer uses to evaluate risk and decide whether and on what terms to offer coverage.
Claim
A request for payment or benefits under an insurance policy after an event that may be covered.
Did the guide make sense?
Answer two quick questions. Your score stays in this browser.
Verify Current Rules
Insurance rules, benefits and product terms can change. These official resources are useful starting points for checking current requirements; they do not replace your policy documents or jurisdiction-specific advice.
Thanks — your response is saved in this browser.
Continue learning, not just scrolling
Follow a practical path from understanding the idea to comparing options and preparing for real-world decisions.
 StartWorkers’ Compensation Insurance Guide: Coverage, Benefits, Costs, and Employer ResponsibilitiesBuild the foundation →
 CompareOwn-Occupation vs. Any-Occupation Disability Insurance: How the Definitions Change a ClaimCompare your options →
 PlanMedicare Advantage 2026: A Plan-Comparison Checklist for Networks, Drugs, and CostsUnderstand the numbers →
 ActInvisible and Autoimmune Disability Claims: Building Evidence Around FunctionBe ready for a claim →
Leave a Comment
Share a helpful question or experience. Your email address will not be published.