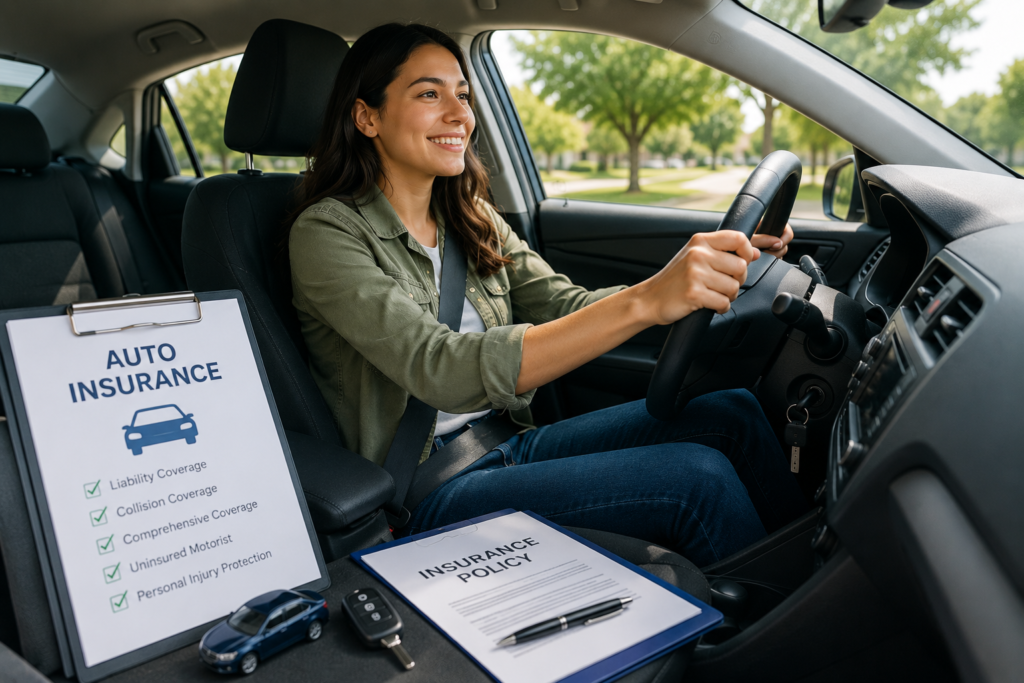
Buying your first car is an exciting milestone, but it also comes with new responsibilities. One of the most important is purchasing auto insurance. If you’ve never bought insurance before, the different coverage options and insurance terms can seem confusing.
What you’ll understand
- What Is Auto Insurance?
- Auto Coverage Scenario Checker
- Why First-Time Drivers Need Auto Insurance
This guide explains how auto insurance works in simple language, helping first-time drivers understand the basics and make informed decisions.
What Is Auto Insurance?
Auto insurance is a contract between you and an insurance company. In exchange for paying a premium, the insurer agrees to help cover certain financial losses if your vehicle is involved in a covered event, such as an accident, theft, or weather-related damage.
The type and amount of coverage depend on the policy you choose.
Auto Coverage Scenario Checker
Choose an incident to see which part of an auto policy is commonly worth reviewing.
This tool identifies common coverage areas to review. It does not determine whether a claim is covered; policy wording, deductibles, limits, exclusions and local law control.
Why First-Time Drivers Need Auto Insurance
For most drivers, auto insurance is more than just a legal requirement—it also provides financial protection.
A policy may help pay for:
- Damage to your vehicle
- Damage you cause to another person’s property
- Medical expenses after a covered accident
- Legal costs related to covered claims
- Theft or damage from certain non-collision events
Without insurance, you could be responsible for paying these costs yourself.
How Auto Insurance Works
Understanding the basic process can make insurance easier to manage.
1. Choose Your Coverage
Select the coverages that match your driving needs, budget, and state requirements.
2. Receive a Quote
Insurance companies calculate your premium based on several factors, including:
- Age
- Driving experience
- Vehicle type
- Location
- Annual mileage
- Driving history
3. Purchase the Policy
Once you accept a quote, your policy becomes active after payment and the effective date.
4. Drive Safely
Your insurance remains active as long as premiums are paid on time.
5. File a Claim if Needed
If a covered accident or loss occurs, notify your insurance company promptly. The insurer will review the claim and determine what is covered under your policy.
Common Types of Auto Insurance Coverage
Liability Coverage
Liability insurance helps pay for injuries or property damage you cause to others in a covered accident. In many places, this is the minimum coverage required by law.
Collision Coverage
Collision insurance helps pay to repair or replace your vehicle after a collision with another vehicle or object, regardless of who is at fault.
Comprehensive Coverage
Comprehensive insurance covers many non-collision events, such as:
- Theft
- Fire
- Vandalism
- Falling objects
- Certain weather-related damage
Personal Injury Protection (PIP) or Medical Payments
Depending on your location, these coverages may help pay medical expenses for you and your passengers after a covered accident.
Uninsured or Underinsured Motorist Coverage
This coverage may help if you’re involved in an accident with a driver who has little or no insurance.
What Is a Deductible?
A deductible is the amount you agree to pay out of pocket before your insurance coverage applies to certain claims.
For example:
- Repair cost: $2,000
- Deductible: $500
Your insurance may cover the remaining eligible amount after the deductible, subject to your policy terms.
Factors That Affect Your Premium
Insurance companies consider many factors when determining your premium.
These often include:
- Your age
- Driving experience
- Driving record
- Vehicle make and model
- ZIP code
- Annual mileage
- Coverage limits
- Deductible amount
Every insurer uses its own rating methods, so premiums can vary.
Tips for First-Time Drivers
If you’re buying auto insurance for the first time, these tips may help:
- Compare quotes from multiple insurers.
- Understand what each policy covers.
- Don’t focus only on the lowest price.
- Choose a deductible you can comfortably afford.
- Ask about available discounts.
- Review your policy every year.
Common Mistakes to Avoid
Many first-time drivers make avoidable mistakes, including:
- Buying coverage without comparing options.
- Choosing limits that may not meet their needs.
- Ignoring deductibles.
- Not reading policy exclusions.
- Forgetting to update the insurer after major life changes.
Frequently Asked Questions
Is auto insurance required?
Requirements vary by location. In many places, drivers must carry at least a minimum amount of liability insurance.
Can first-time drivers get affordable insurance?
Yes. Comparing quotes, maintaining a clean driving record, and asking about discounts may help reduce costs.
What happens if I miss a payment?
Missing payments could result in cancellation or a lapse in coverage, depending on your insurer’s terms.
Should I buy full coverage?
The right coverage depends on your vehicle, financial situation, and personal needs. Consider reviewing your options carefully before making a decision.
Final Thoughts
Auto insurance is designed to help protect you financially when unexpected events occur. As a first-time driver, understanding how policies work, what they cover, and how premiums are calculated can help you choose coverage with confidence.
Take time to compare policies, understand the details, and select protection that fits your needs and budget.
Key terms in this guide
Tap a term to review the plain-English meaning while you read.
Premium
The amount charged for insurance coverage, usually paid monthly, quarterly or annually.
Deductible
The amount you may need to pay toward a covered loss before the insurer pays under the policy, subject to the policy terms.
Exclusion
A policy provision that removes specified situations, causes, property, people or losses from coverage.
Claim
A request for payment or benefits under an insurance policy after an event that may be covered.
Liability
Legal responsibility for injury, damage or loss suffered by another person or organization.
Comprehensive Coverage
Auto coverage that commonly addresses certain non-collision losses such as theft, fire or weather damage, subject to policy terms.
Did the guide make sense?
Answer two quick questions. Your score stays in this browser.
Verify Current Rules
Insurance rules, benefits and product terms can change. These official resources are useful starting points for checking current requirements; they do not replace your policy documents or jurisdiction-specific advice.
Thanks — your response is saved in this browser.
Continue learning, not just scrolling
Follow a practical path from understanding the idea to comparing options and preparing for real-world decisions.
 StartWorkers’ Compensation Insurance Guide: Coverage, Benefits, Costs, and Employer ResponsibilitiesBuild the foundation →
 CompareBehavioral Health Riders in Disability Insurance: Limits, Definitions, and What to CompareCompare your options →
 PlanMedicare Advantage 2026: A Plan-Comparison Checklist for Networks, Drugs, and CostsUnderstand the numbers →
 ActInvisible and Autoimmune Disability Claims: Building Evidence Around FunctionBe ready for a claim →
Leave a Comment
Share a helpful question or experience. Your email address will not be published.