Introduction
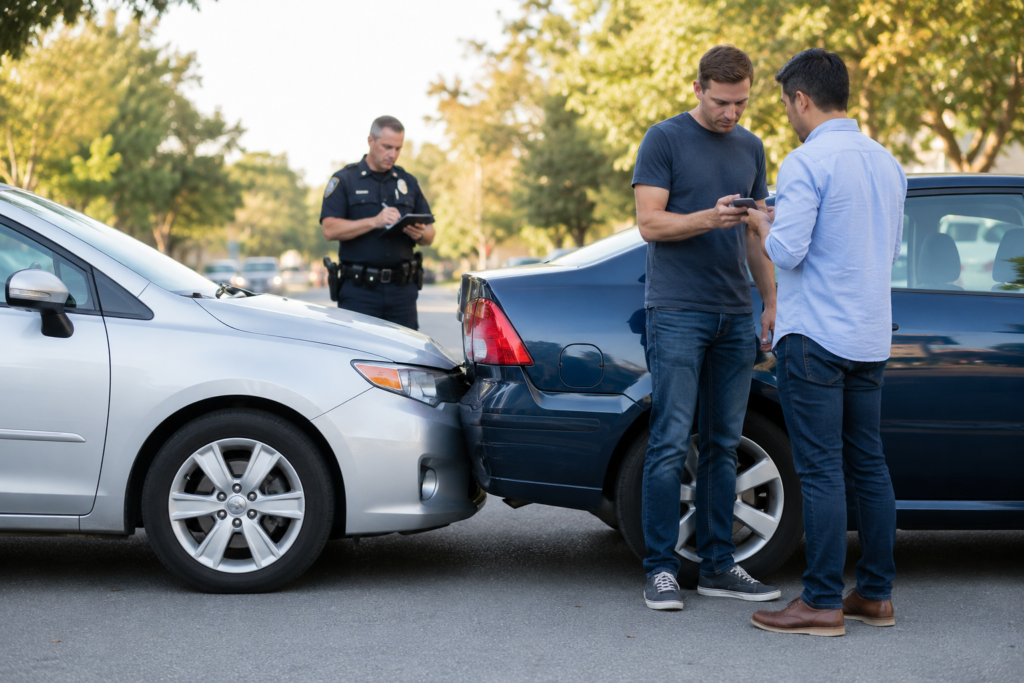
Lending your car to a friend, family member, or colleague may seem harmless, but what happens if they get into an accident while driving your vehicle? Many car owners assume the driver’s insurance will automatically cover the damages, but in most cases, insurance follows the vehicle rather than the driver.
What you’ll understand
- Introduction
- Does Insurance Cover Someone Else Driving Your Car?
- Auto Coverage Scenario Checker
Understanding how auto insurance works when someone else is behind the wheel can help you avoid unexpected financial and legal complications.
Does Insurance Cover Someone Else Driving Your Car?
In many situations, yes. Most standard auto insurance policies provide coverage when you give someone permission to drive your vehicle.
This is known as permissive use, which means the driver had your consent to use the car. If an accident occurs, your insurance policy is generally the first source of coverage.
Auto Coverage Scenario Checker
Choose an incident to see which part of an auto policy is commonly worth reviewing.
This tool identifies common coverage areas to review. It does not determine whether a claim is covered; policy wording, deductibles, limits, exclusions and local law control.
However, the exact outcome depends on:
- Your insurance policy terms
- The driver’s insurance coverage
- The cause of the accident
- State laws where the accident occurred
Who Pays for the Damage?
Your Insurance Usually Pays First
When someone else causes an accident while driving your car with permission, your auto insurance policy is typically considered the primary coverage.
This may include:
- Property damage liability
- Bodily injury liability
- Collision coverage (if purchased)
- Medical payments coverage (if included)
The claim is generally filed under your policy because the vehicle is insured under your name.
The Driver’s Insurance May Help
If damages exceed your policy limits, the driver’s personal auto insurance may act as secondary coverage in some situations.
This can provide additional protection when accident costs are substantial.
What If the Driver Was at Fault?
If the person driving your car caused the accident:
Property Damage Claims
Your liability coverage may pay for damage to the other person’s vehicle or property.
Injury Claims
Your insurance may cover medical expenses and injury-related claims from other parties involved in the accident.
Deductibles Apply
If your vehicle needs repairs under collision coverage, you may be responsible for paying the deductible.
When Coverage May Be Denied
Insurance companies may deny coverage in certain circumstances.
Unauthorized Use
If someone took your vehicle without permission, your insurer may refuse coverage under permissive-use provisions.
Excluded Drivers
Some policies specifically exclude certain individuals from driving the insured vehicle.
If an excluded driver causes an accident, coverage may be limited or denied.
Illegal Activities
Coverage issues can arise if the driver was:
- Driving under the influence
- Participating in illegal activities
- Operating the vehicle without a valid license
Will Your Insurance Rates Increase?
Possibly.
Even if you were not driving, an at-fault accident involving your insured vehicle can affect your claims history.
Insurance companies evaluate:
- Claim amounts
- Accident severity
- Driver history
- Overall risk profile
As a result, premiums may increase when your policy renews.
What Should You Do After the Accident?
If someone else crashes your car:
1. Ensure Safety
Check for injuries and call emergency services if necessary.
2. Contact Law Enforcement
A police report can help document the accident details.
3. Gather Information
Collect:
- Driver’s license details
- Insurance information
- Vehicle details
- Witness contact information
- Photos of the accident scene
4. Notify Your Insurance Company
Report the accident as soon as possible and provide accurate information about who was driving.
5. Cooperate During the Investigation
Your insurer may request statements, documents, and additional details before processing the claim.
Tips Before Letting Someone Drive Your Car
Before handing over your keys:
- Verify the driver has a valid license.
- Confirm they are experienced and responsible.
- Understand your insurance policy’s permissive-use rules.
- Review coverage limits and exclusions.
- Avoid lending your vehicle to high-risk drivers.
A few minutes of preparation can prevent significant financial headaches later.
Final Thoughts
When someone else drives your car and causes an accident, your auto insurance policy is often the first line of protection. While coverage is commonly available when you give permission, every policy contains specific terms, limits, and exclusions.
Before allowing others to use your vehicle, review your insurance policy carefully and understand how coverage applies. Knowing the rules ahead of time can help protect both your finances and your peace of mind if an accident occurs.
Key terms in this guide
Tap a term to review the plain-English meaning while you read.
Premium
The amount charged for insurance coverage, usually paid monthly, quarterly or annually.
Deductible
The amount you may need to pay toward a covered loss before the insurer pays under the policy, subject to the policy terms.
Policy Limit
The maximum amount an insurer may pay for a covered loss or category of loss under the policy.
Exclusion
A policy provision that removes specified situations, causes, property, people or losses from coverage.
Claim
A request for payment or benefits under an insurance policy after an event that may be covered.
Liability
Legal responsibility for injury, damage or loss suffered by another person or organization.
Did the guide make sense?
Answer two quick questions. Your score stays in this browser.
Verify Current Rules
Insurance rules, benefits and product terms can change. These official resources are useful starting points for checking current requirements; they do not replace your policy documents or jurisdiction-specific advice.
Thanks — your response is saved in this browser.
Continue learning, not just scrolling
Follow a practical path from understanding the idea to comparing options and preparing for real-world decisions.
 StartWorkers’ Compensation Insurance Guide: Coverage, Benefits, Costs, and Employer ResponsibilitiesBuild the foundation →
 CompareOwn-Occupation vs. Any-Occupation Disability Insurance: How the Definitions Change a ClaimCompare your options →
 PlanMedicare Advantage 2026: A Plan-Comparison Checklist for Networks, Drugs, and CostsUnderstand the numbers →
 ActInvisible and Autoimmune Disability Claims: Building Evidence Around FunctionBe ready for a claim →
Leave a Comment
Share a helpful question or experience. Your email address will not be published.