Introduction
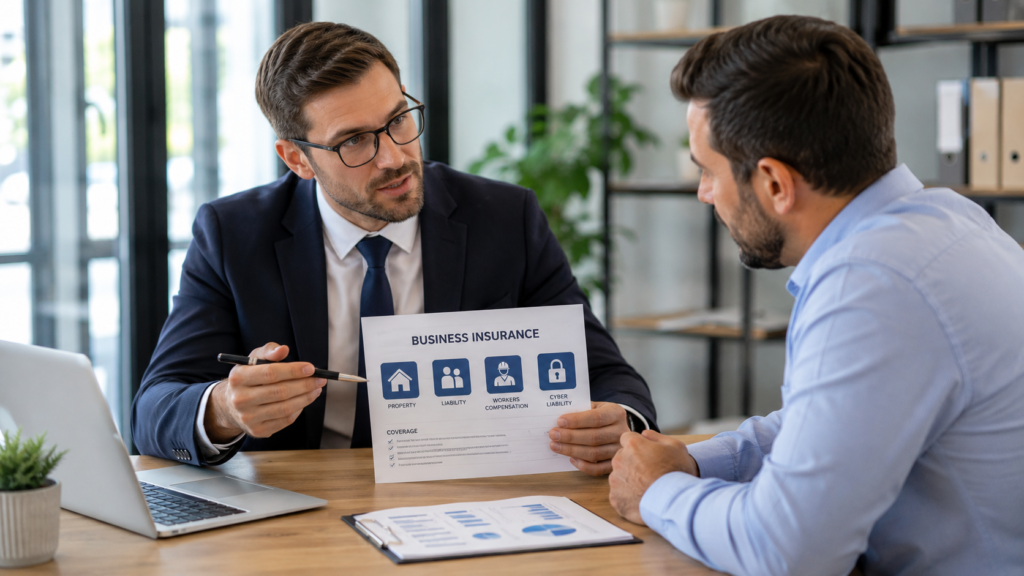
Running a business involves opportunities, growth, and risk. Whether you operate a small local shop, an online store, a consulting firm, or a large company, unexpected events such as lawsuits, property damage, cyberattacks, employee injuries, or natural disasters can lead to significant financial losses. Business insurance helps reduce these risks by providing financial protection against covered events.
What you’ll understand
- Introduction
- Table of Contents
- What Is Business Insurance?
Choosing the right insurance policy is an important part of responsible business management. The right coverage can help your business recover after unexpected incidents, maintain customer confidence, and comply with legal or contractual requirements.
This guide explains what business insurance is, how it works, the most common types of coverage, what it typically includes and excludes, and how to choose the right policy for your business.
Table of Contents
- What Is Business Insurance?
- Why Business Insurance Matters
- How Business Insurance Works
- Types of Business Insurance
- What Business Insurance Covers
- Common Exclusions
- How Much Business Insurance Costs
- Factors That Affect Premiums
- How to Choose the Right Coverage
- Tips to Reduce Business Risks
- Frequently Asked Questions
- Conclusion
What Is Business Insurance?
Business insurance is a collection of insurance policies designed to protect businesses from financial losses resulting from accidents, lawsuits, property damage, theft, cyber incidents, and other covered risks.
Business Insurance Risk Explorer
Select the exposures that apply to your business.
This is an educational risk-mapping tool, not a coverage recommendation. Requirements and suitable limits depend on the business, contracts, jurisdiction and policy terms.
Rather than relying on a single policy, businesses often combine different types of insurance based on their industry, size, number of employees, assets, and operational risks.
Why Business Insurance Matters
Business insurance helps:
- Protect business assets
- Reduce financial losses
- Cover legal expenses
- Maintain business continuity
- Meet contractual obligations
- Increase customer and investor confidence
- Protect employees
- Support long-term business growth
How Business Insurance Works
A business owner purchases a policy and pays a premium. If a covered event occurs, the business files a claim. After reviewing the claim, the insurer may pay covered repair costs, legal expenses, medical costs, settlements, or replacement costs according to the policy terms, limits, and deductible.
Types of Business Insurance
General Liability Insurance
Protects against third-party claims involving:
- Bodily injury
- Property damage
- Advertising injury
- Legal defense costs
Commercial Property Insurance
Helps protect business property, including:
- Buildings
- Equipment
- Furniture
- Inventory
- Computers
- Office contents
Professional Liability Insurance
Also called Errors & Omissions (E&O) insurance, this coverage helps protect businesses that provide professional services against claims of negligence, mistakes, or failure to deliver promised services.
Workers’ Compensation Insurance
Provides benefits for employees who suffer work-related injuries or illnesses, where required by law.
Coverage may include:
- Medical expenses
- Lost wages
- Rehabilitation
- Disability benefits
Business Interruption Insurance
Helps replace lost income if a covered event temporarily interrupts normal business operations.
Commercial Auto Insurance
Covers vehicles owned or used by the business for covered accidents, liability, and certain physical damage.
Cyber Insurance
Helps businesses recover from covered cyber incidents such as:
- Data breaches
- Ransomware attacks
- Network interruptions
- Customer notification costs
- Cyber investigations
Product Liability Insurance
Designed for businesses that manufacture, distribute, or sell products. It can help protect against claims that a product caused injury or property damage.
What Business Insurance Typically Covers
Depending on the policy, business insurance may cover:
- Property damage
- Fire and smoke damage
- Theft and vandalism
- Certain weather-related losses
- Third-party injuries
- Legal defense costs
- Employee injuries (under applicable policies)
- Equipment damage
- Business interruption
- Cyber incidents (with cyber coverage)
Common Exclusions
Most business insurance policies do not cover:
- Intentional acts
- Fraud
- Criminal activity
- Normal wear and tear
- Maintenance issues
- Certain floods or earthquakes unless separately insured
- Undisclosed business activities
- Losses exceeding policy limits
Always review policy documents carefully to understand exclusions.
How Much Business Insurance Costs
Premiums vary based on several factors, including:
- Industry
- Business size
- Annual revenue
- Number of employees
- Claims history
- Business location
- Property value
- Coverage limits
- Deductible amount
- Type of operations
Higher-risk businesses generally pay higher premiums than businesses with lower exposure to claims.
How to Choose the Right Business Insurance
Consider:
- Your industry risks
- Business assets
- Number of employees
- Legal requirements
- Client contract requirements
- Cybersecurity exposure
- Budget
- Potential financial impact of a major claim
Comparing multiple quotes and reviewing coverage annually can help ensure your insurance continues to meet your business needs.
Tips to Reduce Business Risks
- Maintain workplace safety programs.
- Train employees regularly.
- Secure business data with strong cybersecurity practices.
- Keep equipment properly maintained.
- Document business assets.
- Review insurance policies every year.
- Develop a business continuity plan.
- Report incidents promptly.
Frequently Asked Questions
Is business insurance required by law?
Some types, such as workers’ compensation or commercial auto insurance, may be legally required depending on your location and business operations. Other coverages may be optional but highly recommended.
Do small businesses need insurance?
Yes. Even small businesses can face lawsuits, property damage, cyber incidents, or customer injury claims that could result in significant financial losses.
What is a Business Owner’s Policy (BOP)?
A Business Owner’s Policy typically combines general liability insurance and commercial property insurance into one policy, often with optional additional coverages.
Does business insurance cover cyberattacks?
Generally, cyber incidents are covered only if your business has a cyber insurance policy or endorsement that includes those risks.
How often should I review my business insurance?
Review your coverage at least once a year and whenever your business experiences significant changes, such as expansion, hiring employees, purchasing equipment, or adding new services.
Conclusion
Business insurance plays a critical role in protecting companies from unexpected financial losses. Whether you’re a startup, a growing small business, or an established enterprise, the right combination of insurance policies can help safeguard your assets, employees, customers, and long-term success.
By understanding your risks, comparing coverage options, and reviewing your policies regularly, you can build an insurance strategy that supports your business as it grows.
Related insurance guides
- Business Insurance Explained: A Practical Guide for Small Businesses
- Commercial Property Insurance Guide: What It Covers and How It Protects Your Business
Key terms in this guide
Tap a term to review the plain-English meaning while you read.
Premium
The amount charged for insurance coverage, usually paid monthly, quarterly or annually.
Deductible
The amount you may need to pay toward a covered loss before the insurer pays under the policy, subject to the policy terms.
Policy Limit
The maximum amount an insurer may pay for a covered loss or category of loss under the policy.
Exclusion
A policy provision that removes specified situations, causes, property, people or losses from coverage.
Endorsement
A document that changes, adds to or removes terms from the standard insurance policy.
Claim
A request for payment or benefits under an insurance policy after an event that may be covered.
Did the guide make sense?
Answer two quick questions. Your score stays in this browser.
Verify Current Rules
Insurance rules, benefits and product terms can change. These official resources are useful starting points for checking current requirements; they do not replace your policy documents or jurisdiction-specific advice.
Thanks — your response is saved in this browser.
Continue learning, not just scrolling
Follow a practical path from understanding the idea to comparing options and preparing for real-world decisions.
 StartCopays vs. Coinsurance Explained: What’s the Difference and Which Costs You More?Build the foundation →
 CompareCyber Insurance 2.0: Why Your 2026 Policy Now Requires “Proof of Defense”Compare your options →
 PlanMedicare Advantage 2026: A Plan-Comparison Checklist for Networks, Drugs, and CostsUnderstand the numbers →
 ActInvisible and Autoimmune Disability Claims: Building Evidence Around FunctionBe ready for a claim →
Leave a Comment
Share a helpful question or experience. Your email address will not be published.