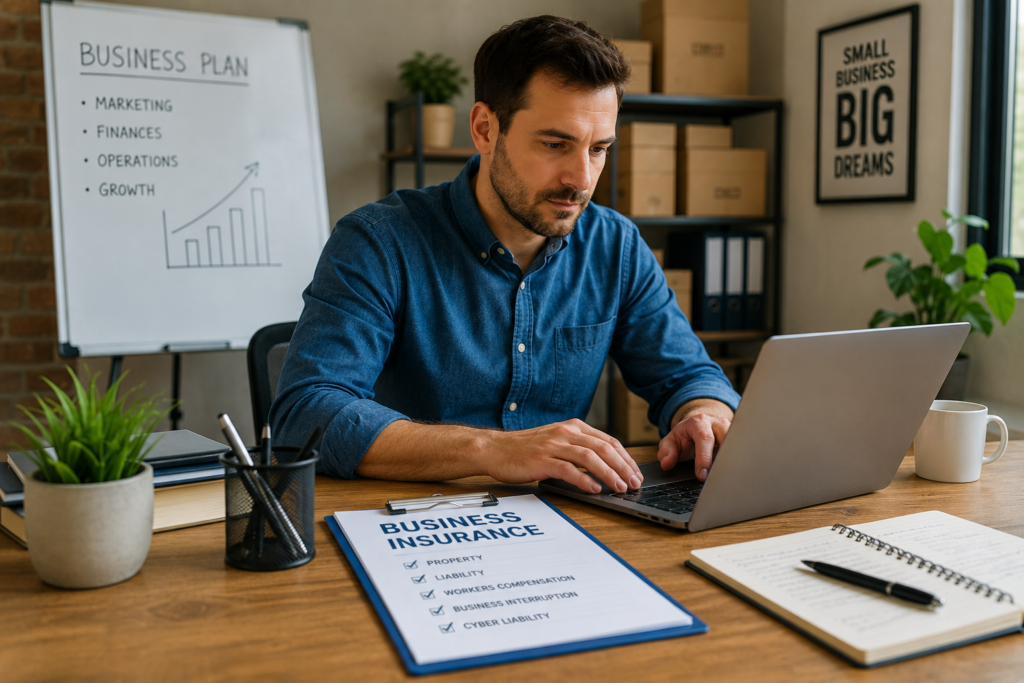
Starting and running a small business is exciting, but it also comes with responsibilities and risks. Whether you own a retail shop, restaurant, consulting firm, online store, or home-based business, unexpected events can affect your operations and finances.
What you’ll understand
- What Is Business Insurance?
- Business Insurance Risk Explorer
- Why Business Insurance Is Important
Business insurance helps reduce the financial impact of covered incidents, allowing you to focus on growing your business with greater confidence. This guide explains the basics of business insurance, the most common types of coverage, and how to choose a policy that fits your business needs.
What Is Business Insurance?
Business insurance is a collection of insurance policies designed to help protect businesses from financial losses caused by covered events. Depending on your policy, it may help cover property damage, legal claims, employee-related risks, business interruptions, and other unexpected situations.
Different businesses face different risks, so the right coverage depends on factors such as your industry, company size, location, and daily operations.
Business Insurance Risk Explorer
Select the exposures that apply to your business.
This is an educational risk-mapping tool, not a coverage recommendation. Requirements and suitable limits depend on the business, contracts, jurisdiction and policy terms.
Why Business Insurance Is Important
Even a small incident can lead to significant expenses. Business insurance provides financial protection that can help your company recover from unexpected challenges.
Some common benefits include:
- Helps protect business assets.
- May reduce the financial impact of lawsuits.
- Helps businesses recover after covered property damage.
- Supports business continuity after certain covered events.
- Can improve credibility with customers and business partners.
- Some policies may be required by law or contracts.
Common Types of Business Insurance
General Liability Insurance
General liability insurance helps protect your business if a third party claims bodily injury, property damage, or personal injury resulting from your business operations.
This is one of the most common types of coverage for small businesses.
Professional Liability Insurance
Also known as Errors and Omissions (E&O) insurance, professional liability insurance may help protect businesses that provide professional advice or services if a client claims financial loss due to errors, omissions, or negligence.
Commercial Property Insurance
Commercial property insurance helps protect business-owned buildings, equipment, furniture, inventory, and other physical assets from covered risks such as fire, theft, or certain weather-related events.
Business Interruption Insurance
If your business must temporarily close because of a covered event, business interruption insurance may help replace lost income and assist with certain ongoing operating expenses during the recovery period.
Workers’ Compensation Insurance
Workers’ compensation insurance generally provides benefits to employees who suffer work-related injuries or illnesses. Requirements vary depending on your location and business type.
Commercial Auto Insurance
If your business owns or regularly uses vehicles for work, commercial auto insurance may help cover accidents, vehicle damage, and liability related to business driving.
Cyber Insurance
Businesses increasingly rely on digital systems to manage operations and customer information. Cyber insurance may help businesses recover from certain cyber incidents, including data breaches, ransomware attacks, and other technology-related risks, depending on the policy.
How to Choose the Right Business Insurance
Choosing the right coverage starts with understanding your business risks.
Consider the following:
- The type of products or services you provide.
- The number of employees you have.
- Whether customers visit your business location.
- The value of your equipment and inventory.
- Whether you own or lease business property.
- Your industry’s legal or contractual insurance requirements.
Working with a licensed insurance professional can help you identify coverage that matches your business needs.
Factors That Affect Business Insurance Costs
Insurance premiums vary because every business is different.
Common factors include:
- Business industry
- Annual revenue
- Number of employees
- Business location
- Claims history
- Coverage limits
- Deductible amount
- Value of business property
Businesses with higher risks generally pay higher premiums than businesses with lower risk profiles.
Tips for Small Business Owners
To get the most value from your business insurance:
- Compare quotes from multiple insurers.
- Understand what each policy covers.
- Review exclusions carefully.
- Update your coverage as your business grows.
- Keep detailed business records and inventory.
- Review your insurance annually.
Common Mistakes to Avoid
Many business owners purchase insurance without fully understanding their risks.
Avoid these common mistakes:
- Buying only the minimum required coverage.
- Ignoring professional liability risks.
- Underestimating the value of business property.
- Not reviewing policies after business growth.
- Assuming personal insurance covers business activities.
Frequently Asked Questions
Do all small businesses need business insurance?
Insurance needs vary depending on your business type, location, and legal requirements. Many businesses benefit from having appropriate insurance coverage.
Is business insurance legally required?
Some types of insurance, such as workers’ compensation or commercial auto insurance, may be required depending on local laws and business operations.
Can home-based businesses need insurance?
Yes. Many home-based businesses have risks that may not be covered under a standard homeowners insurance policy.
How often should I review my policy?
It’s a good idea to review your insurance annually or whenever your business experiences significant changes.
Final Thoughts
Business insurance is an important part of managing risk for any small business. While no policy can prevent unexpected events, the right coverage can help reduce financial setbacks and support business continuity.
Review your business risks regularly, compare available options, and choose coverage that aligns with your company’s current and future needs.
Key terms in this guide
Tap a term to review the plain-English meaning while you read.
Premium
The amount charged for insurance coverage, usually paid monthly, quarterly or annually.
Deductible
The amount you may need to pay toward a covered loss before the insurer pays under the policy, subject to the policy terms.
Exclusion
A policy provision that removes specified situations, causes, property, people or losses from coverage.
Claim
A request for payment or benefits under an insurance policy after an event that may be covered.
Liability
Legal responsibility for injury, damage or loss suffered by another person or organization.
Business Interruption
Coverage that may help with eligible lost income and continuing expenses after a covered event interrupts business operations.
Did the guide make sense?
Answer two quick questions. Your score stays in this browser.
Verify Current Rules
Insurance rules, benefits and product terms can change. These official resources are useful starting points for checking current requirements; they do not replace your policy documents or jurisdiction-specific advice.
Thanks — your response is saved in this browser.
Continue learning, not just scrolling
Follow a practical path from understanding the idea to comparing options and preparing for real-world decisions.
 StartWorkers’ Compensation Insurance Guide: Coverage, Benefits, Costs, and Employer ResponsibilitiesBuild the foundation →
 CompareBehavioral Health Riders in Disability Insurance: Limits, Definitions, and What to CompareCompare your options →
 PlanMedicare Advantage 2026: A Plan-Comparison Checklist for Networks, Drugs, and CostsUnderstand the numbers →
 ActInvisible and Autoimmune Disability Claims: Building Evidence Around FunctionBe ready for a claim →
Leave a Comment
Share a helpful question or experience. Your email address will not be published.