Home Blog Page 17

Invisible But Real: Navigating Autoimmune and Chronic Pain Claims in 2026

Professional living with chronic pain and an invisible autoimmune condition while managing everyday work responsibilities.

Quick Takeaway

A disability doesn’t have to be visible to interfere seriously with someone’s ability to work.

Conditions involving chronic pain, fatigue, inflammation or autoimmune disease can sometimes affect:

stamina + concentration + mobility + dexterity + attendance + ability to sit or stand + ability to work consistently.

CDC data show just how widespread chronic pain is: in 2023, 24.3% of U.S. adults experienced chronic pain, while 8.5% experienced high-impact chronic pain that frequently limited life or work activities.

But having chronic pain or an autoimmune diagnosis does not automatically qualify someone for disability benefits.

For private disability insurance, the central question is usually:

Does the medical evidence show that your condition causes functional limitations severe enough to satisfy your policy’s definition of disability?

For these “invisible” conditions, documenting what you can and cannot reliably and sustainably do can be particularly important.

Why These Claims Can Be Complicated

Consider two employees.

Both look physically healthy during a short conversation.

One can comfortably work an eight-hour day.

The other experiences:

severe fatigue after two hours + unpredictable pain flares + difficulty concentrating + inability to remain seated for long periods.

Appearance tells you very little about occupational capacity.

That’s one reason chronic pain and autoimmune disability claims can require careful documentation.

The condition may not always produce an obvious:

cast + wheelchair + surgical scar + visible injury.

But the functional consequences can still be substantial.

What Is an Autoimmune Disease?

Autoimmune diseases involve abnormal immune-system activity in which the immune system attacks the body’s own tissues.

There are many different autoimmune conditions, and their severity varies enormously.

Depending on the specific condition and individual, symptoms may involve:

  • Fatigue
  • Joint pain
  • Muscle pain
  • Inflammation
  • Weakness
  • Cognitive difficulties
  • Mobility limitations
  • Digestive problems
  • Neurological symptoms
  • Periodic flare-ups

Some people with autoimmune conditions work without significant restrictions.

Others experience substantial occupational limitations.

Therefore:

Diagnosis alone doesn’t determine disability.

What Is Chronic Pain?

Chronic pain generally refers to pain that persists or recurs over an extended period.

CDC’s National Center for Health Statistics defines chronic pain in its survey reporting based on adults reporting pain most days or every day during the previous three months. High-impact chronic pain refers to chronic pain that frequently limits life or work activities.

Chronic pain can be associated with multiple underlying conditions. CDC specifically notes that it can result from conditions including arthritis, diabetes, autoimmune disorders and past injuries.

For disability insurance, however, the diagnosis is only the beginning.

The Real Question: How Does the Condition Affect Work?

Suppose you’re an accountant.

Your job requires:

sitting 7–8 hours

concentrating on detailed financial information

meeting deadlines

using a computer continuously

maintaining accuracy.

Now suppose chronic pain prevents you from sitting for more than:

30 minutes at a time.

Medication causes significant drowsiness.

Poor sleep reduces concentration.

And flare-ups cause unpredictable absences.

Each limitation may be relevant to your ability to perform your occupation.

The claim isn’t simply:

“I experience pain.”

It’s about how that pain affects your ability to work under the policy.

Pain Is Subjective—but Its Effects Can Be Documented

There’s no universal instrument that tells an insurer:

“This person’s pain equals 82% disability.”

That doesn’t mean pain can’t be evaluated.

Documentation can address:

location + duration + frequency + intensity + aggravating factors + medication + treatment + side effects + daily activities + functional limitations.

Social Security specifically evaluates these types of factors when considering how symptoms such as pain and fatigue affect functioning.

Private disability insurers operate under their own policies, but the broader lesson is valuable:

Document function, not merely symptoms.

Autoimmune Conditions Can Fluctuate

One particularly challenging aspect of some autoimmune conditions is:

variability.

A person may have:

Monday — relatively good day

Tuesday — moderate symptoms

Wednesday — severe flare

Thursday — unable to work

Friday — partial recovery.

Someone reviewing only Monday might conclude:

“This person looks fine.”

But employment requires more than occasional capacity.

Most occupations require:

reliability + attendance + sustained performance + predictable productivity.

That’s why a longitudinal medical record can be more informative than a single snapshot.

Good Days Don’t Necessarily Mean Full Work Capacity

Imagine someone with chronic pain attends a:

two-hour family birthday party.

Does that prove they’re capable of:

40 hours of full-time employment?

Not necessarily.

The physical and cognitive demands are different.

Likewise, someone might:

drive to the grocery store

without being capable of:

sitting at a workstation eight hours per day, five days per week.

But accuracy is essential.

Claimants should never exaggerate what they cannot do.

The objective is to provide an accurate picture of:

frequency + duration + limitations + recovery time.

Fatigue Can Be as Important as Pain

Pain often receives most of the attention.

But for some chronic conditions, severe fatigue may be equally disruptive.

Suppose someone can perform a task correctly for:

45 minutes.

Afterward, they require:

two hours of rest.

That creates a very different occupational capacity from someone who can perform the same task continuously throughout the workday.

When relevant, medical documentation should therefore address:

stamina + endurance + recovery time

rather than focusing solely on pain intensity.

Cognitive Symptoms Can Affect Desk Jobs

Invisible disability isn’t only a physical-work issue.

A worker may experience difficulty with:

concentration

memory

processing speed

multitasking

decision-making.

These limitations can be particularly important for:

attorneys + accountants + programmers + engineers + executives + healthcare professionals + financial professionals.

A person doesn’t need to perform heavy physical labor to experience occupational impairment.

Your Job Description Matters

Consider two people with identical physical limitations.

Worker A

Software developer working remotely.

Worker B

Warehouse employee lifting and moving products throughout the day.

The same medical condition could affect their occupations very differently.

Disability claims therefore involve two sides:

Medical limitations

and

Occupational requirements.

A strong claim connects the two.

Document Your Actual Occupational Duties

Don’t rely entirely on a generic HR description.

A job description might simply say:

“Project Manager.”

But your actual work may require:

6 hours daily computer use + 2 hours of meetings + frequent travel + client presentations + deadline management + supervising 20 employees.

Documenting those duties can help explain why particular symptoms matter.

For example:

Difficulty sitting → affects computer work

Severe fatigue → affects full-day schedule

Cognitive problems → affect project decisions

Pain flare-ups → affect attendance

Medication drowsiness → affects concentration.

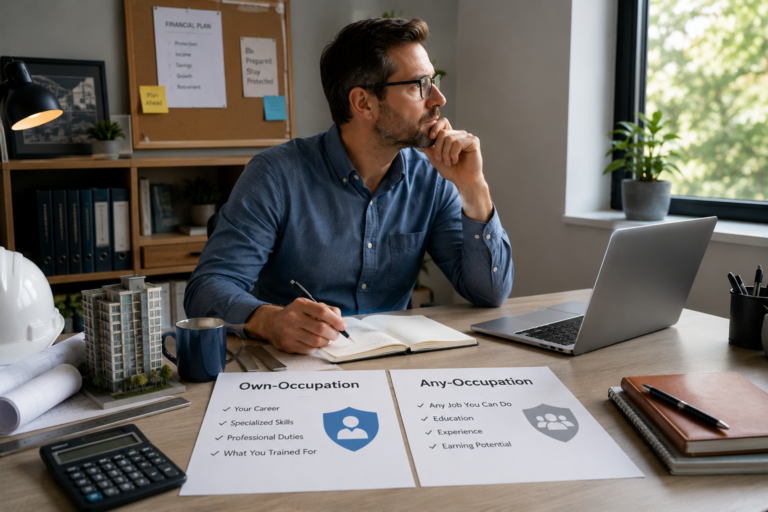
Own-Occupation vs. Any-Occupation Matters

Your policy’s disability definition can dramatically affect a claim.

Under an own-occupation standard, the initial question may focus on whether your condition prevents you from performing your particular occupation as defined by the contract.

Under an any-occupation standard, the insurer may evaluate whether you can perform other qualifying work.

Some LTD plans can also change definitions after a specified benefit period.

Therefore, find:

Definition of Disability

in your policy before assuming how your claim will be evaluated.

Example: Surgeon With an Autoimmune Condition

Imagine a surgeon develops an autoimmune condition causing:

hand pain + stiffness + fatigue.

The surgeon can still:

walk + talk + use a computer + attend meetings.

But prolonged surgical procedures requiring precise hand movements become impossible.

Under an appropriate own-occupation definition, inability to perform those specialized occupational duties could be highly relevant.

An any-occupation analysis could produce a different question:

Could this person perform another qualifying occupation?

Example: Remote Professional With Chronic Pain

Now consider a remote financial analyst.

Because the person works from home, someone might assume:

“They can still work—they don’t even commute.”

But their occupation requires:

extended sitting + sustained concentration + complex calculations + meetings + deadlines.

If documented pain and fatigue make those activities unsustainable, eliminating the commute doesn’t necessarily solve the occupational problem.

Remote work is still work.

Medical Evidence Can Make or Break the Claim

A diagnosis provides important context.

But insurers may need evidence concerning:

severity + treatment + functional impairment + duration + occupational restrictions.

Relevant records might include information from:

treating physicians + specialists + physical therapists + pain-management professionals + other appropriate healthcare providers.

Depending on the condition, objective testing may also be available.

But not every symptom can be completely quantified by a laboratory test.

What Should Medical Records Explain?

Useful documentation may address:

What is the diagnosis?

What symptoms occur?

How frequently?

How severe are they?

What triggers or worsens them?

How long do flares last?

What treatment is being provided?

How effective is treatment?

Are there medication side effects?

What activities are restricted?

How long can the person sit, stand or walk?

How much can the person lift?

How is concentration affected?

Can the person maintain a full-time schedule?

Specific functional information can be far more informative than:

“Patient unable to work.”

Treatment History Matters

Your records can help establish the history of the condition.

Depending on the circumstances, they may show:

specialist consultations

medication changes

physical therapy

diagnostic testing

pain-management treatment

hospitalization

attempts to continue working

changes in symptoms.

Consistency across records can be important.

If a policy requires regular or appropriate care, treatment requirements can also become contractually relevant.

Medication Side Effects Shouldn’t Be Ignored

Sometimes treatment itself affects occupational functioning.

For example, medication may cause:

drowsiness + dizziness + slowed thinking + gastrointestinal effects.

Those side effects may matter for someone who needs to:

drive

operate machinery

make complex decisions

or

maintain intense concentration.

If side effects are significant, discuss them accurately with your healthcare provider.

Keep a Symptom and Function Record

For fluctuating conditions, a simple contemporaneous record can help you accurately describe patterns to your healthcare team.

You might track:

Date

Pain level

Fatigue

Flare duration

Activities attempted

Work hours completed

Breaks required

Medication effects

Missed work

Recovery time.

The purpose isn’t to manufacture evidence.

It’s to prevent vague recollection from replacing accurate information.

Don’t Exaggerate

Credibility is crucial.

If you can walk:

half a mile,

don’t claim:

“I can’t walk.”

Instead, accurately explain:

how far you can walk + how long it takes + whether you need breaks + what happens afterward.

Likewise, if you can work for two hours but not eight, describe that accurately.

A disability claim doesn’t require pretending you have zero functional ability.

Partial and Residual Disability May Help

Not every condition causes complete inability to work.

Suppose you previously earned:

$8,000/month

working full-time.

Your condition now allows you to work only:

20–25 hours per week.

Your income falls to:

$4,500/month.

If your policy provides qualifying:

partial or residual disability benefits,

it may potentially help address some of the lost income.

Review these provisions before assuming you must be completely unable to work.

The Flare-Up Problem

Suppose you’re productive:

three days per week

but unpredictably unable to work:

two days per week.

Even if you’re capable on your good days, the attendance issue may still make sustained employment difficult.

Documentation should therefore capture not only:

what you can do

but:

how reliably you can do it.

For fluctuating illnesses, reliability can be one of the most important pieces of the occupational picture.

Disability Insurance vs. Social Security

Private disability insurance and SSDI are different systems.

A private policy applies its contractual:

definition of disability.

Social Security applies federal statutory and regulatory requirements.

SSA evaluates medical evidence and the effects of symptoms including pain and fatigue on a person’s functioning. Its evidentiary guidance specifically considers factors such as daily activities, symptom frequency and intensity, medication, treatment and functional limitations.

Approval under one system doesn’t automatically guarantee approval under another.

Employer LTD Claims and ERISA

Many private-sector employer disability plans are governed by ERISA, although exceptions exist.

The Department of Labor states that ERISA-covered disability plans are subject to claims-procedure requirements.

These rules matter if your claim is:

denied

or

benefits are later terminated.

DOL notes that ERISA generally requires written notice when a claim is denied and a full and fair process for reviewing that denial.

If Your Claim Is Denied

Don’t assume:

Denied = case over.

Read the denial letter carefully.

Determine:

Why was the claim denied?

Was the insurer disputing:

diagnosis?

severity?

functional limitations?

occupational requirements?

policy eligibility?

medical evidence?

definition of disability?

The reason matters because an appeal should address the actual basis for denial.

For an ERISA-covered employer plan, pay close attention to the plan’s appeal procedures and deadlines.

Your Social Media Can Lack Context

Someone with chronic pain may occasionally:

travel + attend a wedding + go to dinner + visit family.

Those activities don’t automatically establish full-time occupational capacity.

But inconsistent public statements can create questions.

If you’re claiming severe limitations while publicly describing unrestricted physical activity, an insurer may investigate the discrepancy.

The safest approach is simple:

Be accurate everywhere.

Don’t Stop Working Solely to “Prove” Disability

A disability decision should be based on your actual medical and occupational circumstances—not an attempt to create evidence.

Some people may be capable of continuing work with:

reduced hours + modified duties + remote work + ergonomic changes + other accommodations.

If appropriate, discuss options with your healthcare provider and employer.

Disability insurance is one component of the broader picture.

Workplace Accommodations May Help

Depending on the condition and job, reasonable accommodations might allow some employees to continue working.

Possible examples can include:

modified schedules

ergonomic equipment

additional breaks

remote or hybrid arrangements

changes to nonessential duties.

Employment-law rights and disability-insurance eligibility are separate questions, so one doesn’t automatically determine the other.

A Practical Example

Consider Rachel.

Age: 41
Occupation: Financial manager
Income: $120,000/year

Rachel develops an autoimmune condition.

Her major symptoms include:

joint pain + severe fatigue + intermittent cognitive difficulty.

Initially, she continues working.

Over time she begins:

missing work during flares

working shorter days

making concentration-related errors

and needing extended recovery periods.

Her specialists document the progression of symptoms and functional limitations.

Her employer LTD plan uses an own-occupation definition during the initial benefit period.

A potential claim would be evaluated by connecting:

medical evidence

functional limitations

financial manager’s occupational duties

policy definition of disability.

That connection is the heart of the claim.

What Not to Rely On

Avoid building a claim around only:

“I have an autoimmune disease.”

or:

“My pain is 9/10.”

or:

“My doctor says I’m disabled.”

Those statements can be relevant.

But a stronger evidentiary picture generally explains:

what the condition actually prevents you from doing consistently at work.

Questions to Ask Before Filing

  1. What is my exact diagnosis?
  2. What symptoms are documented?
  3. How do they affect my actual occupational duties?
  4. Does my policy use own-occupation or any-occupation?
  5. Does that definition change later?
  6. What is my elimination period?
  7. Does the policy require regular treatment?
  8. Does it provide residual disability benefits?
  9. Are there relevant exclusions or limitations?
  10. Are pre-existing-condition provisions applicable?
  11. What medical evidence does the insurer require?
  12. What occupational information is required?
  13. What is the claims deadline?
  14. What happens if the claim is denied?
  15. What appeal rights and deadlines apply?

2026 Chronic Illness Claim Checklist

Before submitting a disability claim:

  • Obtain your complete policy or plan documents.
  • Find the definition of disability.
  • Check own-occupation vs. any-occupation.
  • Review your elimination period.
  • Document your actual occupational duties.
  • Maintain appropriate medical care.
  • Document pain and fatigue accurately.
  • Document flare frequency and duration.
  • Document sitting, standing and walking limitations.
  • Document cognitive limitations when applicable.
  • Discuss medication side effects with your provider.
  • Track missed work and reduced hours.
  • Review residual/partial disability coverage.
  • Check pre-existing-condition provisions.
  • Review exclusions.
  • Follow claim deadlines.
  • Keep copies of submitted documentation.
  • Read any denial letter carefully.
  • Follow appeal deadlines if applicable.

Frequently Asked Questions

Can chronic pain qualify for disability insurance?

Potentially. The diagnosis or symptom alone doesn’t guarantee benefits. The condition generally must produce functional limitations that satisfy the policy’s definition of disability.

Can autoimmune disease qualify for LTD?

Potentially. Eligibility depends on the severity and functional effects of the condition, medical evidence, occupational duties and policy terms.

Do I need objective medical evidence?

Medical evidence is important, but the type of available evidence depends on the condition. Some symptoms cannot be measured by one definitive test. Documentation of treatment, clinical findings and functional limitations can therefore be important.

Can fatigue be considered in a disability claim?

Yes, when relevant to a medically supported condition and occupational functioning. SSA, for example, specifically evaluates the functional effects of symptoms such as pain and fatigue.

What if my symptoms come and go?

Fluctuating symptoms can still affect work capacity. Document their frequency, duration, severity, recovery time and impact on attendance and sustained performance.

Does working from home mean I can’t qualify?

Not necessarily. Remote jobs still require functional capacity, including concentration, attendance, productivity and—in many jobs—prolonged sitting or computer use.

What if I can work part-time?

Check whether your policy includes partial or residual disability benefits. Some policies may provide benefits when a qualifying disability reduces work capacity and income.

How common is chronic pain?

CDC reported that 24.3% of U.S. adults had chronic pain in 2023, and 8.5% had high-impact chronic pain that frequently limited life or work activities.

Can I appeal a denied employer LTD claim?

If your plan is subject to ERISA, federal claims-procedure protections generally include a process for reviewing denied disability claims. Follow the instructions and deadlines in your plan documents and denial notice.

Final Thoughts

An invisible condition can produce very real occupational limitations.

For autoimmune disease and chronic pain claims, the strongest question isn’t:

“How sick do I look?”

It’s:

“What can I reliably and sustainably do?”

A useful disability claim connects four things:

Medical condition → symptoms → functional limitations → occupational duties.

For fluctuating conditions, also document:

frequency + duration + bad days + recovery time + attendance problems.

And remember that the goal isn’t to prove you can do absolutely nothing.

It’s to accurately establish whether your condition prevents you from satisfying the definition of disability contained in your insurance policy.

In 2026, that distinction remains central to navigating an invisible-disability claim.
Burnout as a Disability: Can You Claim Benefits for Work-Related Stress?

Exhausted American professional taking a quiet break from a demanding workday while considering disability income protection.

Quick Takeaway

Feeling burned out at work does not automatically qualify you for disability insurance benefits.

That distinction is important.

The EEOC explains that ordinary stress caused by job or personal pressures isn’t, by itself, necessarily a mental impairment. However, stress associated with a documented mental or physical disorder may potentially constitute an impairment.

For disability insurance, the practical question is therefore usually not:

“Am I burned out?”

It is:

“Do I have a medically supported condition that prevents me from performing my occupation under my disability policy’s definition?”

A worker experiencing severe work-related distress might also have a diagnosed condition such as depression, an anxiety disorder, PTSD or another recognized condition.

If that condition produces sufficiently serious functional limitations and satisfies the insurance contract, disability benefits may potentially be available.

But burnout alone is not an automatic ticket to LTD benefits.

What Do People Mean by “Burnout”?

People commonly use burnout to describe prolonged workplace exhaustion involving symptoms such as:

  • Extreme fatigue
  • Reduced motivation
  • Difficulty concentrating
  • Emotional exhaustion
  • Reduced productivity
  • Irritability
  • Sleep problems
  • Feeling overwhelmed by work

Those experiences can be serious.

But disability insurance doesn’t generally pay simply because your job has become:

stressful + exhausting + unpleasant.

The claim needs to satisfy the policy.

Burnout vs. a Disabling Medical Condition

Consider two employees.

Employee A works extremely long hours and feels exhausted, frustrated and dissatisfied but remains capable of performing their job.

Employee B experiences severe symptoms, receives professional evaluation and is diagnosed with a mental-health condition that significantly impairs concentration, sleep, decision-making and the ability to work reliably.

These aren’t necessarily equivalent disability-insurance situations.

The second employee may have a stronger basis for a potential claim if the medical condition and functional limitations satisfy the policy.

General Work Stress Isn’t Automatically a Disability

This is where many online explanations become misleading.

The EEOC has specifically distinguished ordinary stress from stress associated with an identifiable disorder.

Its ADA guidance explains that stress by itself isn’t automatically a mental impairment, although stress may be related to a mental or physical impairment.

So telling an insurer:

“My job is incredibly stressful.”

is fundamentally different from establishing:

“I have a documented medical condition producing functional limitations that prevent me from reliably performing the material duties of my occupation.”

When Burnout May Become an Insurance Issue

Suppose a 42-year-old executive has spent several years working:

60+ hours per week + frequent travel + constant deadlines + staff management + high-pressure decisions.

Eventually, they experience serious problems with:

sleep + concentration + memory + emotional regulation + decision-making + consistent attendance.

They seek professional treatment and receive a diagnosis.

At that point, a disability claim generally wouldn’t rest simply on the word:

“burnout.”

The focus would instead be the diagnosed condition, resulting functional limitations, occupational requirements and policy language.

Depression, Anxiety and Other Mental Conditions

Some severe burnout-like experiences may overlap with recognized mental-health conditions.

The EEOC identifies conditions including major depression, PTSD, bipolar disorder and schizophrenia as conditions that will, in virtually all cases, meet the ADA definition of disability because of their effects on brain function; other mental-health conditions may qualify depending on circumstances.

But remember:

ADA protection ≠ automatic LTD approval.

Employment law and private disability insurance apply different legal and contractual standards.

Your LTD Policy Controls the Claim

Suppose your employer’s LTD policy pays:

60% of covered income.

That doesn’t mean you’ll receive 60% simply because a doctor recommends time away from work.

You still need to satisfy the policy’s:

Definition of Disability.

Find that section first.

It may use terms such as:

Regular Occupation

Own Occupation

Any Occupation

Material and Substantial Duties

Gainful Occupation.

The exact wording matters.

Own-Occupation Can Be Especially Important

Imagine you’re a senior investment professional.

Your job requires:

complex analysis + rapid decisions + constant client communication + long working hours + high financial responsibility.

A documented condition significantly reduces your:

concentration + processing speed + stress tolerance + ability to make reliable decisions.

An own-occupation provision may focus on whether you’re capable of performing the material duties of that particular occupation.

An any-occupation standard could be different.

That’s why two workers with similar symptoms can receive different claim outcomes under different policies.

Medical Documentation Matters

For a mental-health-related disability claim, insurers may evaluate medical evidence supporting both:

the condition

and

its functional effects.

Depending on the circumstances, relevant documentation may include treatment records, clinician assessments, medication history, documented symptoms, functional restrictions and information connecting those restrictions to occupational duties.

A statement such as:

“Patient is experiencing burnout”

may provide far less useful information than accurate clinical documentation explaining the underlying condition and how it affects the person’s ability to function.

Connect the Condition to Your Actual Job

Suppose you’re a software engineering director.

Your job requires you to:

lead 30 employees + review technical architecture + resolve production incidents + manage deadlines + attend executive meetings + make high-impact decisions.

The relevant question isn’t merely whether you can:

open a laptop.

It’s whether you can reliably perform the material occupational duties required under the policy.

Functional documentation might therefore address:

Sustained concentration

Memory

Decision-making

Attendance

Communication

Ability to handle deadlines

Ability to work consistently

rather than relying only on a diagnostic label.

Being Able to Work Occasionally Isn’t the Same as Working Reliably

This distinction can matter considerably.

Someone might have a good day and successfully:

answer emails + attend a meeting + complete several tasks.

That doesn’t necessarily demonstrate an ability to sustain:

40–50 hours of competitive employment every week.

Disability claims often involve questions of sustainable functional capacity, not simply whether someone can perform isolated activities.

A Doctor’s Recommendation for Leave Isn’t Automatically LTD Approval

Your treating professional may recommend:

four weeks away from work.

That may be medically appropriate.

But disability benefits are contractual.

The insurer still determines whether the evidence satisfies the policy’s definition and other requirements.

Medical leave and disability insurance should therefore be treated as related but separate issues.

Short-Term Disability May Come First

For some workers experiencing a qualifying condition, short-term disability may be the first income-protection layer.

A hypothetical sequence could look like:

Medical leave

STD

LTD if the disability continues.

Actual employer plans vary substantially.

Check:

STD waiting period + benefit percentage + maximum duration + LTD elimination period.

Make sure there isn’t an unexpected gap between benefits.

Long-Term Disability Requires a Longer View

Suppose your symptoms continue for months.

Your LTD policy might begin after:

90 or 180 days, for example.

Now the insurer may evaluate whether your condition continues to prevent you from performing your occupation.

Ongoing treatment and accurate documentation can therefore become particularly important.

Mental-Health Benefit Limits Can Change the Outcome

This is one of the biggest issues to check.

Some LTD policies impose special maximum benefit periods for certain:

mental-health or substance-use-related disabilities.

The Department of Labor’s ERISA Advisory Council has examined disparities in LTD plan designs involving limits on mental-health benefits.

So your policy might have a long general maximum benefit period while applying a shorter limit to certain mental-health claims.

Read the actual contract.

The 24-Month Issue

Some LTD contracts may impose a:

24-month maximum

on specified mental-health-related disabilities.

This isn’t universal.

Suppose you’re 40 and your LTD policy generally allows qualifying benefits potentially to retirement age.

If your claim instead falls under a 24-month mental-health limitation, your long-term financial protection could be dramatically different.

Search your plan for:

Mental Illness

Mental/Nervous Conditions

Substance Use

Limited Benefit Period

Maximum Benefit Period.

What If Your Burnout Is Specifically Caused by Your Job?

This creates another important distinction.

You might assume:

“Because work caused my condition, workers’ compensation should cover it.”

Workers’ compensation rules are governed primarily by state law, and rules concerning work-related psychological or stress claims vary significantly by jurisdiction.

Don’t assume either:

workers’ comp automatically covers it

or

workers’ comp automatically excludes it.

If work causation is central to your situation, check your state’s current requirements or obtain appropriate professional advice.

LTD May Not Require the Condition to Be Caused by Work

Private disability insurance serves a different purpose.

Depending on the policy, the central question may be whether a covered condition prevents you from working—not necessarily whether your employer caused the condition.

That means a qualifying mental-health disability could potentially arise from multiple circumstances, subject to policy exclusions and requirements.

ADA Accommodation May Be Another Option

Disability benefits aren’t always the only possible route.

If you have a qualifying disability but remain capable of performing your job with reasonable accommodation, workplace accommodation may help you remain employed.

EEOC guidance identifies potential accommodations such as modified work schedules, job restructuring and reassignment to a vacant position in appropriate circumstances.

Depending on the individual situation, an accommodation might involve changes to:

schedule + workload structure + workplace environment + leave arrangements.

Accommodation eligibility is separate from LTD eligibility.

Leave May Be More Appropriate Than LTD in Some Cases

Suppose your clinician expects you to recover after:

six weeks of treatment and rest.

A combination of:

PTO + medical leave + STD

may potentially be more relevant than long-term disability.

Conversely, if the condition produces prolonged functional impairment, LTD could become more relevant.

The appropriate path depends on:

medical circumstances + employer benefits + applicable laws + insurance terms.

Remote Work Isn’t an Automatic Solution

An employee experiencing severe work-related psychological symptoms may hear:

“Why not just work from home?”

But remote work doesn’t eliminate:

deadlines + concentration requirements + meetings + workload + decision-making + performance expectations.

For some people, remote work may help substantially.

For others, it may not address the underlying functional impairment.

Again, the analysis should focus on what the individual can reliably do.

Social Security Disability Has a Different Standard

SSDI should not be confused with private LTD.

Social Security applies federal disability requirements and evaluates medically determinable physical or mental impairments.

Its standard is substantially different from simply being unable to perform your current high-stress occupation.

For 2026, SSA says average monthly earnings of $1,690 or more for a non-blind individual are generally considered substantial, with a higher threshold for individuals who are blind under SSA rules.

Private LTD and SSDI therefore need to be evaluated separately.

Don’t Diagnose Yourself for an Insurance Claim

If you’re experiencing serious symptoms, the priority should be appropriate professional evaluation and treatment—not finding terminology that sounds more likely to produce an insurance payment.

Avoid trying to transform:

“burnout”

into a specific diagnosis yourself.

Your healthcare professional should determine the appropriate clinical diagnosis.

Then your disability insurer evaluates the resulting claim under the policy.

Don’t Exaggerate Your Limitations

Accurate documentation is essential.

Don’t say:

“I can’t do anything.”

if that isn’t true.

Instead, accurately describe:

what you can do + what you cannot do + how long you can sustain activities + what happens when symptoms worsen.

Credibility matters in disability claims.

Example: When a Claim Might Be Possible

Consider Daniel.

Age: 44
Occupation: Corporate attorney
Income: $180,000/year

After prolonged workplace pressure, Daniel experiences significant symptoms affecting:

sleep + concentration + memory + decision-making + ability to handle client interactions.

He receives appropriate professional evaluation and treatment.

His clinician documents a medical condition and functional restrictions.

His LTD policy uses an own-occupation definition during the initial benefit period.

Daniel’s insurer would evaluate whether the documented condition and restrictions satisfy that definition.

The claim isn’t:

“Daniel has burnout.”

It is based on whether his documented medical impairment prevents him from performing the occupational duties required under his contract.

Example: When Burnout Alone May Not Be Enough

Now consider Jennifer.

She dislikes her new manager.

Her workload has increased.

She’s tired and frustrated and wants several months away from work.

However, she has no identified medical impairment preventing her from performing her occupational duties.

Simply describing the situation as:

“burnout”

wouldn’t automatically establish disability.

The EEOC similarly distinguishes ordinary job or personal stress from stress arising from an identifiable mental or physical disorder.

What to Look for in Your Policy

Before relying on disability benefits for a stress-related condition, review:

Definition of Disability

Mental/Nervous Limitation

Maximum Benefit Period

Elimination Period

Own Occupation

Any Occupation

Regular Care

Pre-Existing Conditions

Exclusions

Residual Disability

Other Income Benefits

These provisions can significantly affect eligibility and benefit duration.

Employer LTD Claims and ERISA

Many private-sector employer disability plans are subject to ERISA, although important exceptions exist.

The Department of Labor explains that ERISA establishes standards for many private-industry benefit plans, including requirements concerning plan information and claims/appeal procedures.

DOL also provides specific guidance for filing disability-benefit claims and appealing adverse decisions under applicable ERISA-covered plans.

Questions to Ask HR or Your Insurer

  1. Does the plan cover qualifying mental-health conditions?
  2. How does the policy define disability?
  3. Does it require own-occupation or any-occupation disability?
  4. Is there a mental-health-specific benefit limitation?
  5. Is there a 24-month maximum for certain conditions?
  6. What is the elimination period?
  7. What medical documentation is required?
  8. Does the policy require regular treatment?
  9. Are partial or residual benefits available?
  10. What pre-existing-condition restrictions apply?
  11. What exclusions apply?
  12. How long can benefits continue?
  13. How do I file an STD claim?
  14. How do I file an LTD claim?
  15. What appeal rights apply if the claim is denied?

2026 Burnout & Disability Checklist

Before assuming work-related stress qualifies for disability benefits:

  • Don’t assume burnout itself guarantees coverage.
  • Seek appropriate professional evaluation for significant symptoms.
  • Identify any medically supported underlying condition.
  • Read your policy’s definition of disability.
  • Document your actual occupational duties.
  • Document functional limitations accurately.
  • Check STD coverage.
  • Check the LTD elimination period.
  • Review mental-health benefit limitations.
  • Check the maximum benefit period.
  • Review own-occupation vs. any-occupation language.
  • Check treatment requirements.
  • Review exclusions and pre-existing-condition provisions.
  • Investigate workplace accommodation where appropriate.
  • Check applicable leave benefits.
  • Review state workers’ compensation rules separately if the condition is work-related.
  • Understand your plan’s claims and appeals procedures.

Frequently Asked Questions

Can burnout qualify for disability insurance?

Burnout by itself doesn’t automatically establish disability. A claim may potentially qualify when a medically supported condition causes functional limitations that satisfy the policy’s definition of disability.

Can I get disability benefits just because my job is stressful?

Generally, ordinary job stress alone isn’t enough to establish a disability. EEOC guidance distinguishes general stress from stress related to an identifiable mental or physical impairment.

Can depression caused by work qualify for LTD?

Potentially. The important questions include whether the condition is medically supported, whether it causes sufficient functional impairment and whether you satisfy your LTD policy’s definition and other provisions.

Can anxiety qualify for disability benefits?

Potentially, depending on its severity, functional effects, documentation and the insurance contract. The EEOC recognizes anxiety disorders among mental impairments that can potentially qualify as disabilities under the ADA, although ADA and LTD standards aren’t identical.

Do I need a diagnosis?

Disability insurers generally require medical support for a claim. Simply self-identifying as burned out isn’t equivalent to establishing a covered medical disability.

Does a doctor’s note guarantee LTD benefits?

No. Medical evidence is important, but the insurer still evaluates whether you satisfy the policy’s contractual definition and requirements.

Are mental-health LTD benefits always limited to 24 months?

No. Some policies impose condition-specific duration limits, but terms vary considerably. Review your actual plan.

Can my employer accommodate me instead of my taking disability leave?

Potentially. Employees with qualifying disabilities may have rights to reasonable workplace accommodations under the ADA, subject to applicable requirements.

Final Thoughts

Burnout and disability aren’t automatically the same thing.

A difficult manager, excessive workload, long hours or general workplace stress may create genuine distress without necessarily satisfying a disability policy.

The situation changes when a worker has a medically supported condition producing significant functional limitations.

Then the important question becomes:

Can you reliably perform the material duties of your occupation under your policy’s definition of disability?

For a potential claim, focus on:

Medical condition → functional limitations → occupational duties → policy definition → supporting evidence.

And before relying on LTD, check for:

mental-health benefit limits + waiting periods + treatment requirements + own-occupation/any-occupation provisions + exclusions.

For work-related stress in particular, also remember that:

Disability insurance + workplace accommodation + medical leave + workers’ compensation

are separate systems with different eligibility rules.

Mental Health & Disability Insurance: What’s Covered in 2026?

American employee discussing mental health and disability income protection with a professional in 2026.

Quick Takeaway

Yes—mental health conditions can potentially qualify for disability benefits, but having a diagnosis does not automatically mean an insurance claim will be approved.

For private short-term or long-term disability insurance, coverage depends on the specific policy. The insurer typically evaluates whether a covered condition prevents you from working under the policy’s definition of disability.

There is another important issue: some long-term disability (LTD) plans place special limits on benefits arising from mental health conditions. The U.S. Department of Labor’s ERISA Advisory Council has specifically examined LTD plans that limit the duration of benefits for mental-health and substance-use conditions while some other covered disabilities may receive benefits for much longer periods.

For workers in 2026, the key questions are therefore:

Is my condition covered?

How does my policy define disability?

Is there a mental-health-specific benefit limit?

What evidence will I need for a claim?

Can Mental Health Conditions Be Considered Disabilities?

Yes.

Mental health conditions can substantially affect a person’s ability to work, even when there is no obvious physical injury.

The EEOC explains that conditions including major depressive disorder, PTSD, bipolar disorder and schizophrenia can qualify as disabilities under the Americans with Disabilities Act when applicable requirements are met. Other mental health conditions may qualify as well.

However, three different concepts need to be separated:

ADA disability

Private disability-insurance eligibility

Social Security disability

They don’t use identical standards.

Being protected as a person with a disability under employment law does not automatically mean your private LTD insurer must pay a claim.

What Mental Health Conditions Might Be Covered?

Depending on the policy and severity of functional impairment, disability claims may potentially involve conditions such as:

  • Major depressive disorder
  • Anxiety disorders
  • Post-traumatic stress disorder (PTSD)
  • Bipolar disorder
  • Obsessive-compulsive disorder
  • Panic disorder
  • Schizophrenia and related disorders
  • Other qualifying psychiatric or psychological conditions

Coverage is not guaranteed simply because a condition appears on this list.

The actual determination depends on factors including:

Policy language + diagnosis + severity + functional limitations + occupational requirements + medical evidence + exclusions and limitations.

Diagnosis vs. Disability

This is one of the most important distinctions.

Suppose two people have the same diagnosis:

Major depressive disorder.

Person A continues working full-time with treatment.

Person B experiences symptoms that severely affect:

concentration + memory + decision-making + attendance + productivity + ability to interact with others.

The diagnosis may be similar.

Their functional capacity may be very different.

Disability insurance generally focuses on whether the condition prevents you from satisfying the work requirements described by the policy’s disability definition.

Mental Health Disabilities Can Be “Invisible”

A worker experiencing a disabling mental-health condition may:

look physically healthy

walk normally

drive

have conversations

attend occasional social events.

That doesn’t necessarily establish whether they can reliably perform a demanding occupation eight hours a day, five days a week.

For disability insurance, a more relevant question may be:

Can the person reliably perform the material duties of their occupation?

That can involve:

concentration + memory + communication + attendance + decision-making + stress tolerance + consistency.

How Long-Term Disability Insurance May Cover Mental Health

Imagine an employee earns:

$8,000 per month.

Their employer’s LTD plan provides:

60% of covered earnings

subject to the policy’s terms.

Potential monthly benefit:

$4,800.

The employee develops a qualifying mental-health condition and satisfies the policy’s definition of disability.

The LTD policy may potentially pay benefits after the applicable:

elimination period.

But there may be another provision buried deeper in the contract:

a mental-health benefit limitation.

That provision can dramatically change how long benefits continue.

The 24-Month Mental Health Limitation

One of the most important provisions to investigate is whether your LTD plan imposes a maximum benefit period for disabilities caused by certain mental-health conditions.

For example, a policy might provide:

General LTD maximum: to age 65

but:

Certain mental-health disabilities: maximum 24 months.

This is only an illustration—actual policies vary.

The Department of Labor’s ERISA Advisory Council has documented the issue of LTD plans limiting the duration of benefits for mental-health conditions while benefits for some other medical conditions may continue until retirement age.

So never assume:

“Benefits to age 65”

means every covered disability will necessarily be payable until age 65.

Why This Limitation Matters

Consider a 40-year-old worker.

Suppose their policy could otherwise provide qualifying LTD benefits until:

age 65.

Potential protection period:

25 years.

But suppose a particular mental-health claim falls under a:

24-month limitation.

The difference is enormous.

That’s why you should examine both:

Maximum Benefit Period

and

Mental Health / Mental-Nervous Limitations.

Mental Health Parity Doesn’t Automatically Apply to LTD

This is an especially important point.

You may have heard of federal mental-health parity requirements and assume mental and physical disabilities must therefore receive identical LTD treatment.

That’s not necessarily the case.

The Department of Labor’s ERISA Advisory Council specifically noted that the Mental Health Parity and Addiction Equity Act (MHPAEA) does not apply to LTD plans.

In other words:

Health insurance mental-health parity ≠ automatic LTD parity.

That distinction can significantly affect income protection.

Health Insurance and Disability Insurance Solve Different Problems

Health Insurance

Helps pay eligible expenses associated with:

Doctors + therapy + prescriptions + hospitalization + other covered treatment.

Disability Insurance

Helps replace part of:

your lost earnings

when you satisfy the policy’s definition of disability.

A health plan may cover treatment for depression while your disability policy separately determines whether the condition prevents you from working.

These are different insurance questions.

What Does an Insurer Need to See?

For a mental-health disability claim, insurers may review documentation relating to:

Diagnosis

Symptoms

Treatment

Functional limitations

Medication

Treatment response

Occupational duties

Work history

Attendance

and other relevant information permitted under the policy and applicable law.

The objective isn’t merely to establish:

“I have anxiety.”

It is generally necessary to establish how the condition affects your ability to perform the work required under the policy.

Medical Documentation Can Be Critical

Mental-health symptoms can sometimes be difficult to measure with a single test.

That makes consistent clinical documentation particularly important.

Depending on the situation, relevant records may include documentation from:

Psychiatrists

Psychologists

Other treating clinicians

Hospitals or treatment programs

and other appropriate medical sources.

Social Security likewise requires a medically determinable physical or mental impairment supported by appropriate medical evidence; symptoms alone do not establish a medically determinable impairment under SSA’s rules.

Private insurers apply their own policy standards, but accurate documentation remains important.

Connect Symptoms to Job Duties

Consider a software engineering manager.

Their job requires:

Managing 15 employees

Reviewing complex technical work

Leading meetings

Making high-impact decisions

Managing deadlines

Maintaining concentration for extended periods.

A statement saying:

“Patient experiences anxiety”

doesn’t explain how work is affected.

Relevant functional information might address limitations involving:

sustained concentration

decision-making

memory

communication

attendance

ability to tolerate workplace demands

ability to maintain consistent productivity.

The documentation should be accurate—not exaggerated.

Consistency Matters

A person might be capable of completing an activity:

occasionally

without being capable of sustaining competitive full-time employment.

For example:

Being able to use a laptop for 30 minutes isn’t necessarily the same as maintaining:

8 hours of complex work every weekday.

Likewise, attending a family dinner doesn’t necessarily demonstrate the capacity to maintain:

40 hours of demanding professional work every week.

Social Security regulations similarly distinguish ordinary activities such as household tasks and hobbies from substantial gainful activity.

What About Depression?

Depression can range from relatively mild symptoms to severe functional impairment.

A diagnosis alone doesn’t establish disability.

But severe symptoms might potentially interfere with:

Concentration

Memory

Energy

Motivation

Decision-making

Attendance

Communication

Ability to complete tasks consistently.

Whether LTD benefits are payable depends on the policy and evidence.

What About Anxiety?

Anxiety also varies greatly in severity.

Someone with anxiety may continue working successfully.

Another person may experience symptoms that substantially interfere with:

meetings + client interactions + travel + concentration + decision-making + attendance.

Again:

diagnosis ≠ automatic disability.

The focus is the functional impact under the applicable policy.

What About PTSD?

PTSD may potentially qualify under disability insurance when the condition satisfies the policy’s requirements.

Symptoms can affect areas such as:

concentration + sleep + emotional regulation + social interaction + ability to tolerate certain environments.

The EEOC recognizes PTSD among mental-health conditions that may constitute disabilities under employment law.

Private disability benefits, however, remain governed by the applicable insurance contract.

What About Bipolar Disorder?

Bipolar disorder can also potentially affect work capacity.

The EEOC identifies bipolar disorder among conditions that can qualify as disabilities under the ADA.

For insurance purposes, the relevant issue remains whether documented functional limitations satisfy the policy’s definition of disability.

Mental Health and Own-Occupation Coverage

Your disability definition matters enormously.

Suppose you’re an attorney whose condition prevents you from reliably:

conducting trials + managing complex litigation + meeting court deadlines + advising clients.

Under an:

Own-Occupation

definition, the policy may focus on whether you’re capable of performing your occupation as defined in the contract.

Under an:

Any-Occupation

definition, the insurer may evaluate whether you’re capable of other qualifying work.

The distinction can substantially affect mental-health disability claims.

Your Definition May Change

Some LTD policies may use one definition during the initial claim period and a different one later.

A simplified example might be:

First 24 months: Own Occupation

then:

After 24 months: Any Occupation.

Now imagine the same policy also contains a mental-health-specific limitation.

You need to understand both provisions.

Search your policy for:

Definition of Disability

Own Occupation

Any Occupation

Mental/Nervous

Mental Illness

Maximum Benefit Period.

Partial Disability May Be Important

Mental-health conditions aren’t necessarily:

Able to work

or

Unable to work.

A worker might be capable of:

20 hours per week

but not:

40 hours.

If their income falls substantially, a policy containing qualifying:

partial disability

or

residual disability

benefits may potentially provide some protection.

Check whether your policy includes these features.

Example: Working Reduced Hours

Before the condition:

40 hours/week

$8,000/month income

After the condition:

20 hours/week

$4,200/month income

Income reduction:

$3,800/month.

Depending on the policy, residual or partial disability provisions could potentially address some of that lost income.

Don’t assume benefits require complete inability to perform any work.

Remote Work Doesn’t Automatically Solve Disability

In 2026, this is increasingly relevant.

An insurer or employer may ask:

“Couldn’t you just work from home?”

Remote work can eliminate commuting and provide flexibility.

But many jobs still require:

Sustained concentration

Deadlines

Meetings

Communication

Decision-making

Productivity

Regular attendance.

A mental-health condition affecting those functions doesn’t automatically disappear because the employee works remotely.

Workplace Accommodation Is Different From Disability Insurance

The ADA may require covered employers to provide reasonable accommodations to qualified employees with disabilities unless doing so would cause undue hardship. The EEOC notes that accommodations can help workers with mental-health conditions perform and retain their jobs.

Possible accommodations depend on the situation.

But this is a separate question from whether a disability insurer must pay benefits.

Think of them as:

ADA → Can the employee continue working with reasonable accommodation?

Disability insurance → Does the employee satisfy the policy’s disability definition?

The two can overlap factually but aren’t the same determination.

What About Social Security Disability?

Social Security recognizes qualifying:

physical or mental impairments.

SSA states that an adult generally must be unable to engage in substantial gainful activity because of a medically determinable physical or mental impairment expected to result in death or lasting—or expected to last—for at least 12 continuous months.

This is a different standard from private disability insurance.

SSDI Rules for 2026

SSA’s 2026 substantial gainful activity amount is:

$1,690 per month for non-blind individuals

and:

$2,830 per month for statutorily blind individuals.

These numbers apply to Social Security’s rules.

They don’t determine whether a private LTD insurer must approve a claim.

Private LTD Approval Doesn’t Guarantee SSDI

Suppose your private insurer approves your mental-health disability claim.

That doesn’t automatically qualify you for SSDI.

Likewise, a Social Security decision doesn’t necessarily determine whether you meet a private policy’s definition.

Different systems apply:

different definitions + different evidence standards + different benefit rules.

Watch for Pre-Existing-Condition Provisions

Mental-health conditions may also interact with a policy’s:

pre-existing-condition provision.

Suppose you receive treatment shortly before becoming covered under a new employer LTD plan.

Depending on the plan, a later claim related to that condition might be affected by the pre-existing-condition language.

Review:

Look-back period

Effective date

Treatment/medication definitions

Exclusion period.

Don’t assume new employment automatically means every prior condition receives unrestricted coverage immediately.

Substance-Use Conditions May Have Separate Rules

Some policies combine mental-health and substance-use conditions under the same benefit limitation.

Others may treat them differently.

Check the exact contract.

Don’t assume that a policy’s rules concerning:

depression

are necessarily identical to those concerning:

substance-use disorders.

Treatment Requirements Matter

Some disability policies require the claimant to remain under:

regular and appropriate care

or use similar terminology.

That means ongoing treatment can be relevant not only medically but contractually.

If you’re making a claim, understand what the policy requires and follow appropriate medical advice.

Don’t Wait Until a Claim to Read the Policy

Before you need disability benefits, obtain your plan documents.

Search for these sections:

Definition of Disability

Mental Illness Limitation

Mental/Nervous Disorders

Substance Use

Maximum Benefit Period

Elimination Period

Own Occupation

Any Occupation

Residual Disability

Pre-Existing Conditions

Exclusions

Those sections provide far more useful information than a benefits page that simply says:

“60% LTD coverage.”

A 2026 Mental Health Coverage Example

Consider Emma, a 39-year-old professional.

Monthly income: $9,000

Employer LTD: 60%

Potential monthly benefit: $5,400

Essential monthly expenses: $6,200

Initial gross gap:

$800/month

before considering taxes, caps or offsets.

Now suppose Emma develops a qualifying mental-health condition.

Her plan approves LTD.

But the claim falls under a:

24-month mental-health benefit limitation.

Her financial problem isn’t simply the:

$800 monthly gap.

She also needs to ask:

“What happens after Month 24 if I’m still unable to work?”

That is why benefit duration matters as much as benefit percentage.

Questions to Ask HR or Your Insurer

Before relying on your disability coverage, ask:

  1. Does the policy cover qualifying mental-health disabilities?
  2. Is there a separate mental-health limitation?
  3. What conditions fall under that limitation?
  4. Is there a 24-month or other maximum?
  5. Are there exceptions to the limitation?
  6. How does the policy define disability?
  7. Is it own-occupation or any-occupation?
  8. Does the definition change later?
  9. Does the policy cover partial disability?
  10. Are residual benefits available?
  11. What medical documentation is required?
  12. Is ongoing treatment required?
  13. What is the elimination period?
  14. Are there pre-existing-condition restrictions?
  15. What exclusions apply?

2026 Mental Health Disability Checklist

Before purchasing or reviewing coverage:

  • Read the complete disability definition.
  • Check mental-health coverage.
  • Look for mental/nervous limitations.
  • Check the maximum benefit period.
  • Determine whether a 24-month limitation applies.
  • Review substance-use provisions separately.
  • Check own-occupation vs. any-occupation.
  • Determine whether the definition changes later.
  • Review partial/residual disability benefits.
  • Check the elimination period.
  • Review pre-existing-condition provisions.
  • Check treatment requirements.
  • Review exclusions.
  • Check monthly benefit limits.
  • Understand other-income offsets.
  • Calculate your household income gap.
  • Keep appropriate medical documentation.
  • Understand your occupational duties.
  • Review employer accommodations separately.
  • Recheck coverage when changing employers.

Frequently Asked Questions

Does disability insurance cover depression?

Potentially. Depression may qualify when it meets the policy’s definition of disability and other contractual requirements. A diagnosis by itself doesn’t guarantee benefits.

Can anxiety qualify for long-term disability?

Potentially, if its documented functional effects are sufficiently severe to satisfy the applicable policy definition. Coverage and limitations vary.

Can PTSD qualify for disability benefits?

Potentially. PTSD can significantly affect occupational functioning, and the EEOC recognizes PTSD as a condition that can qualify as a disability under the ADA. Private disability-insurance eligibility is determined separately under the policy.

Does bipolar disorder qualify for disability insurance?

It potentially can, depending on severity, functional limitations, supporting evidence and policy terms. The EEOC identifies bipolar disorder among mental-health conditions that can qualify as disabilities under employment law.

Are mental-health LTD benefits limited to two years?

Some LTD plans impose duration limits on benefits for certain mental-health conditions, but this isn’t universal. The Department of Labor’s ERISA Advisory Council has specifically studied these disparities.

Does mental-health parity law apply to LTD insurance?

The Department of Labor’s ERISA Advisory Council states that MHPAEA does not apply to LTD plans.

Does Social Security recognize mental-health disabilities?

Yes. SSA’s disability definition covers qualifying medically determinable physical or mental impairments.

What’s the SSDI substantial gainful activity amount in 2026?

SSA lists 2026 SGA at $1,690 per month for non-blind individuals and $2,830 for statutorily blind individuals.

Final Thoughts

Mental-health disability coverage can be an important part of income protection in 2026.

But the most important question isn’t simply:

“Does my disability insurance cover mental health?”

You need to go deeper:

Which conditions are covered?

How does the policy define disability?

How long can benefits continue?

Does a mental-health-specific limitation apply?

What happens if I can work only part-time?

What evidence is required?

A policy promising benefits until age 65 can provide very different protection if certain mental-health claims are subject to a shorter maximum period.

Before relying on your employer or individual LTD coverage, read the actual contract—particularly its:

definition of disability + mental-health limitations + benefit period + residual benefits + exclusions + pre-existing-condition provisions.

For income protection, those details can matter far more than the headline benefit percentage.

Mental Health & “Invisible” Disabilities: The 2026 Frontier of Income Protection

Small business owner reviewing cyber liability insurance after a cybersecurity incident.

Quick Takeaway

Not every disability is visible.

A worker may look physically healthy while dealing with a condition that seriously affects their ability to:

concentrate, communicate, remember, make decisions, maintain attendance, manage stress or consistently perform their occupation.

Mental-health conditions are one important example. Other conditions may also create significant functional limitations without an obvious outward sign.

For disability insurance, however, the key question generally isn’t:

“Can other people see your disability?”

It’s:

“Does your condition meet the policy’s definition of disability, and can its impact on your ability to work be adequately documented?”

This distinction matters because private disability insurance, employer LTD plans and Social Security Disability Insurance can use different eligibility standards.

And there’s another issue workers need to understand in 2026:

Mental-health parity rules for health insurance don’t automatically mean equal treatment under long-term disability insurance.

A U.S. Department of Labor ERISA Advisory Council report specifically noted that the federal Mental Health Parity and Addiction Equity Act (MHPAEA) applies to certain health coverage but does not apply to LTD plans.

That makes reading your actual disability policy particularly important.

What Is an “Invisible” Disability?

“Invisible disability” isn’t one single insurance-policy category.

It’s a broad term often used for health conditions whose effects may not be immediately apparent to another person.

Someone could:

walk normally

drive

have a conversation

post on social media

and still experience functional limitations that make sustained employment difficult or impossible.

Depending on the individual and severity, examples can involve conditions affecting:

  • Mental functioning
  • Cognitive abilities
  • Energy and stamina
  • Concentration
  • Memory
  • Pain
  • Neurological functioning
  • Sensory processing
  • Emotional regulation

The important insurance point is that a diagnosis alone generally isn’t the whole story.

Functional impairment matters.

Mental Health Can Affect Work Capacity

Consider an employee whose job requires:

complex decision-making + constant client interaction + tight deadlines + managing employees + frequent presentations.

A serious mental-health condition might affect:

concentration

memory

decision-making

stress tolerance

attendance

social interaction

or

ability to complete tasks consistently.

A person doesn’t necessarily need a visible physical impairment for their ability to perform occupational duties to be substantially affected.

Disability Insurance Is About Function, Not Appearance

Imagine two employees.

Employee A

Has an obvious physical injury but can still perform the essential duties of a remote desk-based occupation.

Employee B

Has no visible physical impairment but experiences severe cognitive and psychological symptoms that prevent reliable completion of essential job duties.

From a disability-insurance perspective, outward appearance alone doesn’t determine the result.

The insurer evaluates the claim under the:

policy definition + medical evidence + occupational evidence + functional limitations.

That’s why the term:

“invisible disability”

shouldn’t be confused with:

“unprovable disability.”

Diagnosis Doesn’t Automatically Equal Disability

Suppose someone has been diagnosed with depression.

That fact alone doesn’t necessarily establish entitlement to LTD benefits.

Likewise, having anxiety, PTSD or another diagnosed condition doesn’t automatically mean a person cannot work.

The relevant question is usually closer to:

How does this person’s condition affect their ability to perform the occupational duties required under the policy’s definition of disability?

Two people with the same diagnosis can have dramatically different functional abilities.

Medical Evidence Matters

Documentation can become especially important when symptoms aren’t externally visible.

Depending on the claim and policy, evidence might include:

Treatment records

Physician or clinician assessments

Medication history

Hospital or treatment history

Functional assessments

Documented symptoms

Work limitations

Treatment response

and other appropriate clinical evidence.

Social Security similarly requires a medically determinable physical or mental impairment. SSA explains that medical evidence must establish the impairment; symptoms alone aren’t sufficient to establish a medically determinable impairment.

Private insurers use their own contractual standards, but the broader lesson remains useful:

documentation matters.

Your Occupational Duties Matter Too

Medical records establish only part of the picture.

The next question is:

What does your job actually require?

Suppose you’re a senior financial analyst.

Your work requires:

8–10 hours of sustained concentration

complex financial modeling

rapid decision-making

accuracy

deadlines

and

client presentations.

Now suppose a condition severely affects:

concentration + memory + processing speed + stress tolerance.

Those limitations need to be considered in the context of your occupational requirements.

The issue isn’t simply:

“Can this person use a computer?”

It’s:

“Can this person reliably perform the material duties required by the occupation under the policy?”

Consistency Can Matter as Much as Capability

This distinction is particularly important with some invisible conditions.

Someone may be capable of performing a task:

once.

But employment generally requires performing duties:

day after day

week after week

with reasonable:

reliability + productivity + attendance + accuracy.

Being capable of concentrating for:

30 minutes

doesn’t necessarily mean someone can maintain concentration for an eight-hour workday.

Similarly, having one good day doesn’t necessarily establish the ability to sustain full-time employment.

Mental Health and Long-Term Disability Insurance

Many employer LTD policies can cover qualifying disabilities associated with mental-health conditions.

However, the terms can differ from those applicable to some physical conditions.

One particularly important provision to look for is a:

mental/nervous limitation

or similar condition-specific benefit limitation.

Some LTD plans may limit the period during which benefits are payable for certain mental-health or substance-use-related disabilities.

The 24-Month Limitation

A commonly discussed LTD provision limits benefits for certain mental-health disabilities to:

24 months.

But don’t assume every policy contains this limit.

And don’t assume every mental-health-related claim automatically falls under it.

The U.S. Department of Labor’s ERISA Advisory Council studied mental-health disparities in LTD benefits and specifically examined limitations imposed on benefits for mental-health and substance-use-disorder conditions.

The exact treatment depends on the contract and applicable law.

That’s why workers should search their policy for terms such as:

Mental Illness

Mental/Nervous Disorder

Mental Health

Substance Use

Limited Pay Period

Maximum Benefit Period

Why a 24-Month Limit Can Be Significant

Imagine your LTD policy generally provides benefits:

to age 65.

You’re 42.

That sounds like potentially decades of protection.

But suppose the policy limits qualifying benefits for a particular category of mental-health disability to:

24 months.

That’s a dramatically different financial outcome.

Potential maximum under the general provision:

Years of benefits

versus

potential condition-specific limitation:

2 years.

This is why reading only the headline:

“LTD benefits to age 65”

can be misleading.

You need to read the limitations section too.

Mental Health Parity Doesn’t Automatically Fix This

This is an especially important distinction for 2026.

The Mental Health Parity and Addiction Equity Act provides federal protections relating to mental-health and substance-use-disorder benefits in applicable health plans.

The Department of Labor explains that MHPAEA requires covered health plans to treat mental-health and substance-use-disorder benefits comparably to medical/surgical benefits in areas such as certain financial requirements and treatment limitations.

But:

health insurance isn’t disability income insurance.

The Department of Labor’s ERISA Advisory Council specifically noted that MHPAEA does not apply to LTD plans.

That’s a critical distinction.

Health Coverage vs. Income Protection

Think of the difference this way.

Health Insurance

Helps pay eligible costs associated with:

therapy + doctors + hospitalization + prescriptions + treatment.

Disability Insurance

Helps replace part of:

lost earnings

when you satisfy the policy’s definition of disability.

Mental-health parity protections applicable to health coverage therefore shouldn’t automatically be assumed to govern your disability-income benefit.

Other Invisible Conditions

Invisible disability isn’t limited to mental health.

Depending on the individual and severity, conditions affecting work capacity might involve:

chronic pain

neurological disorders

autoimmune conditions

migraine disorders

post-viral conditions

cognitive impairment

and other health problems.

This article isn’t suggesting that having any particular condition automatically qualifies someone for disability benefits.

Eligibility depends on:

severity + functional limitations + medical evidence + occupational duties + policy definition.

The Challenge of Fluctuating Conditions

Some conditions aren’t equally severe every day.

A person may experience:

good days

and

bad days.

That creates an important disability question:

Can the person reliably maintain the schedule and productivity required by their occupation?

For example:

Monday — works normally.

Tuesday — severe symptoms.

Wednesday — partial recovery.

Thursday — unable to work.

Friday — works several hours.

The question isn’t simply whether the person can ever work.

It may be whether they can perform their occupational duties with sufficient:

consistency and reliability.

Remote Work Complicates the Question

The expansion of remote and hybrid work has created another layer.

An insurer might ask:

Could this employee perform the occupation from home?

But remote work doesn’t eliminate every occupational requirement.

A remote professional may still need to:

concentrate for hours

attend meetings

manage deadlines

communicate with clients

make complex decisions

maintain productivity

and

work consistently.

Removing the commute doesn’t necessarily remove the disability.

Accommodation and Disability Insurance Are Different Questions

An employer may be able to provide workplace accommodations in certain situations.

But:

employment accommodation

and

disability insurance eligibility

are separate legal and contractual questions.

A modified schedule or remote-work arrangement could potentially help someone remain employed.

That’s often valuable.

But whether the person qualifies for disability benefits depends on the applicable insurance plan and facts.

Partial Disability Can Be Important

Invisible conditions don’t always eliminate work capacity entirely.

Suppose you previously worked:

40 hours/week

but can now sustainably work only:

20 hours/week.

Your income falls significantly.

Some disability policies offer:

partial disability

or

residual disability

benefits.

These provisions can be particularly important when a condition reduces your ability to work rather than completely eliminating it.

Example: Reduced Work Capacity

Before disability:

Income: $8,000/month
Hours: 40/week

After disability:

Income: $4,500/month
Hours: 22/week

Income reduction:

$3,500/month.

Depending on the policy, a qualifying residual-disability provision could potentially provide benefits based partly on reduced income or work capacity.

Check the actual formula.

Own-Occupation Coverage Can Matter

Suppose you’re a trial attorney.

Your condition severely affects:

rapid information processing + memory + sustained concentration + public speaking under pressure.

You can still perform some simpler administrative work.

An:

own-occupation

definition could evaluate whether you can perform your insured occupation.

An:

any-occupation

definition may eventually evaluate your capacity for other qualifying work.

For invisible disabilities, this distinction can be extremely important.

Employer Plans May Change Definitions

Your employer LTD plan might use:

Own occupation initially

and later transition to:

Any occupation.

That means someone could receive benefits for a period and later face a more demanding eligibility standard.

Review:

Definition of Disability

and determine whether it changes after:

12 months, 24 months or another period.

Don’t assume approval means benefits will continue unchanged until retirement.

Social Security Recognizes Mental Impairments

Social Security’s disability rules expressly recognize both:

physical and mental impairments.

SSA defines disability as inability to engage in substantial gainful activity because of a medically determinable physical or mental impairment, or combination of impairments, expected to result in death or lasting—or expected to last—at least 12 continuous months.

So a disability does not need to be visibly physical to potentially satisfy Social Security’s medical framework.

But SSDI Has a Strict Standard

Recognition of mental impairment doesn’t mean automatic eligibility.

SSA evaluates whether a medically determinable impairment prevents substantial gainful activity under its rules.

For 2026, SSA lists the general monthly SGA amount as:

$1,690 for non-blind individuals

and:

$2,830 for individuals considered blind under SSA rules.

SSA also requires sufficient work history for SSDI eligibility.

Private LTD and SSDI Are Not the Same

This distinction is crucial.

Your employer LTD plan might say:

Own Occupation

while Social Security uses its own federal disability standard.

SSA itself notes that its disability criteria can differ from criteria used by private disability programs.

Therefore:

Approved for LTD ≠ automatically approved for SSDI.

And:

Denied SSDI ≠ automatically denied under every private LTD policy.

Each system applies its own rules.

Documentation Should Connect Symptoms to Work

Consider the difference between these descriptions.

Weak description:

“Employee has difficulty concentrating.”

Versus a more function-focused record showing that the condition affects:

ability to maintain attention

ability to complete complex tasks

accuracy

attendance

ability to meet deadlines

interaction with colleagues or clients

decision-making

and

sustainable work hours.

The point isn’t to exaggerate symptoms.

It’s to accurately document their occupational consequences.

Treatment History Can Matter

Depending on the policy and claim, insurers may review whether you’re receiving:

appropriate treatment

and complying with applicable:

care recommendations.

Policies may contain provisions requiring:

regular care

or similar treatment requirements.

If you are filing a claim, read these provisions carefully and maintain accurate treatment records.

Medication Side Effects Can Affect Function

Sometimes the underlying condition isn’t the only factor affecting work capacity.

Treatment can potentially cause side effects affecting:

alertness + concentration + memory + stamina.

If clinically relevant, these effects should be accurately discussed with your treating healthcare professional.

Again, disability claims are about:

documented functional capacity.

Don’t Stop Treatment Because a Claim Was Approved

LTD approval isn’t necessarily permanent.

Insurers may periodically review whether the claimant continues to satisfy the policy’s disability definition.

Social Security also conducts continuing disability reviews in appropriate cases to determine whether disability continues.

Follow appropriate medical advice regardless of the insurance process.

Social Media Can Create Context Problems

Imagine telling your insurer:

“I cannot leave home.”

Then posting public photos showing extensive travel.

That could raise obvious questions.

But context matters.

A photograph doesn’t necessarily establish someone’s ability to sustain:

40 hours of competitive employment every week.

Still, disability claimants should be accurate and consistent about their limitations.

Never exaggerate a claim.

Describe what you:

can and cannot reliably do.

Invisible Doesn’t Mean “All or Nothing”

Someone may be able to:

shop for groceries

while being unable to:

manage an eight-hour executive workday.

Someone may be able to:

attend a family event

but be unable to:

maintain five consecutive days of high-pressure employment.

Daily activities and occupational capacity aren’t necessarily identical.

The important issue is accurate context.

Income Protection Should Be Reviewed Before a Crisis

The worst time to discover a:

24-month mental-health limitation

is after you’ve already become disabled.

Before choosing coverage, review:

Maximum Benefit Period

then separately:

Condition-Specific Limitations.

Don’t assume they’re identical.

Questions to Ask Your Employer

If you receive disability insurance through work, ask HR or the plan administrator:

  1. Does our LTD plan cover qualifying mental-health disabilities?
  2. Is there a separate mental-health benefit limit?
  3. If so, how long is it?
  4. Which conditions fall under that limitation?
  5. Are there exceptions?
  6. How does the plan define disability?
  7. Does the definition change later?
  8. Are partial or residual disabilities covered?
  9. What medical evidence is required?
  10. Is regular treatment required?
  11. What’s the elimination period?
  12. What’s the maximum monthly benefit?
  13. What other-income offsets apply?
  14. How do appeals work?
  15. Where can I obtain the complete plan documents?

What to Look for in an Individual Policy

If you’re considering individual disability insurance, don’t compare only:

Premium + benefit amount.

Review:

Mental-health limitations

Substance-use limitations

Own-occupation definition

Residual disability

Elimination period

Benefit duration

Exclusions

Pre-existing-condition provisions

Renewability

Recovery benefits

Future increase options.

Policy wording matters far more than a brochure headline.

A Practical 2026 Income-Protection Example

Consider a 38-year-old professional earning:

$9,000/month.

Employer LTD benefit:

60%

Potential monthly benefit:

$5,400

Essential household expenses:

$6,500/month.

Initial monthly gap:

$1,100

before considering taxes, caps and offsets.

Now suppose the plan also contains a condition-specific:

24-month limitation

applicable to the person’s claim.

The worker faces two separate financial questions:

Can my household survive the monthly income reduction?

and:

What happens if benefits stop after two years but I’m still unable to work?

That’s why condition-specific limitations can be as important as the replacement percentage.

Building a Stronger Safety Net

A broader income-protection strategy might combine:

Emergency fund

Employer STD

Employer LTD

Individual disability coverage, when appropriate

household secondary income

applicable government programs.

No single layer necessarily solves every disability scenario.

2026 Invisible Disability Insurance Checklist

Before purchasing or reviewing coverage:

  • Read the definition of disability.
  • Check own-occupation vs. any-occupation.
  • Determine whether the definition changes.
  • Review mental-health coverage.
  • Check for condition-specific benefit limits.
  • Review substance-use provisions separately.
  • Check the maximum benefit period.
  • Review residual/partial disability.
  • Check the elimination period.
  • Review treatment requirements.
  • Check pre-existing-condition provisions.
  • Review exclusions.
  • Check monthly benefit caps.
  • Review other-income offsets.
  • Understand the claims process.
  • Understand appeal rights.
  • Keep accurate medical records.
  • Understand your occupational duties.
  • Calculate your household income gap.
  • Maintain appropriate emergency savings.

Frequently Asked Questions

Can mental-health conditions qualify for disability insurance?

Potentially, yes. Eligibility depends on the policy, severity of the condition, functional limitations, medical evidence and the applicable definition of disability.

What is an invisible disability?

It’s a broad term commonly used for a disability or health condition whose effects may not be immediately apparent to other people. It’s not one universal disability-insurance classification.

Does a mental-health diagnosis automatically qualify for LTD?

No. A diagnosis alone doesn’t necessarily establish that you meet the policy’s definition of disability. Functional limitations and supporting evidence are important.

Can LTD benefits for mental-health disabilities be limited to 24 months?

Some LTD plans contain condition-specific mental-health limitations, including 24-month limits. The Department of Labor’s ERISA Advisory Council has specifically examined these limitations in LTD plans.

Does federal mental-health parity law require LTD policies to treat mental and physical disabilities identically?

Not generally under MHPAEA. The Department of Labor’s ERISA Advisory Council notes that MHPAEA applies to health coverage but doesn’t apply to LTD plans.

Can Social Security recognize a mental-health disability?

Yes. SSA’s definition includes medically determinable physical or mental impairments, provided all eligibility requirements are satisfied.

Does SSDI use the same disability definition as private LTD?

No. SSA specifically notes that its criteria may differ from those used by private disability programs.

Can someone qualify for disability even if they can perform some daily activities?

Potentially. The relevant question is whether the person satisfies the applicable disability definition. SSA regulations, for example, distinguish activities such as household tasks and hobbies from substantial gainful activity.

Final Thoughts

The future of disability insurance isn’t only about visible injuries.

For the 2026 workforce, income protection increasingly needs to account for conditions affecting:

mental functioning + cognition + stamina + consistency + ability to perform complex work.

But the fundamental insurance principle remains unchanged:

Diagnosis isn’t the same as disability.

A successful disability claim generally depends on demonstrating how a covered condition affects the ability to work under the policy’s specific definition.

Workers should pay particular attention to:

mental-health limitations → maximum benefit periods → own-occupation vs. any-occupation → residual disability → treatment requirements → medical documentation.

And don’t assume health-insurance mental-health parity rules automatically extend to disability-income coverage.

For an invisible disability, the most important evidence isn’t whether other people can see the condition.

It’s whether the medical and occupational evidence accurately demonstrates:

what the condition prevents you from reliably doing—and how that affects your ability to earn an income.

Is Group Disability Enough? Why Your Employer’s Plan Might Leave a 40% Income Gap

American employee comparing employer group disability benefits with household income and monthly expenses.

Quick Takeaway

Your employer tells you:

“You have long-term disability insurance.”

That sounds reassuring.

But there’s an important question:

How much of your income would actually be replaced if you couldn’t work?

Many disability plans are designed to replace only a portion of pre-disability earnings rather than your entire paycheck. A plan replacing 60% of earnings mathematically leaves a 40% gross-income gap before considering monthly benefit caps, taxes, offsets and other policy provisions.

For example:

Monthly salary: $8,000
60% disability benefit: $4,800
Gross income difference: $3,200/month

And your actual spendable benefit could be lower in some circumstances.

The IRS states that disability benefits attributable to employer-paid premiums generally must be included in taxable income. If an employee paid the entire premium with after-tax dollars, qualifying disability benefits generally aren’t included in income.

So the real question isn’t simply:

“Do I have disability insurance through work?”

It’s:

“How much income would my plan actually replace—and for how long?”

What Is Group Disability Insurance?

Group disability insurance is disability coverage provided to eligible employees through an employer or another group arrangement.

Employers may offer:

Short-Term Disability (STD)

and/or

Long-Term Disability (LTD).

Depending on the plan, the employer may:

  • Pay the entire premium
  • Pay part of the premium
  • Require employees to pay
  • Offer additional voluntary coverage

Group disability insurance can be a valuable employee benefit.

The problem arises when workers assume:

Group coverage = my entire income is protected.

It usually doesn’t work that way.

Where Does the “40% Income Gap” Come From?

Consider a simplified example.

You earn:

$100,000 per year.

That’s approximately:

$8,333 per month gross.

Suppose your LTD plan replaces:

60% of covered earnings.

The theoretical benefit is:

$5,000 per month.

That leaves approximately:

$3,333 of gross monthly earnings unreplaced.

Over one year, that’s roughly:

$40,000

of gross income difference.

The 40% figure isn’t a universal rule. Some plans replace more or less than 60%, and definitions of covered earnings vary.

But it illustrates why a percentage that sounds substantial may still create a significant financial gap.

Your Expenses Don’t Automatically Fall by 40%

This is the practical problem.

Suppose disability reduces your gross income from:

$8,000 → $4,800 per month.

Does your mortgage fall by 40%?

No.

Does your rent?

No.

Your:

Mortgage + utilities + groceries + insurance + debt + childcare + transportation

may continue.

Your expenses could even increase if disability creates additional healthcare or assistance costs.

That’s why disability coverage should be evaluated against your household budget, not simply your salary.

The Monthly Benefit Cap Can Make the Gap Even Larger

The replacement percentage isn’t necessarily the most important number.

Your policy may also impose a:

maximum monthly benefit.

Suppose you earn:

$15,000/month.

Your plan says:

60% income replacement.

You might expect:

$9,000/month.

But suppose the plan has a:

$6,000 monthly maximum.

Your benefit could be capped at:

$6,000.

Now you’re not replacing 60% of your $15,000 salary.

You’re replacing only:

40%.

Your gross monthly income gap becomes:

$9,000.

This issue can be especially important for:

Executives + physicians + attorneys + technology professionals + salespeople + other high earners.

Bonuses and Commissions May Not Be Fully Covered

Suppose your compensation is:

Base salary: $100,000
Annual bonus: $30,000
Commission: $20,000

Total compensation:

$150,000.

Does your disability plan calculate benefits using:

$150,000

or only:

$100,000?

Don’t assume.

Plans may define covered earnings differently.

Review how the policy treats:

  • Bonuses
  • Commissions
  • Overtime
  • Incentive compensation
  • Stock-based compensation
  • Other variable earnings

For workers with substantial variable compensation, this can create another income-protection gap.

Taxes Can Reduce What You Actually Receive

Here’s another issue many employees overlook.

Suppose your employer pays the LTD premium.

If you become disabled, you may assume:

$5,000 monthly benefit = $5,000 available for expenses.

Not necessarily.

According to the IRS, if your employer paid for the accident or health insurance plan providing disability benefits, amounts received through that employer-paid coverage generally must be reported as income.

If both you and your employer paid premiums, generally only the portion attributable to the employer’s contributions is included in income when the employee’s share was paid after tax.

If you paid the entire cost with after-tax dollars, qualifying disability benefits generally aren’t included in income.

Tax circumstances vary, so check your specific plan and consult a qualified tax professional when necessary.

A 60% Benefit Can Feel Like Much Less

Consider:

Pre-disability gross income: $10,000/month

Group LTD benefit: 60%

Potential gross LTD benefit:

$6,000/month.

Your apparent gap:

$4,000/month.

But if the benefit is taxable because of how premiums were paid, your spendable benefit may be lower.

That’s why you should determine:

Who pays the premium?

Is it paid pre-tax or after-tax?

How would benefits be treated for federal income-tax purposes?

These questions matter before disability occurs.

Group LTD May Have a Waiting Period

Even good coverage doesn’t necessarily begin immediately.

Long-term disability commonly includes an:

elimination period

or:

waiting period.

During this period, LTD benefits generally aren’t payable.

Suppose your plan has:

90-day elimination period.

Your income protection may need to look something like:

PTO/Sick Leave

Emergency Savings

Short-Term Disability

Long-Term Disability

The pieces need to fit together.

Check Whether STD and LTD Actually Connect

Suppose:

Short-term disability ends: Day 60

but:

Long-term disability elimination period: 90 days.

Potential gap:

30 days.

Where will the money come from?

Perhaps:

Emergency savings.

But you need to know that before a claim occurs.

Don’t assume employer benefits automatically coordinate perfectly.

Definition of Disability Can Matter More Than the Percentage

Imagine your plan promises:

60% income replacement.

That’s useful only if you satisfy its:

definition of disability.

Some plans initially evaluate whether you can perform your:

own occupation

while others may apply or eventually transition to an:

any-occupation

standard.

This can substantially affect eligibility.

For example, a surgeon might lose the ability to perform surgery but remain capable of teaching or administrative work.

Whether LTD continues can depend on the contract.

Your Definition Could Change Later

Some employer LTD policies use one disability definition for an initial period and a different standard afterward.

For example, a policy might effectively operate as:

Initial period: Own occupation

then:

Later period: Any occupation.

If that happens, you may qualify initially but later face a different eligibility test.

Search your plan documents for:

Definition of Disability

Own Occupation

Regular Occupation

Any Occupation

Gainful Occupation.

Group Coverage Is Connected to Your Employment

Another important question:

What happens when you leave your employer?

Employer-sponsored disability benefits are generally tied to eligibility under that particular plan.

If you:

resign + get laid off + change companies + become self-employed,

you shouldn’t automatically assume the same disability protection follows you.

Check the plan’s:

termination + conversion + portability

provisions.

Individual disability insurance, by contrast, is generally purchased directly by the insured and isn’t dependent on remaining with one employer, subject to policy terms.

Changing Jobs Can Create a Coverage Reset

Imagine you’ve had excellent LTD coverage for ten years.

You change employers for a:

25% salary increase.

Great.

But your new employer’s disability plan might have:

lower benefits + smaller monthly cap + different waiting period + different disability definition.

Salary shouldn’t be the only benefit you compare when evaluating a new job.

For workers with substantial financial obligations, disability benefits can have meaningful economic value.

Group Coverage Can Be Excellent—Without Being Complete

None of this means employer disability insurance is bad.

Quite the opposite.

Employer-sponsored LTD can provide valuable protection at little or no direct cost to an employee.

The problem is assuming:

“Employer LTD exists, therefore I don’t need to evaluate disability risk.”

A better approach is:

Employer coverage first → identify gaps → decide whether those gaps matter → consider supplemental options if appropriate.

What Is Supplemental Disability Insurance?

Supplemental disability insurance is additional coverage intended to complement existing protection.

Depending on availability, workers may obtain additional coverage through:

Employer voluntary benefits

or

an individually purchased disability policy.

The goal isn’t necessarily:

replace 100% of salary.

Instead, it may be to reduce a meaningful income gap created by:

replacement percentage + monthly cap + taxes + uncovered compensation.

Example: Employer LTD Plus Individual Coverage

Consider Sarah.

Annual salary: $150,000

Her employer LTD plan provides:

60% of covered salary

subject to:

$6,000/month maximum.

Her theoretical 60% benefit would be:

$7,500/month.

But the cap reduces it to:

$6,000.

Her gross monthly salary is:

$12,500.

So her gross income gap is:

$6,500/month.

She might evaluate individual disability coverage to help address part of that gap, subject to underwriting and insurers’ participation limits.

Insurers Won’t Necessarily Let You Insure 100% of Income

You generally shouldn’t expect to stack policies until disability benefits equal or exceed your normal income.

Disability insurers commonly limit total available benefits relative to earnings.

Why?

Insurance is intended to protect against financial loss—not create a financial incentive to remain disabled.

If purchasing supplemental coverage, disclose existing:

Group disability + individual coverage + other applicable disability benefits

accurately during underwriting.

Emergency Savings Still Matter

Even excellent disability coverage doesn’t eliminate the need for accessible savings.

Why?

Because you may still face:

Waiting periods + claims processing + uncovered expenses + income gaps + deductibles + healthcare costs.

Suppose your essential expenses are:

$6,000/month.

Your LTD benefit is:

$4,500/month.

Monthly shortfall:

$1,500.

A:

$30,000 emergency fund

could provide considerable flexibility for handling that gap.

Disability insurance and emergency savings solve different parts of the same problem.

How Much of Your Income Do You Actually Need?

Rather than automatically targeting:

100% replacement,

calculate your essential expenses.

For example:

ExpenseMonthly Amount
Mortgage$2,300
Food$900
Utilities$400
Transportation$600
Insurance$600
Childcare$900
Debt$500
Other essentials$500
Total$6,700

Suppose your estimated spendable disability income is:

$4,800/month.

Your estimated monthly gap becomes:

$1,900.

That’s the number worth planning around.

Don’t Forget Health Insurance

If disability prevents you from working, also investigate what happens to your:

employer health insurance.

Disability income coverage and health coverage are separate issues.

Ask HR:

Does health coverage continue during disability?

For how long?

What portion of premiums would I pay?

A disability could reduce income while simultaneously changing healthcare expenses.

Social Security Disability Isn’t a Simple Gap Filler

Some workers assume:

Employer LTD + SSDI = I’ll be fine.

But Social Security Disability Insurance has separate and relatively strict eligibility rules.

It shouldn’t be treated as guaranteed supplemental income.

Additionally, employer LTD plans may contain provisions offsetting benefits by certain other disability income.

Always check your policy’s:

Other Income Benefits

or:

Offsets

section.

Other Benefits Can Reduce Group LTD Payments

Depending on the plan, benefits from other sources may affect LTD payments.

Potential examples can include certain:

Social Security disability benefits

workers’ compensation

other disability benefits.

The exact rules vary by plan.

So don’t automatically calculate:

Employer LTD + SSDI + workers’ comp = total income.

Your policy may coordinate these amounts.

Pre-Existing Condition Provisions Matter

Starting a new job and receiving LTD coverage doesn’t necessarily mean every condition is immediately covered without limitations.

Some plans contain:

pre-existing-condition provisions.

Review:

look-back period + treatment rules + exclusion period + effective date.

This can be especially important after changing employers.

Mental Health Limitations Can Affect Benefit Duration

Some LTD plans impose specific benefit-duration limits on certain categories of disability.

A plan might advertise:

Benefits to age 65

while containing shorter limitations for specified conditions.

Review sections dealing with:

mental/nervous conditions

substance-use disorders

and other condition-specific limitations.

Don’t assume the maximum benefit period applies identically to every disability.

Group Plans Can Have Claims and Appeal Procedures

Many private-sector employer disability plans are governed by ERISA, although there are exceptions.

The U.S. Department of Labor says ERISA-covered disability plans must comply with minimum procedural requirements for benefit claims, including rules concerning claims processing, benefit determinations and appeals.

If your employer plan is ERISA-covered, understanding the claims and appeals process can be important if a benefit is denied or terminated.

Get Your Summary Plan Description

Don’t evaluate your protection from the HR enrollment screen alone.

Ask for the:

Summary Plan Description (SPD)

and relevant:

certificate of coverage or policy documents.

Then find:

Benefit Percentage

Maximum Monthly Benefit

Definition of Earnings

Elimination Period

Definition of Disability

Maximum Benefit Period

Other Income Benefits

Exclusions

Limitations

Termination of Coverage

Those sections tell you what you’re actually buying.

Run a Disability Paycheck Stress Test

Here’s a useful exercise.

Write down:

1. Gross monthly salary

Example:

$10,000

2. Employer LTD percentage

Example:

60%

Potential benefit:

$6,000

3. Monthly maximum

Example:

$5,000

Now your benefit is capped at:

$5,000.

4. Determine potential tax treatment

Find out who pays the premiums and whether contributions are made pre-tax or after-tax.

5. Essential monthly expenses

Example:

$6,500

Now you can see the problem:

Potential benefit: $5,000 before considering applicable taxes

versus

Essential expenses: $6,500.

That’s at least a:

$1,500 monthly gap

before considering tax consequences or other policy provisions.

Who Is Most Likely to Need Supplemental Coverage?

Supplemental protection may deserve closer consideration if you:

  • Have a high income subject to a low group-plan cap
  • Receive substantial bonuses or commissions
  • Are the household’s primary earner
  • Have children or other dependents
  • Have a large mortgage
  • Carry significant fixed expenses
  • Have limited emergency savings
  • Work in a highly specialized occupation
  • Expect significant future income growth
  • Plan to become self-employed
  • Frequently change employers

This doesn’t mean everyone in these situations automatically needs an individual policy.

It means the gap deserves closer analysis.

When Might Employer Coverage Be Enough?

Employer coverage may be adequate for some workers.

For example, you may have:

Low fixed expenses

Substantial emergency savings

Strong spouse/partner income

Generous group LTD

Manageable monthly benefit cap

Favorable plan provisions.

Insurance decisions should reflect your actual financial exposure.

There is no universal rule saying:

Everyone needs supplemental disability insurance.

15 Questions to Ask HR in 2026

Before assuming your employer coverage is enough, ask:

  1. What percentage of earnings does LTD replace?
  2. What counts as covered earnings?
  3. Are bonuses included?
  4. Are commissions included?
  5. What’s the maximum monthly benefit?
  6. Who pays the premium?
  7. Are employee premiums paid pre-tax or after-tax?
  8. What’s the elimination period?
  9. How long can benefits continue?
  10. How does the plan define disability?
  11. Does the definition change later?
  12. What other-income offsets apply?
  13. Are there condition-specific benefit limitations?
  14. What happens when I leave the company?
  15. Where can I obtain the full SPD and policy documents?

Group vs. Individual Disability Insurance

FeatureEmployer Group LTDIndividual Disability
Obtained throughEmployerIndividual purchase
CostOften employer-subsidizedIndividually priced
PortabilityMay end with employmentGenerally tied to insured, subject to policy
UnderwritingDepends on planUsually individual underwriting
Benefit capPlan-specificBased on underwriting and income
Disability definitionPlan-specificPolicy-specific
CustomizationOften limitedMay offer more options
Tax treatmentDepends on premium fundingDepends on premium funding and tax rules

Neither is automatically superior.

They can serve complementary roles.

2026 Group Disability Checklist

Before deciding your employer plan is sufficient:

  • Find your benefit percentage.
  • Check the monthly maximum.
  • Determine what counts as earnings.
  • Check treatment of bonuses.
  • Check treatment of commissions.
  • Determine who pays premiums.
  • Understand potential tax treatment.
  • Review the elimination period.
  • Check STD-to-LTD coordination.
  • Read the definition of disability.
  • Check whether the definition changes.
  • Review partial/residual benefits.
  • Review benefit duration.
  • Check other-income offsets.
  • Review exclusions.
  • Review condition-specific limitations.
  • Check pre-existing-condition provisions.
  • Determine what happens after leaving your employer.
  • Calculate essential monthly expenses.
  • Calculate your actual potential income gap.
  • Consider whether supplemental coverage is appropriate.

Frequently Asked Questions

Does employer disability insurance replace my entire salary?

Usually, you should not assume that it does. Employer plans commonly replace only a specified percentage of covered earnings and may impose a maximum monthly benefit. Check your specific plan documents.

Why does a 60% disability plan leave a 40% gap?

Mathematically, if a plan replaces 60% of covered gross earnings, 40% isn’t replaced by that benefit before considering caps, taxes, offsets and other provisions. The actual gap can therefore be smaller or larger depending on your circumstances.

Can the income gap be more than 40%?

Yes. A monthly benefit cap, exclusion of bonuses or commissions, taxes on benefits, and other-income provisions can alter the amount you actually receive.

Are employer-paid disability benefits taxable?

The IRS says disability benefits attributable to an accident or health insurance plan paid for by your employer generally must be included in income. If both employer and employee paid premiums, taxation depends on how contributions were made.

Are benefits tax-free if I pay the disability premium myself?

The IRS says that if you pay the entire cost of the accident or health insurance plan yourself, benefits received for personal injury or sickness generally aren’t included in income. The treatment depends on how premiums were paid, including whether they were paid with after-tax dollars.

Does group LTD follow me when I change jobs?

Don’t assume it does. Check your plan’s eligibility, termination, portability and conversion provisions before leaving an employer.

Can I buy disability insurance in addition to my employer plan?

Potentially. Individual or supplemental disability coverage may be available, subject to insurer underwriting, income requirements and limits on total coverage.

Should high earners pay particular attention to group LTD?

Yes. A monthly maximum can cause the effective replacement percentage to fall substantially below the advertised percentage for higher-income employees.

Where can I find the details of my employer disability plan?

Ask your employer or plan administrator for the Summary Plan Description and relevant insurance certificate or plan documents. For ERISA-covered disability plans, federal claims-procedure standards apply.

Final Thoughts

Employer disability insurance can be one of the most valuable benefits in your compensation package.

But:

having disability insurance

isn’t the same as:

having enough disability insurance.

A plan replacing 60% of covered income automatically creates a 40% gross difference before considering anything else.

Then you may need to account for:

Monthly benefit caps + taxes + uncovered bonuses + commissions + waiting periods + offsets + exclusions + benefit-duration limits.

For some employees, employer LTD may provide adequate protection.

For others—particularly higher earners or households dependent on one income—the actual gap could be substantial.

So don’t stop at:

“My company provides LTD.”

Find your plan documents and calculate:

Normal income → covered earnings → replacement percentage → monthly cap → potential tax treatment → essential expenses = your real disability-income gap.

That’s the number that matters.

Disability Insurance 101: A Guide for the 2026 American Workforce

American worker reviewing disability insurance and income protection as part of a 2026 financial plan.

Quick Takeaway

Most workers insure their:

car + home + health.

But there’s another asset that can be even more important:

your ability to earn a paycheck.

Disability insurance is designed to replace part of your income when a qualifying illness or injury prevents you from working.

It generally comes in two major forms:

Short-Term Disability (STD) — designed for shorter qualifying periods away from work.

Long-Term Disability (LTD) — designed for disabilities that continue much longer.

The NAIC says short-term disability typically replaces a portion of salary for roughly three to six months, while long-term coverage generally begins later and may potentially continue for years or until retirement age, depending on the policy.

For American workers in 2026, understanding disability insurance isn’t just an insurance decision.

It’s part of protecting your:

income + household expenses + savings + long-term financial plan.

What Is Disability Insurance?

Disability income insurance is designed to provide income when a covered disability prevents you from working according to your policy’s requirements.

Think about what happens when your paycheck stops.

Your:

  • Mortgage or rent
  • Groceries
  • Utilities
  • Car payment
  • Insurance premiums
  • Student loans
  • Credit-card payments
  • Childcare expenses

don’t necessarily stop with it.

Health insurance can help with qualifying medical expenses.

But health insurance generally isn’t designed to replace your lost paycheck.

That’s the financial problem disability income insurance attempts to address.

Why Your Income May Be Your Most Valuable Asset

Imagine you’re 35 years old and earn:

$75,000 per year.

If you work another 30 years at exactly the same salary, that’s:

$2.25 million

in gross future earnings.

And that doesn’t account for:

raises + promotions + bonuses + career growth.

Now imagine losing the ability to earn that income because of a prolonged disability.

For many working Americans, their future earning ability represents one of their largest financial assets.

Disability insurance is essentially designed to protect part of that earning power.

Disability Doesn’t Necessarily Mean a Catastrophic Accident

When people hear “disability,” they may imagine:

a major car accident

or

a serious workplace injury.

But qualifying disabilities can also result from illnesses.

Coverage varies considerably between policies. The NAIC notes that some disability policies cover both illnesses and injuries, while some may limit coverage to disability resulting from accidents.

That’s why you should never assume:

“Disability insurance covers anything that stops me working.”

The contract determines what qualifies.

The Two Main Types of Disability Insurance

Most workers should understand two categories:

Short-Term Disability Insurance

Short-term disability is designed to replace part of your income during a temporary qualifying disability.

The NAIC says STD typically replaces a portion of salary for approximately:

three to six months.

Actual benefit periods vary by plan.

Long-Term Disability Insurance

Long-term disability is designed for potentially much longer income interruptions.

Depending on the policy, benefits might continue for:

several years

or potentially:

until a specified retirement age.

The NAIC notes that LTD can potentially last years or until retirement age depending on the coverage selected.

STD vs. LTD

FeatureShort-Term DisabilityLong-Term Disability
PurposeTemporary income protectionExtended income protection
Benefit durationUsually monthsPotentially years
Waiting periodGenerally shorterGenerally longer
Income replacementPortion of incomePortion of income
Primary riskTemporary inability to workProlonged loss of earning ability
Role in financial planShort-term bridgeLong-term income protection

Exact terms depend on the policy.

How Much Income Does Disability Insurance Replace?

Here’s one of the biggest misconceptions:

Disability insurance usually doesn’t replace your entire paycheck.

The NAIC says a typical disability policy benefit is approximately:

60% of pre-disability earned income, although actual coverage varies and other sources of disability support can affect benefits.

Suppose you earn:

$6,000 per month.

A hypothetical 60% benefit would be:

$3,600 per month.

That leaves a:

$2,400 difference

before considering taxes, benefit limits, offsets and other household income.

That’s why understanding the percentage alone isn’t enough.

Watch the Maximum Monthly Benefit

Imagine your employer says:

“Our LTD plan replaces 60% of salary.”

You earn:

$15,000 per month.

You might expect:

$9,000 per month.

But suppose the policy has a:

$6,000 maximum monthly benefit.

Your actual maximum could be significantly lower.

Higher earners should therefore check both:

replacement percentage + monthly benefit cap.

What Is an Elimination Period?

One of the most important disability-insurance terms is:

Elimination Period.

It’s also commonly called the:

Waiting Period.

This is the period you generally must satisfy after becoming disabled before benefits become payable.

The NAIC notes that longer waiting periods generally produce lower premiums.

Think of it as a:

time deductible.

Instead of paying the first $1,000 of a claim, you are responsible for financially surviving the initial period without disability benefit payments.

Example: 90-Day Waiting Period

Suppose you have:

LTD benefit: $4,000/month
Elimination period: 90 days

You become unable to work on:

January 1.

Your policy generally won’t provide LTD benefits during the elimination period.

How will you pay your expenses?

Possible resources include:

Emergency savings

Paid sick leave

PTO

Short-term disability

Spouse/partner income.

This is why disability insurance and emergency savings should work together.

The First Payment May Come Later

Don’t assume:

90-day waiting period = check arrives on Day 91.

Payment schedules vary.

The NAIC notes that it can be common to wait up to 30 days after the waiting period before receiving the first benefit payment.

That makes maintaining adequate accessible savings especially important.

What Does “Disabled” Actually Mean?

This may be the single most important question in your policy.

Not:

“How much does it pay?”

But:

“What must happen for the insurer to consider me disabled?”

The definition varies between policies.

Two important concepts are:

Own-Occupation

and

Any-Occupation.

Own-Occupation Disability

An own-occupation definition generally focuses on whether your disability prevents you from performing your occupation as defined by the policy.

Consider a surgeon who develops a severe hand condition.

The surgeon can no longer:

perform surgery.

But they may still be capable of:

teaching + consulting + administrative work.

An own-occupation definition can potentially focus on the inability to perform the duties of the insured occupation.

Any-Occupation Disability

An any-occupation definition generally applies a broader work-capacity standard under the terms of the policy.

The question may become whether you’re capable of performing other gainful employment for which you’re qualified.

The NAIC specifically warns consumers that definitions differ: some policies may pay when you cannot perform your own occupational duties, while others may require that you be unable to perform other gainful employment for which you’re qualified.

That’s a major difference.

Some LTD Policies Can Change Definitions

Don’t assume the definition that applies at the beginning of your disability applies forever.

Some LTD plans may use an own-occupation-style definition initially and later move to an any-occupation-style standard.

Therefore, search your policy for:

Definition of Disability

and check whether that definition changes after a specified period.

What Is Partial Disability?

Not every disability prevents all work.

Suppose you normally work:

40 hours per week.

A medical condition allows you to work only:

20 hours.

Your income drops significantly.

Some policies may provide benefits for qualifying:

partial disability

or

residual disability.

The NAIC says residual benefits can help fill an income gap when a disability reduces your ability to perform your job and causes reduced income.

This feature can be extremely valuable.

How Long Can Disability Benefits Last?

Benefit periods vary substantially.

Depending on the policy, LTD benefits might potentially last:

1 year

2 years

5 years

10 years

or

to a specified retirement age.

The NAIC notes that choosing a shorter benefit period can lower premiums, but benefits could also expire while you’re still disabled.

That creates an important trade-off.

Employer Disability Insurance

Before shopping for individual coverage, check what you already have through work.

Ask HR whether your benefits include:

Short-Term Disability

and/or

Long-Term Disability.

But don’t stop when HR says:

“Yes, you have LTD.”

Get the actual plan information.

For many private-sector employer plans subject to ERISA, federal rules establish standards for disability-benefit claims and appeals. The Department of Labor explains that ERISA includes requirements governing claims processing and rights when a claim is denied.

10 Questions to Ask HR

Find out:

  1. What percentage of my income is covered?
  2. What’s the maximum monthly benefit?
  3. How long is the waiting period?
  4. How long can benefits continue?
  5. How does the plan define disability?
  6. Does the definition change later?
  7. Does it cover partial disability?
  8. Who pays the premium?
  9. What benefit offsets apply?
  10. What happens to my coverage if I leave the company?

These questions can tell you far more than:

“My employer provides disability insurance.”

Employer Coverage vs. Individual Coverage

Employer disability insurance can be an excellent benefit.

However, workers should understand its limitations.

An employer policy may have:

Benefit caps

Plan-specific disability definitions

Offsets

Coverage limitations

and potentially:

loss of coverage after leaving the employer.

Individual disability insurance can provide another source of protection, but eligibility, underwriting, pricing and features vary by insurer.

Some workers use:

Employer LTD + individual disability insurance

to address gaps in their overall income protection.

What About Self-Employed Workers?

Self-employed Americans face a different problem.

There may be no HR department providing:

STD + LTD.

If you’re a:

freelancer

consultant

contractor

professional

or

business owner,

ask yourself:

“What happens if I cannot work for 18 months?”

Your income could fall while your household expenses continue.

And your business may still have expenses.

Personal Disability Insurance Isn’t Business Insurance

Suppose you own a consulting firm.

You become disabled.

You personally need money for:

mortgage + groceries + household expenses.

But your company still needs money for:

rent + payroll + software + utilities + loan payments.

Those are different financial problems.

Personal disability income insurance generally focuses on replacing part of personal income.

Business owners may need separate strategies for ongoing business obligations.

Disability Insurance vs. Workers’ Compensation

These products shouldn’t be confused.

Workers’ compensation generally addresses qualifying:

work-related injuries and illnesses

under applicable state law.

Disability insurance can potentially provide income protection for covered disabilities occurring outside work as well, depending on the contract.

You shouldn’t automatically assume:

“My employer has workers’ comp, so I’m covered if I can’t work.”

They serve different purposes.

Disability Insurance vs. Health Insurance

Health insurance helps with eligible healthcare expenses.

Disability insurance helps address:

lost income.

Imagine an illness keeps you out of work for eight months.

Your health insurance might help pay qualifying:

doctor + hospital + treatment

costs.

But who pays:

your mortgage?

That’s the type of financial risk disability income coverage is intended to address.

What About Social Security Disability Insurance?

Social Security Disability Insurance—SSDI—is a federal program.

But it should not be treated as equivalent to private disability insurance.

SSA uses a strict disability definition.

For adults, the impairment generally must prevent substantial gainful activity and be expected to result in death or last continuously for at least 12 months.

SSA also states that Social Security doesn’t provide benefits for partial or short-term disability.

SSDI in 2026

SSA’s 2026 rules state that workers generally must have sufficient covered work history in addition to meeting the disability requirements.

For 2026, SSA lists the general substantial gainful activity amount as:

$1,690 per month

or:

$2,830 per month for individuals considered blind under SSA rules.

These amounts are specific to Social Security’s rules and shouldn’t be confused with limits in a private disability policy.

Don’t Assume SSDI Will Replace Private LTD

SSA itself notes that its disability criteria can differ from those used by private and other government disability programs.

You might therefore:

qualify under one system

but

not qualify under another.

Likewise, a private policy may provide partial or shorter-term protection that Social Security doesn’t.

How Disability Insurance Fits Into Your Financial Plan

Think of income protection in layers.

Layer 1: Emergency Savings

Handles immediate expenses.

Layer 2: Paid Leave

Provides temporary income when available.

Layer 3: Short-Term Disability

Can bridge a qualifying temporary income interruption.

Layer 4: Long-Term Disability

Protects against potentially prolonged income loss.

Layer 5: Social Security Disability

May provide federal benefits when strict eligibility requirements are satisfied.

The strongest plan doesn’t necessarily rely on only one layer.

How Much Disability Insurance Do You Need?

Start with your actual household budget.

Suppose your monthly expenses are:

ExpenseMonthly Cost
Mortgage/Rent$2,000
Food$800
Utilities$350
Transportation$600
Insurance$500
Debt$500
Childcare$700
Other essentials$550
Total$6,000

Now compare that with your expected disability benefit.

Suppose:

Potential monthly benefit = $4,200

Your initial estimated gap is:

$1,800/month.

Now ask whether your:

savings + partner’s income + other resources

can comfortably handle that gap.

That’s more useful than simply asking:

“Is 60% coverage enough?”

Watch for Benefit Offsets

Some disability policies coordinate benefits with other sources of disability income.

That means the amount you receive from another program could potentially affect the amount payable under your policy.

Check for provisions involving:

Other Income Benefits

Offsets

Social Security

Workers’ Compensation

and other disability benefits.

Never assume you can simply add every benefit together.

Taxes Can Affect Your Real Benefit

A policy might advertise:

$5,000 monthly benefit.

But your usable amount can depend partly on the tax treatment applicable to your particular coverage.

Tax treatment can depend on factors including how premiums were paid.

For employer coverage, ask:

Who pays the premium?

Then discuss the potential tax implications with a qualified tax professional.

Exclusions Matter

Don’t evaluate disability insurance only by what it covers.

Also ask:

What doesn’t it cover?

Depending on the policy, exclusions or limitations may apply to certain:

conditions + circumstances + activities + pre-existing conditions.

Read these sections carefully.

A cheap policy with significant limitations may not provide the protection you expected.

Mental Health Benefit Limitations

Some disability policies may contain separate provisions affecting benefits for specified mental-health or substance-related conditions.

Don’t assume:

“Benefits payable to age 65”

necessarily means every qualifying disability receives benefits for that entire period.

Review condition-specific limitations.

Inflation Can Matter During a Long Disability

Imagine receiving:

$4,500 per month

today.

Now imagine receiving the same:

$4,500

15 years from now.

Its purchasing power could be substantially lower.

Some individual disability policies offer inflation-related features such as a:

Cost-of-Living Adjustment (COLA).

These features can be particularly relevant for younger workers purchasing long-duration coverage.

Future Income Growth Matters Too

Suppose you’re 30 and earn:

$70,000.

At 40, you’re earning:

$140,000.

Coverage purchased a decade earlier may no longer adequately protect your income.

Some individual policies offer options that may allow qualifying policyholders to increase coverage later under specified conditions.

Workers expecting substantial career growth should review these provisions.

When Should You Review Your Disability Coverage?

Don’t treat disability insurance as:

buy once → forget forever.

Review your coverage when you:

  • Change jobs
  • Get married
  • Have children
  • Buy a home
  • Become self-employed
  • Receive a major promotion
  • Experience substantial income growth
  • Take on significant debt
  • Lose employer benefits
  • Build substantial savings

Your income-protection needs can change dramatically over time.

A Simple Disability Stress Test

Ask yourself:

“If my paycheck stopped tomorrow, how long could I maintain my household?”

Scenario 1: 30 Days

Could your savings handle it?

Scenario 2: 6 Months

Would paid leave or STD help?

Scenario 3: 2 Years

Would LTD protect enough income?

Scenario 4: 10 Years

Would your policy still be paying?

Would inflation become a problem?

Would the definition of disability have changed?

This simple exercise can reveal gaps that aren’t obvious from reading your benefit percentage alone.

2026 Disability Insurance Checklist

Before purchasing or reviewing disability coverage:

  • Calculate essential monthly expenses.
  • Determine your emergency-fund coverage.
  • Check employer STD coverage.
  • Check employer LTD coverage.
  • Confirm the income-replacement percentage.
  • Check the maximum monthly benefit.
  • Review the elimination period.
  • Determine when the first payment would arrive.
  • Review the benefit period.
  • Read the definition of disability.
  • Compare own-occupation and any-occupation provisions.
  • Determine whether the definition changes later.
  • Review partial/residual disability benefits.
  • Check exclusions.
  • Review pre-existing-condition provisions.
  • Check condition-specific benefit limitations.
  • Review benefit offsets.
  • Understand potential tax treatment.
  • Consider inflation protection.
  • Consider future income growth.
  • Check portability of employer coverage.
  • Reassess your coverage after major life changes.

Frequently Asked Questions

What does disability insurance do?

Disability insurance generally replaces part of your income when a qualifying illness or injury prevents you from working according to the policy’s definition of disability.

How much of my salary does disability insurance replace?

The amount varies. The NAIC says a typical disability policy benefit is approximately 60% of pre-disability earned income, although policy limits, offsets and other provisions can change the actual benefit.

What’s the difference between STD and LTD?

Short-term disability generally protects against shorter qualifying income interruptions, while long-term disability addresses extended disabilities. The NAIC says STD commonly replaces part of income for approximately three to six months, while LTD can potentially continue for years.

What is an elimination period?

It’s the waiting period you generally must satisfy after disability begins before policy benefits become payable. Longer waiting periods generally result in lower premiums.

Is disability insurance the same as workers’ compensation?

No. Workers’ compensation primarily addresses qualifying work-related injuries and illnesses. Disability income insurance is a separate form of income protection.

Is disability insurance the same as SSDI?

No. SSDI is a federal Social Security program with its own eligibility rules. Private disability insurance operates according to the insurance contract.

Does Social Security cover short-term disability?

No. SSA states that Social Security pays only for total disability under its rules, not partial or short-term disability.

How long must a disability last for SSDI?

Under Social Security’s definition, the impairment generally must have lasted or be expected to last continuously for at least 12 months, or be expected to result in death.

Do I need disability insurance if my employer already provides it?

Employer coverage may provide valuable protection, but review its benefit percentage, monthly cap, waiting period, disability definition, benefit duration, offsets and portability before deciding whether it fully meets your needs.

Is own-occupation disability coverage better?

It can provide a broader occupational definition of disability, particularly for specialized professionals, but coverage and terminology vary. The NAIC notes that some policies focus on inability to perform your occupation while others require inability to perform other gainful employment for which you’re qualified.

Final Thoughts

For the 2026 American workforce, disability insurance should be viewed as:

income protection—not medical insurance.

The fundamental question is simple:

What happens financially if you can no longer earn your normal paycheck?

A strong disability strategy may combine:

Emergency savings + paid leave + short-term disability + long-term disability + applicable government benefits.

But don’t evaluate a disability policy based only on its premium.

Pay close attention to:

Benefit amount → monthly maximum → elimination period → definition of disability → own-occupation vs. any-occupation → benefit duration → exclusions → residual benefits → offsets.

The most important policy isn’t necessarily the one promising the largest monthly payment.

It’s the one whose terms appropriately protect the income risk you’re actually trying to insure.

Own-Occupation vs. Any-Occupation: The One Clause That Determines Your Payout

Professional comparing own-occupation and any-occupation disability insurance coverage.

Quick Takeaway

When comparing disability insurance, it’s easy to focus on:

Premium + monthly benefit + waiting period + benefit duration.

But one provision can be even more important:

the policy’s definition of disability.

Two policies might both promise a $5,000 monthly benefit, yet reach very different claim decisions because one uses an own-occupation definition while another uses an any-occupation definition.

In simplified terms:

Own-occupation: Are you unable to perform the material duties of your occupation?

Any-occupation: Are you unable to perform an occupation you could reasonably be expected to perform based on factors specified by the policy?

NAIC materials describe own occupation in relation to the occupation performed before disability, while an any-occupation definition can consider other work a person could reasonably perform based on factors such as age, education, experience, and physical and mental capacity.

The exact language varies by policy, so the contract—not the marketing label—controls.

Why This Clause Matters So Much

Imagine you’re a surgeon.

A medical condition causes severe loss of fine motor control in your hands.

You can:

talk + walk + teach + perform administrative work.

But you can no longer safely perform surgery.

Are you disabled?

The answer could depend heavily on your policy’s definition.

Under some own-occupation coverage, inability to perform the material duties of your surgical occupation could potentially satisfy the definition.

Under an any-occupation standard, the insurer may also examine whether you’re capable of performing other work that satisfies the policy’s requirements.

That’s an enormous difference.

What Is Own-Occupation Disability Insurance?

Own-occupation coverage focuses primarily on whether your disability prevents you from performing the important duties of your occupation, as that term is defined in the contract.

An NAIC model-language document describes being totally disabled from one’s own occupation as being unable to perform the material and substantial duties of the insured’s specific occupation with reasonable continuity in the usual and customary way.

This can be particularly important for people whose income depends on highly specialized abilities.

Think:

  • Surgeons
  • Dentists
  • Physicians
  • Attorneys
  • Engineers
  • Executives
  • Pilots
  • Skilled tradespeople
  • Specialized consultants
  • Certain technology professionals

However, simply seeing the words “own occupation” on a brochure isn’t enough.

You need to read exactly how your policy defines it.

What Is Any-Occupation Disability Insurance?

Any-occupation coverage generally applies a broader work-capacity test.

Instead of asking only:

“Can you still perform your previous occupation?”

the insurer may ask:

“Can you perform another occupation that meets the policy’s definition?”

NAIC model language describes any occupation by reference to work the insured could reasonably be expected to perform full-time considering factors such as age, education, experience, physical and mental capacity, and station in life.

Again, actual policy wording varies.

The Difference in One Example

Consider Alex.

Occupation: Orthopedic surgeon
Pre-disability income: $300,000
Condition: Permanent hand impairment

Alex cannot safely operate.

But Alex could potentially:

teach medicine + consult + perform administrative work.

Under an own-occupation policy, the key question may center on whether Alex can continue performing the material duties of being an orthopedic surgeon.

Under an any-occupation provision, the insurer may consider whether Alex can perform another occupation meeting the contract’s criteria.

Same person.

Same medical condition.

Same loss of surgical ability.

Potentially very different insurance outcomes.

It’s Not Simply “Can You Work?”

This distinction is critical.

Disability insurance doesn’t necessarily ask:

“Are you physically capable of doing anything?”

The actual question is determined by the contract.

An any-occupation provision may consider factors such as:

Education + training + experience + functional capacity + earnings potential, depending on its wording.

So being capable of performing a completely unrelated minimum-wage job doesn’t automatically tell you whether you satisfy every private any-occupation policy.

Read the definition carefully.

Occupation vs. Job Title

Suppose your title is:

Vice President.

That tells an insurer relatively little.

Your actual duties might include:

  • Managing 100 employees
  • Traveling internationally
  • Negotiating contracts
  • Presenting to clients
  • Analyzing financial information
  • Working 60 hours per week

Another company’s vice president could perform completely different duties.

When evaluating an own-occupation claim, the nature of your actual occupational duties can therefore be extremely important.

Specialists Should Pay Particular Attention

Consider two physicians.

Doctor A: General practitioner

Doctor B: Neurosurgeon

Both are technically:

physicians.

But their occupational duties differ significantly.

That’s why specialists should determine whether the policy recognizes their specialty when defining occupation.

NAIC model language specifically includes the insured’s specialty when describing own occupation.

For professionals with highly specialized duties, this distinction can be especially valuable.

True Own-Occupation Coverage

You may encounter policies marketed using terms such as:

True Own-Occupation

The general idea is that you may qualify as disabled from your insured occupation even if you’re capable of working in another occupation, subject to the exact contract.

For example:

A surgeon can no longer perform surgery.

The surgeon qualifies under the policy’s disability definition.

Later, the surgeon teaches at a medical school.

Depending on the policy, benefits may potentially continue even though the insured is earning income elsewhere.

But don’t rely on the phrase “true own occupation” alone.

It’s marketing terminology.

Read the contractual definition.

Modified Own-Occupation

Another variation is sometimes described as:

Modified Own-Occupation.

A policy might consider you disabled when you cannot perform your own occupation and aren’t working in another occupation, depending on the specific language.

That creates an important difference.

Under one contract:

Unable to perform own occupation + working elsewhere = benefits may continue.

Under another:

Working elsewhere = benefits reduced or terminated.

Again:

policy wording controls.

Transitional Own-Occupation

Some policies may provide own-occupation treatment while adjusting benefits based on income earned in another occupation.

This may sometimes be called:

transitional own-occupation

or similar terminology.

For example:

You previously earned:

$15,000/month.

After disability, you can no longer perform your former occupation but earn:

$7,000/month

in another role.

Your disability benefit could potentially be affected by that new income depending on the contract.

Some Policies Change Definitions

This is one of the biggest traps.

A long-term disability policy might effectively operate like:

First 24 months → Own-Occupation

then:

After 24 months → Any-Occupation

The exact period varies.

That means receiving benefits today doesn’t necessarily guarantee you’ll continue receiving them under the same disability standard several years later.

When the definition changes, your claim may be reassessed.

The 24-Month Example

Suppose you’re an engineer earning:

$120,000 per year.

A neurological condition prevents you from performing your engineering duties.

Your policy pays:

$6,000/month.

For the first two years, the policy evaluates whether you can perform your own occupation.

You qualify.

Then the contract changes to an any-occupation definition.

The insurer now evaluates whether you can perform other work meeting the policy’s criteria.

If it determines that you can, benefits could potentially end even though:

you still cannot return to engineering.

This is why the disability definition deserves attention before buying coverage—not only after filing a claim.

Don’t Assume Employer LTD Means Own-Occupation Forever

Employer-provided long-term disability can be valuable.

But you need the actual plan terms.

If your employer offers LTD, obtain the:

Summary Plan Description (SPD) and relevant insurance certificate or policy materials.

The U.S. Department of Labor explains that the SPD describes how an ERISA-covered plan operates and what benefits it provides.

Look specifically for headings such as:

Definition of Disability

Total Disability

Own Occupation

Any Occupation

Regular Occupation

Gainful Occupation

Those few paragraphs may be among the most important parts of your LTD plan.

Example: Dentist

Consider a dentist who develops severe hand tremors.

The dentist can no longer safely perform:

fillings + extractions + dental procedures.

But the person remains capable of:

teaching + consulting + administrative work.

An own-occupation definition may potentially focus on the lost ability to practice dentistry.

An any-occupation definition may evaluate the person’s capacity for other qualifying employment.

For someone whose livelihood depends on precise physical skills, this difference can be substantial.

Example: Airline Pilot

Now consider a commercial airline pilot who develops a condition preventing the pilot from satisfying the occupational requirements needed to fly.

The pilot might still be capable of:

training + aviation consulting + administrative work.

Again, the question isn’t merely:

“Can this person work?”

It’s:

“What does this disability policy require before benefits are payable?”

Example: Software Developer

This issue isn’t limited to medical professionals.

Suppose a software developer develops a neurological condition causing severe concentration and cognitive-processing difficulties.

The person can still perform some basic tasks but cannot reliably:

write complex code + debug systems + manage production deployments.

Whether this constitutes disability depends on the policy’s definition and the person’s functional limitations.

Own-occupation coverage can therefore matter even for desk-based professions.

Your Income Can Matter Too

Some any-occupation provisions don’t simply look for:

any possible job.

They may define a suitable or gainful occupation using an earnings threshold.

For example, the contract might consider whether you’re capable of earning a specified percentage of your previous income.

The percentage varies by policy.

This can materially affect claim eligibility.

Search your policy for terms such as:

Gainful Occupation

Reasonable Occupation

Earnings Threshold

Indexed Earnings

Residual Disability Adds Another Layer

Disability isn’t always:

100% able to work

versus

100% unable to work.

Suppose you can continue your occupation but only:

20 hours per week instead of 40.

Your income falls by:

50%.

Some policies provide residual or partial disability benefits for qualifying reductions in work capacity and income.

This can be particularly important for conditions that reduce rather than completely eliminate your ability to work.

Recovery Benefits May Matter

Suppose you return to your occupation.

You’re technically working again.

But your income remains significantly below its pre-disability level while you rebuild your practice or workload.

Some policies may include recovery-related benefits under specified circumstances.

Again, these features vary.

When comparing policies, don’t look only at:

total disability.

Review partial, residual and recovery provisions too.

Mental Health and Any-Occupation Definitions

Disability can result from physical or mental conditions.

But some disability policies impose special limitations on benefits associated with certain mental-health or substance-related disabilities.

For example, some policies may limit benefits for specified conditions to a particular duration.

This is separate from the:

own-occupation vs. any-occupation

question.

A policy could have favorable own-occupation language but still contain another provision limiting benefits for certain conditions.

Read the policy as a whole.

Pre-Existing Conditions Can Also Affect Coverage

A strong own-occupation definition doesn’t override every other policy provision.

Your claim could still be affected by:

  • Pre-existing-condition limitations
  • Exclusions
  • Waiting periods
  • Benefit maximums
  • Benefit-duration limits
  • Other-income offsets
  • Claims requirements

Disability insurance needs to be evaluated as a complete contract.

Social Security Uses a Different Standard

Don’t confuse private own-occupation disability insurance with Social Security Disability Insurance.

Social Security uses its own federal disability rules.

SSA says it pays only for total disability—not partial or short-term disability—and generally requires that you cannot do your previous work or adjust to other work because of your medical condition.

SSA considers factors including:

medical condition + age + education + work experience + transferable skills

when evaluating whether someone can adjust to other work.

Therefore:

Private own-occupation coverage ≠ Social Security disability.

Being Approved for One Doesn’t Automatically Mean Approval for Another

Imagine your own-occupation insurer approves your claim because you can no longer perform surgery.

That doesn’t automatically mean Social Security will find you disabled.

SSA may proceed to determine whether you can adjust to other work.

Likewise, decisions made under one disability program don’t automatically dictate another program’s claim decision.

Different programs can use different definitions.

Why Higher-Income Professionals Often Examine Own-Occupation Coverage

Suppose you’ve spent:

12 years training

for a highly specialized profession.

Your income depends heavily on:

specific physical abilities

or

specialized cognitive skills.

Being able to perform some other occupation doesn’t necessarily replace your former earning power.

That’s why own-occupation coverage can be particularly relevant to professionals whose:

occupation + specialized ability + income

are closely connected.

But Own-Occupation Isn’t Automatically Better for Everyone

Broader protection can cost more.

Someone with:

substantial savings + multiple income sources + flexible occupational skills

may evaluate the trade-off differently from a specialist whose entire earning capacity depends on one specific ability.

The goal isn’t necessarily to purchase the broadest possible policy.

It’s to understand:

what risk you’re transferring to the insurer.

Premium vs. Definition

Imagine:

Policy A: $130/month
Policy B: $180/month

Policy A looks cheaper.

But suppose Policy A eventually uses an any-occupation definition while Policy B provides a stronger own-occupation definition under its terms.

The additional:

$50/month

isn’t simply buying “more insurance.”

It may be buying a materially different definition of when the insurer considers you disabled.

Compare:

contract against contract

rather than:

premium against premium.

The Definition Can Be Worth More Than a Larger Benefit

Consider:

Policy A

Benefit: $7,000/month
Definition: Restrictive any-occupation

Policy B

Benefit: $6,000/month
Definition: Stronger own-occupation

Which is better?

You can’t answer from the monthly benefit alone.

A theoretical:

$7,000 benefit

doesn’t help if you don’t satisfy the policy’s definition of disability.

The first question should therefore be:

“Under what circumstances will this policy consider me disabled?”

Then evaluate the benefit.

Document Your Occupational Duties

If you’re buying own-occupation coverage, understand exactly what you do.

Consider documenting:

  • Job responsibilities
  • Physical duties
  • Cognitive duties
  • Work hours
  • Travel
  • Client responsibilities
  • Procedures performed
  • Percentage of time spent on major duties
  • Specialized skills
  • Income sources

For specialists, the distinction between different duties can become important during a claim.

Your Occupation Can Change

Suppose you’re a surgeon at age 40.

At age 52, you move almost entirely into:

hospital administration.

Your actual occupation immediately before disability may therefore be different from the occupation you had when you originally bought the policy.

How the policy determines your occupation matters.

Check whether it focuses on:

occupation at time of disability

and how it treats changes in duties.

Business Owners Need Extra Attention

A business owner may perform multiple roles:

CEO + salesperson + consultant + administrator.

If the owner becomes disabled, which occupation applies?

The answer depends on the policy and facts.

Business owners should make sure their occupational description accurately reflects what they actually do.

Don’t simply write:

“Business owner.”

Describe the material duties.

How Insurers May Evaluate a Claim

During a disability claim, the insurer may review information such as:

  • Medical records
  • Physician statements
  • Job descriptions
  • Occupational duties
  • Income records
  • Work history
  • Functional limitations
  • Treatment records

For an own-occupation claim, accurately establishing the relationship between:

medical limitations

and

occupational duties

can be particularly important.

“My Doctor Says I’m Disabled” May Not Be Enough

Your physician’s opinion can be important evidence.

But disability insurance is a contractual benefit.

The insurer evaluates whether your condition satisfies:

the policy’s definition of disability.

The question isn’t simply:

“Does the doctor call me disabled?”

It’s whether medical and occupational evidence demonstrates that you meet the contractual standard.

Questions to Ask Before Buying LTD

Ask your insurer, broker or benefits administrator:

  1. How does the policy define disability?
  2. Is it own-occupation or any-occupation?
  3. How is “occupation” defined?
  4. Is my specialty recognized?
  5. Does the definition change after a certain period?
  6. If so, when?
  7. Can I work in another occupation and still receive benefits?
  8. Does income from another occupation reduce benefits?
  9. What does “gainful occupation” mean?
  10. Is there an earnings threshold?
  11. Are residual disability benefits included?
  12. Is partial disability covered?
  13. Are recovery benefits available?
  14. How are self-employed duties evaluated?
  15. What exclusions or benefit limitations apply?

The Clause to Find in Your Policy

Open your disability policy.

Search for:

DEFINITION OF DISABILITY

Then read every word.

Don’t stop when you see:

Own Occupation.

Continue reading.

Look for wording indicating:

for the first 24 months

or

after benefits have been payable for…

That language could signal that the definition changes later.

Also search for:

Any Occupation

Gainful Occupation

Regular Occupation

Material and Substantial Duties

Residual Disability

Partial Disability

These sections can tell you far more than the policy’s marketing page.

Employer Coverage: Get the Actual Documents

If your disability insurance comes through work, ask your employer or plan administrator for the plan documents.

The Department of Labor says the SPD explains plan benefits and how the plan operates, and participants can request it from the plan administrator.

Don’t rely exclusively on a one-page benefits enrollment summary.

A statement such as:

“60% LTD coverage”

doesn’t tell you the definition of disability.

Own-Occupation vs. Any-Occupation Comparison

FeatureOwn-OccupationAny-Occupation
Main questionCan you perform your occupation?Can you perform another qualifying occupation?
Specialized dutiesParticularly importantMay become less central
Other workMay still permit benefits under some policiesAbility to perform other work can affect eligibility
Claim standardGenerally broaderGenerally more restrictive
CostMay be higherMay be lower
Best fitOften attractive to specialistsMay suit people seeking lower-cost protection
Policy wordingCriticalCritical

These are generalizations. Actual policies can differ significantly.

A Simple Decision Framework

Consider three questions.

1. Is my income dependent on specialized abilities?

If yes, own-occupation protection deserves particular attention.

2. Could I realistically earn similar income in another occupation?

If no, a restrictive any-occupation definition may create more financial exposure.

3. Can I afford the stronger coverage?

Insurance must fit your budget.

You need enough protection to matter without making your overall financial plan unsustainable.

2026 Policy Review Checklist

Before purchasing or renewing disability insurance:

  • Find the definition of disability.
  • Identify own-occupation vs. any-occupation wording.
  • Determine whether the definition changes later.
  • Check when any transition occurs.
  • Determine how your occupation is defined.
  • Confirm whether your specialty is recognized.
  • Check whether you can work elsewhere.
  • Review earnings limitations.
  • Review residual disability.
  • Review partial disability.
  • Check recovery benefits.
  • Review the elimination period.
  • Review benefit duration.
  • Check monthly benefit limits.
  • Review exclusions.
  • Review pre-existing-condition provisions.
  • Check mental-health limitations.
  • Review other-income offsets.
  • Keep your occupational description accurate.
  • Reassess coverage after major career changes.

Frequently Asked Questions

What is own-occupation disability insurance?

Generally, it evaluates whether a covered disability prevents you from performing the material duties of your own occupation, subject to the specific policy wording. NAIC model language describes own occupation by reference to the actual occupation performed before disability, including specialty.

What is any-occupation disability insurance?

It generally evaluates whether you’re unable to perform other qualifying work as defined by the policy. Factors may include education, experience and physical or mental capacity.

Is own-occupation coverage better?

It generally provides a broader occupational definition of disability, but whether it’s appropriate depends on your occupation, finances, available policy options and premium.

Can I work another job while receiving own-occupation benefits?

Some policies permit this under specified circumstances; others may reduce or terminate benefits. Read the exact definition and provisions concerning other employment and income.

Can an LTD policy change from own-occupation to any-occupation?

Some policies do. This is why you should check whether the disability definition changes after benefits have been payable for a specified period.

Does any-occupation literally mean any job at all?

Not necessarily. The policy may define the occupations considered using criteria such as training, education, experience, functional capacity or earnings. Always read the actual definition.

Is Social Security Disability the same as any-occupation insurance?

No. Social Security is a separate federal program with its own rules. SSA generally considers whether you can perform past work and, if not, whether you can adjust to other work.

Where can I find my employer LTD definition?

Start with your Summary Plan Description and applicable insurance certificate or policy. The Department of Labor explains that the SPD provides important information about an ERISA-covered plan’s benefits and operation.

Final Thoughts

A disability policy can advertise:

$5,000 per month for years.

But before focusing on that number, ask:

What has to happen before the insurer considers me disabled?

That’s where:

own-occupation vs. any-occupation

becomes so important.

For someone with a specialized career, losing the ability to perform that specific occupation could destroy a substantial portion of their earning power—even if they’re technically capable of performing another type of work.

And remember that some policies can transition from one definition to another.

When comparing disability insurance in 2026, review:

Definition of disability → occupation definition → transition period → residual benefits → exclusions → elimination period → monthly benefit → benefit duration.

The biggest benefit amount isn’t necessarily the strongest policy.

The policy first has to recognize that you’re disabled.

The “Elimination Period” Explained: Why Your Waiting Period Matters More Than You Think

Professional reviewing a disability insurance timeline showing the waiting period before income benefits begin.

Quick Takeaway

When comparing disability insurance, most people immediately look at:

Monthly benefit + benefit period + premium.

But another number can have a major impact on both your coverage and your finances:

the elimination period.

An elimination period—also commonly called a waiting period—is the period between the beginning of a qualifying disability and when you become eligible to receive benefits under the policy.

The NAIC defines an elimination period as a specified number of days, weeks or months at the beginning of a covered loss during which no benefits are payable.

That means a policy can promise:

$5,000 per month in disability benefits

while still paying:

$0 during the elimination period.

Understanding how you’ll financially survive that gap can be just as important as choosing the benefit amount.

How Does an Elimination Period Work?

Consider a simple example.

You become disabled and unable to work on:

March 1.

Your long-term disability policy has a:

90-day elimination period.

During those 90 days, you satisfy the policy’s disability requirements but don’t yet receive LTD benefits.

Your financial timeline might look like:

Disability begins

90-day elimination period

Benefit eligibility begins

First payment according to the policy’s payment schedule

The NAIC notes that it can also be common to wait after the elimination period before receiving the first benefit payment, depending on the policy.

This makes cash-flow planning particularly important.

Elimination Period vs. Benefit Period

These two terms sound similar but mean completely different things.

Elimination period: How long you generally wait before benefits become payable.

Benefit period: How long qualifying benefits can potentially continue.

For example:

90-day elimination period

Benefits payable to age 65

means you generally need to satisfy the first 90 days before LTD benefits become payable, while qualifying benefits could potentially continue much longer under the policy terms.

Don’t confuse the two.

Think of It as a Time Deductible

With auto insurance, you might have a:

$1,000 deductible.

You absorb the first portion of a covered financial loss.

Disability insurance can work differently.

Instead of primarily asking:

“How much money do I pay first?”

the policy may ask:

“How long must the qualifying disability continue before benefits become payable?”

That’s why an elimination period can be thought of as a:

time deductible.

The longer the waiting period, the longer you need another way to fund your expenses.

Common Elimination Periods

Depending on the insurer and product, disability policies may offer different waiting periods.

You may encounter options such as:

  • 30 days
  • 60 days
  • 90 days
  • 180 days
  • Longer periods

The NAIC notes that a 30-day waiting period is common, but actual options vary by policy.

Long-term disability policies frequently use longer elimination periods than short-term coverage.

The important point isn’t finding a universally “best” number.

It’s choosing a waiting period that works with your:

Savings + employer benefits + paid leave + household expenses + other income protection.

Why Would Anyone Choose a Longer Waiting Period?

Because waiting periods can affect premiums.

The NAIC notes that policies with longer waiting periods generally have lower premiums.

Think about it from the insurer’s perspective.

A policy beginning benefits after:

30 days

potentially starts paying much sooner than one requiring:

180 days.

The second policy effectively transfers more of the short-term disability risk to you.

In exchange, premiums may be lower.

But cheaper isn’t automatically better.

The Hidden Cost of a Long Elimination Period

Imagine two policies.

FeaturePolicy APolicy B
Monthly Benefit$5,000$5,000
Elimination Period60 days180 days
Benefit PeriodTo age 65To age 65
PremiumHigherLower

Policy B looks attractive because it costs less.

But suppose you become disabled.

You may need to finance approximately:

six months of expenses

before LTD benefits become payable.

If your household spends:

$6,000 per month,

that’s potentially:

$36,000 of expenses

during a six-month period.

This simplified example ignores other income and exact claim timing, but it demonstrates the trade-off.

A lower insurance premium can create a much larger:

self-funded waiting-period obligation.

Your Emergency Fund and Elimination Period Should Work Together

This is perhaps the most important concept in this article.

Suppose your essential expenses are:

$5,000 per month.

You have:

$20,000 in accessible emergency savings.

Ignoring other income, that’s approximately:

four months of expenses.

A 90-day elimination period may therefore be financially manageable.

A 180-day elimination period?

Potentially much harder.

Before selecting a waiting period, calculate:

Essential monthly expenses × waiting-period months

Then compare the result with:

Emergency savings + paid leave + short-term disability + spouse/partner income + other reliable resources.

Example: 30-Day Elimination Period

Suppose:

Monthly essential expenses: $4,500

Waiting period: 30 days

Your household may need roughly:

$4,500

to fund essential expenses during that period, before considering other resources.

A shorter waiting period can reduce your immediate financial burden.

But the policy may cost more.

Example: 90-Day Elimination Period

Now assume:

Monthly essential expenses: $4,500

Waiting period: 90 days

Potential expenses during the waiting period:

$13,500

Again, that’s a simplified illustration.

If you have:

$25,000 in emergency savings,

the gap might be manageable.

If you have:

$2,000,

it could be a serious problem.

Example: 180-Day Elimination Period

Now use:

$4,500 × 6 months = $27,000.

A 180-day waiting period may reduce the insurance premium, but you are accepting considerably more short-term financial risk.

Ask yourself:

“Could I realistically finance six months without my normal paycheck?”

If not, choosing a very long waiting period purely because the premium is cheaper could undermine your financial protection.

Short-Term Disability Can Bridge the Gap

This is where short-term disability insurance can become useful.

Suppose your benefits are structured like this:

Days 1–7: Paid leave/emergency savings

Weeks 2–12: Short-term disability

After 90 days: Long-term disability

In a well-coordinated plan, short-term disability can potentially bridge much of the LTD elimination period.

But verify the actual dates.

You don’t want:

STD ends Day 60

while:

LTD begins after Day 90.

That could create a:

30-day income gap.

Don’t Assume Employer STD and LTD Automatically Line Up

Your employer may provide both.

Excellent.

But check:

When does STD end?

and:

When does LTD eligibility begin?

Suppose:

STD benefit period: 12 weeks

LTD elimination period: 180 days.

There could be a substantial period between the two.

Ask HR or the plan administrator for the actual plan documents rather than relying only on the benefits summary.

Paid Sick Leave Can Also Matter

Suppose you have:

4 weeks of paid sick leave

plus:

8 weeks of short-term disability

followed by:

90-day LTD elimination period.

Your protection may coordinate reasonably well.

Someone with:

zero paid leave

and

no short-term disability

faces a completely different financial situation even if both people own identical LTD policies.

This is why elimination periods should never be selected in isolation.

What Happens If You Recover During the Elimination Period?

Imagine you have a:

90-day elimination period.

You’re disabled for:

55 days

and then recover.

If the policy requires you to remain disabled throughout the applicable elimination period, you may never reach the point at which benefits become payable.

That isn’t necessarily a defect in the policy.

It’s part of the coverage design.

Longer elimination periods generally mean you’re retaining more short-duration disability risk yourself.

What If You Return to Work and Become Disabled Again?

This is where policy wording becomes extremely important.

Some policies may contain provisions addressing:

recurrent disability.

For example, a second disability related to the original condition within a specified period might potentially be treated as a continuation of the earlier claim rather than an entirely new disability.

But rules vary.

Check:

How does my policy treat recurrent disability during or after the elimination period?

Don’t assume the days automatically carry over.

Does the Waiting Period Require Consecutive Days?

Another important question.

Suppose your policy requires:

90 days.

You are disabled:

40 days

then return to work briefly,

then become disabled again.

Do the previous 40 days count?

The answer depends on the contract.

Some policies may allow certain non-consecutive disability days to count toward an elimination period under specified circumstances.

Others may operate differently.

Read the:

Elimination Period

and

Recurrent Disability

provisions together.

The Elimination Period Doesn’t Always Equal the First Payment Date

This catches many consumers by surprise.

Suppose your elimination period ends.

You may think:

“The money should appear tomorrow.”

Not necessarily.

The policy may pay benefits:

monthly in arrears

or according to another claims-payment schedule.

The NAIC specifically notes that it can be common to wait up to 30 days after a waiting period before receiving the first benefit payment.

So when building your emergency fund, don’t plan only until:

Day 90.

Consider when the:

first actual payment

would likely arrive under your policy.

The 90-Day Trap

Suppose you calculate:

90 days × expenses = $15,000.

So you save:

exactly $15,000.

But you haven’t considered:

  • Claims processing
  • Payment schedule
  • Unexpected medical expenses
  • Health insurance costs
  • Household emergencies
  • Reduced spouse/partner income
  • Expenses not included in your estimate

Having exactly enough money to reach the elimination-period finish line can leave little margin for error.

A financial buffer can be valuable.

Don’t Confuse Private LTD With Social Security’s Waiting Period

This distinction is important.

Your private disability insurance policy has its own contractual elimination period.

Social Security Disability Insurance operates under separate federal rules.

SSA generally requires eligible disabled-worker beneficiaries to serve a five-full-calendar-month waiting period before disability insurance benefits can begin, although exceptions apply in certain circumstances.

Social Security also uses its own disability definition and generally does not pay benefits for short-term or partial disability.

Therefore:

Private LTD elimination period ≠ SSDI waiting period.

They are separate systems.

A 90-Day LTD Period Doesn’t Mean SSDI Begins on Day 91

This is another potentially costly assumption.

Your private LTD policy could potentially begin benefits after its contractual waiting period if you satisfy its disability definition.

Social Security has:

different eligibility rules + different disability definition + different waiting-period rules.

SSA generally requires a medically determinable impairment expected to result in death or last continuously for at least 12 months and uses additional work-related eligibility standards.

Don’t build a financial plan assuming the two programs begin simultaneously.

Longer Isn’t Always Better—or Worse

A longer elimination period can make sense when you have:

Large emergency savings

Generous paid leave

Strong short-term disability coverage

Another dependable household income

and want to insure primarily against catastrophic long-duration income loss.

A shorter elimination period may make more sense when:

Savings are limited

Your household depends heavily on your paycheck

You lack STD

or

Even two months without income would create financial stress.

The appropriate choice depends on your financial situation.

High Earners Should Look Beyond the Waiting Period

Suppose you earn:

$200,000 per year.

You have enough savings to handle:

180 days without income.

A longer elimination period may appear reasonable.

But don’t stop there.

Also check:

Maximum monthly benefit.

If your LTD policy replaces:

60% of income

but has a relatively low monthly maximum, your actual replacement percentage could be much lower.

The NAIC says typical disability policies may replace around 60% of pre-disability earned income, although benefits and offsets vary by policy.

Self-Employed Workers Need a Different Calculation

If you’re self-employed, losing your ability to work can affect both:

household income

and

business cash flow.

Suppose you’re a consultant.

You become disabled.

Your personal expenses continue.

But so might:

Office rent

Software subscriptions

Employee wages

Business loans

Professional fees.

Personal disability income insurance isn’t necessarily designed to pay all business overhead expenses.

Business owners should evaluate personal and business obligations separately.

Build a Waiting-Period Fund

One practical strategy is creating a dedicated amount of accessible savings capable of covering the elimination period.

For example:

Essential expenses: $5,500/month

Elimination period: 90 days

Approximate basic target:

$16,500

Then consider an additional buffer for:

healthcare + unexpected expenses + payment timing.

This isn’t a universal savings recommendation.

It’s simply a useful method for understanding the financial risk you’re retaining.

Don’t Count Retirement Savings Too Easily

You might say:

“I have $150,000 in my retirement account. I can handle a six-month waiting period.”

But retirement assets may involve:

tax consequences + withdrawal restrictions + lost investment growth + retirement-plan damage.

Your disability waiting-period strategy should ideally emphasize appropriately accessible resources rather than assuming every asset is equally available.

Your Spouse’s Income Can Change the Decision

Consider two households.

Household A

One income.

Three dependents.

Limited savings.

Household B

Two strong incomes.

No dependents.

Large emergency fund.

A 180-day waiting period represents very different financial risk for each.

Your insurance should reflect your household balance sheet—not someone else’s recommendation online.

Review Your Waiting Period When Life Changes

The elimination period you selected at:

age 28

may no longer make sense at:

age 42.

Why?

Perhaps you now have:

children + mortgage + higher expenses.

Or perhaps the opposite happened.

You now have:

larger savings + lower debt + two household incomes.

Review disability coverage after major changes involving:

  • Marriage
  • Children
  • Home purchase
  • Income increase
  • Career change
  • Self-employment
  • Major debt changes
  • Significant savings growth
  • Employer-benefit changes

Questions to Ask Before Choosing an Elimination Period

Ask your insurer, broker or benefits administrator:

  1. How long is my elimination period?
  2. Does it apply to both illness and injury?
  3. Must the disability days be consecutive?
  4. How are partial-disability days counted?
  5. What happens if I temporarily return to work?
  6. How does recurrent disability work?
  7. When does the elimination period officially begin?
  8. When is the first benefit actually paid?
  9. Does changing the elimination period change my premium?
  10. What short-term disability benefits coordinate with LTD?
  11. Does paid leave affect the benefit?
  12. Do other disability benefits create offsets?
  13. What definition of disability applies during the waiting period?
  14. Do different conditions have different limitations?
  15. Does the elimination period reset for a new disability?

How to Choose Your Waiting Period

A useful approach is to follow four steps.

Step 1: Calculate Essential Expenses

Determine the minimum amount your household needs each month.

Include:

Housing + food + utilities + transportation + insurance + debt + healthcare + essential family costs.

Step 2: Identify Available Resources

Calculate what would be available if your paycheck stopped.

Consider:

Emergency savings + paid sick leave + STD + spouse/partner income + other reliable resources.

Step 3: Model Several Waiting Periods

For example:

Waiting PeriodEssential Expenses at $5,000/Month
30 days~$5,000
60 days~$10,000
90 days~$15,000
180 days~$30,000

These figures are simplified illustrations rather than exact insurance calculations.

Step 4: Compare Premium Savings With Added Risk

Ask:

How much premium do I save by moving from 90 to 180 days?

Then compare that saving with:

another three months of expenses you must potentially finance yourself.

That’s a much better comparison than simply choosing the cheapest premium.

2026 Elimination Period Checklist

Before selecting or renewing disability insurance:

  • Find your current elimination period.
  • Calculate essential monthly expenses.
  • Calculate accessible emergency savings.
  • Check available paid sick leave.
  • Review short-term disability.
  • Determine when STD ends.
  • Determine when LTD eligibility begins.
  • Check for an STD/LTD coverage gap.
  • Confirm how disability days are counted.
  • Review recurrent-disability rules.
  • Check partial-disability provisions.
  • Determine when the first payment arrives.
  • Review the disability definition.
  • Check the maximum monthly benefit.
  • Review benefit offsets.
  • Compare several waiting-period options.
  • Compare premium differences.
  • Maintain an adequate financial buffer.
  • Review coverage after major life changes.

Frequently Asked Questions

What is an elimination period in disability insurance?

It’s the period beginning with a qualifying disability during which benefits aren’t payable. The NAIC defines it as a specified number of days, weeks or months starting at the beginning of a loss during which no benefits are payable.

Is an elimination period the same as a waiting period?

In disability insurance, the terms are commonly used to describe the period you must wait before becoming eligible for benefit payments under the policy. The NAIC itself refers to “Waiting/Elimination Period” when explaining disability coverage.

Is a 30-day or 90-day elimination period better?

Neither is universally better. A shorter period can provide earlier benefit eligibility but may cost more. A longer waiting period may lower premiums but requires you to finance more of the initial disability period yourself.

Does disability insurance pay during the elimination period?

Generally, no. That’s the fundamental purpose of the elimination period: benefits aren’t payable during that specified period.

Does a longer elimination period lower disability insurance premiums?

Generally, yes. The NAIC notes that policies with longer waiting periods generally have lower premiums.

Does the first disability payment arrive immediately when the waiting period ends?

Not necessarily. Payment schedules and claims procedures vary. The NAIC notes that it may be common to wait after the waiting period before receiving the first benefit.

Can short-term disability cover an LTD elimination period?

Potentially. Short-term disability can sometimes provide income during part or all of an LTD waiting period, depending on how the plans are structured.

Does Social Security have an elimination period?

SSDI generally has a separate five-full-calendar-month waiting period before disabled-worker benefits become payable, with certain exceptions.

Final Thoughts

The elimination period may look like a minor number buried in your disability policy.

It isn’t.

It determines how long you could potentially need to survive without disability benefits after a qualifying disability begins.

A:

30-day waiting period

may provide earlier protection but potentially cost more.

A:

90-day waiting period

may work well when combined with adequate savings or short-term disability benefits.

A:

180-day waiting period

may reduce premiums but transfers substantially more short-term financial risk to you.

The goal shouldn’t simply be:

“Choose the shortest waiting period.”

Nor should it be:

“Choose the longest period to save money.”

Instead, coordinate:

Emergency savings + paid leave + short-term disability + LTD elimination period + first-payment timing.

The best waiting period is one your household can realistically finance without undermining the long-term protection you purchased disability insurance to provide.

Short-Term vs. Long-Term Disability: Which Does Your 2026 Financial Plan Need?

Professional couple comparing short-term and long-term disability insurance as part of their financial plan.

Quick Takeaway

Short-term and long-term disability insurance serve the same basic purpose:

helping replace part of your income when a covered disability prevents you from working.

But they protect different parts of your financial timeline.

Short-term disability (STD) is generally designed for temporary periods away from work.

Long-term disability (LTD) is designed for disabilities that continue much longer—potentially for years.

The NAIC says short-term disability commonly replaces a portion of income for about three to six months, while long-term coverage generally begins later and may continue for years or even until retirement age, depending on the policy.

For many households, therefore, the question shouldn’t necessarily be:

“Which one should I choose?”

It may be:

“How should short-term coverage, emergency savings and long-term disability insurance work together?”


What Is Disability Income Insurance?

Disability income insurance is designed to replace part of the income you lose when a qualifying illness or injury prevents you from working.

It is not the same as health insurance.

Health insurance primarily helps pay eligible:

  • Doctor bills
  • Hospital expenses
  • Prescription costs
  • Medical treatment

Disability insurance focuses on something different:

your lost income.

That distinction matters because your bills don’t disappear simply because you cannot work.

You may still need to pay:

Mortgage or rent + groceries + utilities + transportation + insurance + debt payments + everyday family expenses.

The NAIC defines disability income insurance as coverage designed to compensate insured people for a portion of income lost because of a disabling injury or illness.

What Is Short-Term Disability Insurance?

Short-term disability insurance provides income protection for a relatively limited period.

Depending on the specific policy, it may pay benefits when a qualifying disability temporarily prevents you from working.

The NAIC says short-term disability typically replaces part of a policyholder’s salary for approximately three to six months.

Exact benefit periods vary considerably by plan.

Short-term disability is frequently offered as an employee benefit, although availability depends on the employer and jurisdiction.

When Could Short-Term Disability Help?

Imagine you earn:

$5,000 per month.

An illness or injury prevents you from working for three months.

Without disability coverage, you might need to rely on:

Emergency savings

Paid leave

Family income

Credit cards or loans

Short-term disability could potentially replace part of your lost earnings during a qualifying absence.

The actual amount depends entirely on your policy.

What Is Long-Term Disability Insurance?

Long-term disability insurance addresses a much larger financial risk:

What happens if you cannot return to work for years?

The NAIC describes long-term disability income insurance as providing monthly income payments when an insured person becomes disabled for an extended period.

Depending on the policy, benefits might continue for:

several years

or potentially:

until a specified age.

This makes LTD fundamentally different from temporary income protection.

Short-Term vs. Long-Term Disability at a Glance

FeatureShort-Term DisabilityLong-Term Disability
Primary purposeTemporary income protectionExtended income protection
Typical durationOften several monthsPotentially several years
Benefits beginUsually relatively quicklyGenerally after a longer waiting period
Income replacedPortion of earningsPortion of earnings
Best suited forTemporary qualifying disabilitiesSerious or prolonged qualifying disabilities
Financial roleBridge a shorter income gapProtect against long-term loss of earning capacity

Exact definitions, waiting periods and benefit durations vary by policy.

The Most Important Difference Is Time

Think of disability risk as a timeline.

Day 1

You become unable to work.

Emergency savings / sick leave

Short-term disability

Long-term disability

Return to work or benefits continue according to policy terms

A properly coordinated financial plan attempts to prevent gaps between these stages.

What Is an Elimination Period?

An elimination period is the period after disability begins during which benefits aren’t payable.

The NAIC describes it as a specified number of days, weeks or months beginning at the start of a loss during which no benefits are payable.

Think of it somewhat like a:

time-based deductible.

Suppose your LTD policy has a:

90-day elimination period.

If you experience a qualifying disability, the policy generally won’t begin paying immediately.

You need a strategy for those first 90 days.

That might involve:

savings + sick leave + PTO + short-term disability.

Why Short-Term Disability Can Fill the Gap

Suppose your financial protection looks like this:

Days 1–7: Paid leave

Weeks 2–12: Short-term disability

After Day 90: Long-term disability

The exact dates will depend on your plans, but the concept is important.

Your policies should ideally complement each other rather than accidentally creating:

an uninsured income gap.

How Much Income Does Disability Insurance Replace?

Disability insurance generally does not replace 100% of your salary.

The NAIC says a typical disability policy benefit is approximately 60% of earned pre-disability income, although actual percentages depend on the policy and other sources of support.

Suppose you earn:

$6,000 per month.

A hypothetical policy replacing 60% could provide:

$3,600 per month

before considering policy limits, offsets, taxation and other provisions.

That leaves:

$2,400 less than your normal monthly earnings.

This is why disability insurance should be integrated with your overall financial plan.

Start With Your Essential Monthly Expenses

Before deciding how much disability protection you need, calculate your essential spending.

For example:

Monthly ExpenseAmount
Mortgage/Rent$2,000
Food$800
Utilities$350
Transportation$600
Insurance$500
Debt Payments$400
Other Essentials$600
Total$5,250

Now compare:

Essential expenses: $5,250

against:

Potential disability benefit: $3,600.

You have a potential:

$1,650 monthly gap.

This type of calculation is more useful than simply asking:

“Is 60% enough?”

The NAIC similarly recommends considering critical obligations such as housing, food, transportation, utilities, savings and healthcare when determining disability coverage needs.

Short-Term Disability Protects Your Immediate Cash Flow

Short-term disability can be particularly useful if you don’t have enough liquid savings to cover several months without a paycheck.

Ask yourself:

Could I pay every essential household expense for three months if my paycheck stopped tomorrow?

If the answer is no, short-term income protection deserves attention.

But Emergency Savings Can Change the Calculation

Suppose Household A has:

$3,000 emergency savings.

Household B has:

$60,000 emergency savings.

Both earn the same income.

Their need for short-term disability coverage may be very different.

Household B might be capable of self-funding a temporary income interruption.

But even substantial savings can be vulnerable to a disability lasting:

2 years, 5 years or longer.

That is where LTD becomes especially important.

Long-Term Disability Protects Your Earning Power

Your largest financial asset may not be:

your house

or

your retirement account.

For many working adults, it is their ability to earn income for decades.

Imagine a 35-year-old earning:

$80,000 annually.

If that person otherwise expected to work another 30 years, future gross earnings could total millions of dollars before considering raises, taxes or investment growth.

A prolonged disability can therefore be financially devastating even for someone with good savings.

Disability Is Not Just an Accident Risk

Many people associate disability with:

car crashes

workplace accidents

or

sports injuries.

But disability can also arise from illness.

Depending on the policy, qualifying conditions can include both injuries and illnesses.

The NAIC specifically notes that covered disabilities vary by policy and that some policies may cover only disability resulting from accidents rather than illness.

Always verify what your policy actually covers.

Don’t Assume Social Security Will Replace Your Paycheck

Social Security Disability Insurance can provide important protection for eligible workers.

But SSDI should not automatically be treated as a substitute for private disability insurance.

Social Security uses a strict definition of disability.

To qualify under its disability standard, your medical condition generally must prevent substantial gainful activity and have lasted—or be expected to last—at least 12 continuous months or result in death. Social Security does not pay benefits for partial or short-term disability.

That means a person could be unable to work for several months yet not qualify for Social Security disability benefits.

How Common Is Disability Risk?

According to the Social Security Administration’s 2026 disability publication, studies indicate that a 20-year-old worker has approximately a 1-in-4 chance of developing a disability before reaching full retirement age.

That doesn’t mean one in four workers will necessarily need a private LTD claim.

But it demonstrates why loss of earning ability deserves a place in financial planning.

Employer Disability Insurance: Start Here

Before purchasing anything independently, check your employee benefits.

You may already have:

Short-term disability

Long-term disability

or both.

Ask HR for the actual:

Summary Plan Description or certificate of coverage.

Don’t rely solely on a benefits-page statement saying:

“LTD Included.”

You need to understand what that means.

Questions to Ask About Employer Coverage

Find out:

  • What percentage of income is replaced?
  • Is there a monthly benefit cap?
  • How long is the elimination period?
  • How long can benefits continue?
  • Who pays the premium?
  • Are benefits potentially taxable?
  • What definition of disability applies?
  • Is partial disability covered?
  • Does coverage continue if you leave your employer?
  • What offsets apply?

These details can completely change the value of the benefit.

Watch the Monthly Benefit Cap

Suppose your employer plan says:

60% income replacement.

You earn:

$15,000 per month.

You might initially expect:

$9,000 monthly benefit.

But suppose the policy has a:

$6,000 monthly maximum.

Your actual maximum benefit could be much lower than 60% of your earnings.

Higher earners should pay particular attention to benefit caps.

“Own Occupation” vs. “Any Occupation”

This is one of the most important LTD provisions.

The definition of disability determines when you qualify for benefits.

The NAIC notes that some policies may pay when you cannot perform your own occupational duties, while others require that the disability prevent you from performing other gainful employment for which you are qualified.

Consider a surgeon who develops a condition affecting fine hand movements.

The surgeon may no longer be capable of surgery.

But perhaps they could still:

teach medicine

or

work in administration.

Whether they qualify for benefits may depend partly on the policy’s definition of disability.

Never buy LTD based solely on:

price + percentage + benefit amount.

Read the definition.

Partial and Residual Disability

Disability isn’t always:

working normally

or

not working at all.

Suppose you previously worked:

40 hours per week

but after an illness can manage only:

20 hours.

Your income falls significantly.

Some disability policies provide residual or partial disability benefits in qualifying situations.

The NAIC explains that residual benefits can help fill an income gap when a disability reduces your ability to perform your job and causes reduced income.

This can be an extremely valuable feature.

How Long Should LTD Benefits Last?

Long-term disability policies may offer different benefit periods.

Examples can include:

2 years

5 years

10 years

or

to a specified age.

The NAIC notes that shorter benefit periods generally cost less but create the possibility that benefits could end while the person remains disabled.

Think carefully about the risk you’re trying to insure.

A six-month disability can damage your emergency fund.

A 15-year disability can fundamentally change your family’s financial future.

Consider Inflation Protection

Imagine receiving:

$5,000 per month

in LTD benefits.

That might cover your expenses today.

But what if you’re still disabled:

15 years from now?

Inflation can reduce the purchasing power of a fixed benefit.

Some policies offer a:

Cost-of-Living Adjustment (COLA)

feature.

The NAIC notes that inflation protection may be available for an additional premium and that disability benefits don’t necessarily rise automatically with your earnings.

This feature can be particularly relevant for younger workers buying long-duration protection.

Future Increase Options

Suppose you’re 28 and earn:

$70,000.

Ten years later you earn:

$140,000.

Coverage purchased at 28 may no longer adequately protect your income.

Some individual disability policies may offer options allowing eligible policyholders to increase coverage later, subject to the policy’s terms.

For professionals expecting significant income growth, this feature can deserve attention.

Short-Term Disability May Be More Important If…

STD may deserve greater priority when you:

  • Have limited emergency savings
  • Have little paid sick leave
  • Depend heavily on one paycheck
  • Couldn’t comfortably absorb several months without income
  • Have substantial fixed monthly expenses
  • Have an LTD policy with a significant waiting period

But that doesn’t automatically mean STD should replace emergency savings.

Ideally, the two work together.

Long-Term Disability May Be More Important If…

LTD deserves particularly serious consideration when:

  • Your household depends heavily on your income
  • You have many working years ahead
  • You have a mortgage
  • You support children or other dependents
  • Your emergency fund couldn’t sustain years without income
  • Your employer’s LTD coverage is limited
  • You’re self-employed
  • You have substantial future earning potential

For many working households, the financial consequences of a permanent or multi-year income loss are much greater than those of a temporary absence.

Do You Need Both?

Potentially.

Think about three financial layers:

Layer 1 — Emergency Fund

Handles immediate expenses.

Layer 2 — Short-Term Disability

Can help replace income during qualifying temporary disabilities.

Layer 3 — Long-Term Disability

Can protect against prolonged loss of earning ability.

A strong plan coordinates these layers.

Example: Using Both Policies Together

Consider Maya, age 38.

She earns:

$90,000 annually.

Her employer provides:

STD: 60% of salary for up to 12 weeks

LTD: 60% after a 90-day elimination period, subject to policy limits.

She also maintains:

four months of essential expenses in savings.

If Maya experiences a qualifying long-term disability, her protection could potentially work approximately like this:

Emergency savings/PTO

STD benefits

LTD benefits

The exact claim timing and payments would depend on her plans.

But financially, the coverages are designed to complement one another.

Example: Strong Savings but No LTD

Now consider Daniel.

He has:

12 months of expenses saved.

He decides:

“I don’t need disability insurance.”

For a three-month disability, he may be right that his savings can absorb the loss.

But what happens if he cannot work for:

eight years?

His emergency fund wasn’t designed for that.

This illustrates why the argument for LTD can remain strong even when someone has substantial short-term savings.

Self-Employed Workers Need Special Attention

Employees may receive disability benefits through work.

A freelancer, consultant or business owner may not.

If you’re self-employed, ask:

What happens to my household income if I cannot work?

And separately:

What happens to my business expenses?

Personal disability income insurance is designed primarily to protect personal income.

Business owners may need additional insurance strategies for business-related expenses or continuity.

Disability Insurance Is Not Workers’ Compensation

Workers’ compensation generally concerns qualifying work-related injuries and illnesses under state law.

Disability insurance can potentially apply to covered disabilities regardless of whether they happened at work, depending on the policy.

Don’t assume:

“My employer has workers’ comp, so I don’t need disability insurance.”

They solve different problems.

Disability Insurance Is Not Long-Term Care Insurance

These are also different products.

Disability insurance: helps replace lost income when disability prevents you from working.

Long-term care insurance: addresses qualifying care needs and services.

The words:

“long-term”

appear in both, but the products serve different purposes.

How Taxes Can Affect Your Disability Benefit

Tax treatment can depend partly on:

who paid the premium

and

how it was paid.

This can materially affect how much spendable income you actually receive during disability.

Rather than estimating your protection from the headline benefit alone, review the tax treatment of your particular plan with a qualified tax professional.

How to Compare Disability Policies

When comparing policies, don’t look only at:

monthly premium.

Review:

Definition of disability

Benefit percentage

Maximum monthly benefit

Elimination period

Benefit period

Partial/residual disability

Exclusions

Pre-existing-condition provisions

Offsets

Renewability

COLA options

Future increase options

Claims procedures.

The NAIC specifically recommends comparing many of these provisions when evaluating LTD policies.

Guaranteed Renewable vs. Non-Cancelable

These terms matter.

The NAIC explains that many LTD policies contain one of two common renewability structures.

With guaranteed renewable coverage, the insurer generally must continue renewing the policy when required conditions are met, but premiums may potentially increase for an applicable class.

With a non-cancelable policy, coverage and premiums generally cannot be changed by the insurer while the required premiums are paid, subject to the contract.

Read the actual policy wording.

Don’t Wait Until You Need Coverage

Disability insurance is generally easier to evaluate before a health problem affects your insurability.

Individual disability coverage may involve underwriting.

Depending on the insurer and policy, health history, occupation, income and other factors can affect:

eligibility + premium + exclusions + available benefits.

That makes disability planning something to consider while you’re healthy and working—not only after a problem occurs.

A Simple 2026 Disability Planning Exercise

Start with these four numbers:

1. Monthly take-home income

Example: $6,500

2. Essential monthly expenses

Example: $4,800

3. Emergency savings

Example: $20,000

4. Existing employer disability benefit

Example: $3,900/month

Now ask:

How many months could my savings cover the difference?

If benefits provide:

$3,900

while expenses are:

$4,800,

the monthly shortfall is:

$900.

That is manageable with $20,000 savings for a substantial period.

But if you have:

no disability coverage,

your monthly gap may be much larger.

This exercise helps turn an abstract insurance decision into a financial-planning decision.

Which Does Your 2026 Financial Plan Need?

There isn’t one answer for everyone.

But a useful way to think about the decision is:

Short-Term Disability = Protect the next several months

Long-Term Disability = Protect the next several years

If you can comfortably self-fund several months without income, short-term coverage may be less critical.

If losing your income for years would seriously damage your financial future, LTD may be much harder to replace with savings alone.

And if your household would struggle with either scenario:

you may need both.

2026 Disability Insurance Checklist

Before purchasing or renewing coverage:

  • Calculate essential monthly expenses.
  • Determine how many months your emergency fund can cover.
  • Check employer STD benefits.
  • Check employer LTD benefits.
  • Confirm the income-replacement percentage.
  • Check the maximum monthly benefit.
  • Review the elimination period.
  • Review the maximum benefit period.
  • Read the definition of disability.
  • Check own-occupation provisions.
  • Review partial/residual benefits.
  • Check exclusions.
  • Review pre-existing-condition provisions.
  • Check benefit offsets.
  • Understand potential tax treatment.
  • Consider inflation protection.
  • Review future increase options.
  • Understand renewability.
  • Consider portability if you leave your employer.
  • Reassess coverage after major income or family changes.

Frequently Asked Questions

What is the main difference between short-term and long-term disability insurance?

The primary difference is the period of income protection. Short-term disability generally covers temporary qualifying disabilities, while LTD is designed for longer periods. The NAIC says STD commonly replaces part of income for three to six months, while LTD may continue for years or potentially until retirement age.

Does disability insurance replace 100% of my salary?

Usually not. The NAIC says a typical disability policy benefit is approximately 60% of pre-disability earned income, although actual benefits vary considerably by policy.

Can I have short-term and long-term disability insurance together?

Yes. The two can complement each other, with STD potentially providing protection during an LTD policy’s waiting period.

Is an emergency fund enough instead of short-term disability?

Possibly, depending on the size of your emergency fund, expenses and risk tolerance. Someone with substantial liquid savings may be more capable of self-funding a short disability.

Is an emergency fund enough instead of long-term disability?

For most households, funding many years without earnings would require dramatically more savings than covering a few months. This is why LTD addresses a fundamentally different financial risk.

Does Social Security cover short-term disability?

No. Social Security says it does not pay benefits for partial or short-term disability. A qualifying condition generally must have lasted or be expected to last at least 12 months or result in death.

What does a 90-day elimination period mean?

It generally means benefits aren’t payable during the first 90 days of a qualifying disability, subject to the policy’s terms. The NAIC defines an elimination period as the specified period at the beginning of a loss during which benefits are not payable.

Does long-term disability last forever?

Not necessarily. Benefit periods vary. Some policies may pay for a specified number of years, while others may potentially provide benefits to a specified age, assuming the insured continues meeting the policy’s disability definition.

Should self-employed people consider disability insurance?

Yes, particularly when the household depends heavily on income generated by the person’s ability to work. Self-employed individuals should also distinguish personal income protection from insurance protecting ongoing business expenses.

Final Thoughts

The difference between short-term and long-term disability insurance becomes clearer when you stop thinking about them as competing products.

They protect different periods.

Emergency savings protect today.

Short-term disability can protect the coming months.

Long-term disability can protect against years of lost earning ability.

For your 2026 financial plan, start by calculating:

How long could I maintain my household if my paycheck stopped tomorrow?

Then ask the more difficult question:

What happens if I still can’t work two years from now?

If your savings comfortably answer the first question but not the second, LTD may deserve greater priority.

If neither scenario is financially manageable, combining:

emergency savings + STD + LTD

can create a more complete income-protection strategy.

The goal isn’t to buy the most insurance.

It’s to prevent a disability from turning into a long-term financial crisis.

Usage-Based Commercial Auto: How Telematics 2.0 Can Save Your Fleet 20%

Fleet manager reviewing telematics driving data beside commercial delivery vans.

Commercial auto insurance has traditionally looked backward.

Insurers examine:

Past accidents + claims history + vehicle types + driver records + operating territory

and use those factors to estimate what might happen next.

Telematics changes the equation.

Instead of asking only:

“What happened to this fleet during the last five years?”

insurers can increasingly ask:

“How are these vehicles being driven today?”

Modern telematics can measure mileage, driving times, rapid acceleration, hard braking, hard cornering and other driving characteristics. The NAIC explains that usage-based insurance can use this information to align premiums more closely with actual driving behavior.

For businesses operating:

  • Delivery vans
  • Service vehicles
  • Contractors’ trucks
  • Sales fleets
  • Commercial cars
  • Light trucks
  • Regional transportation fleets

this can create an opportunity.

A company with demonstrably safer drivers may be able to turn:

good driving → better risk profile → potentially better insurance economics.

But telematics is not simply about installing GPS trackers.

The real value comes from what the business does with the data.

What Is Commercial Auto Telematics?

Telematics combines:

Vehicle + sensors + GPS + communications + data analytics.

Depending on the system, information can come from:

  • Built-in vehicle technology
  • Plug-in devices
  • Hardwired equipment
  • Smartphones
  • Fleet-management platforms

The information is transmitted to software that analyzes vehicle use and driver behavior.

The NAIC identifies telematics measurements including:

Mileage

How far the vehicle travels.

Time of day

When driving occurs.

Location

Where vehicles operate.

Rapid acceleration

How frequently drivers accelerate aggressively.

Hard braking

How frequently drivers brake suddenly.

Hard cornering

Potentially risky turning behavior.

Airbag deployment

Information potentially useful after an accident.

More advanced commercial platforms can combine this information with broader fleet-management data.

Traditional Insurance vs. Usage-Based Insurance

Consider two plumbing companies.

Plumbing Company A

  • 20 vans
  • Drivers average 10,000 miles annually.
  • Most driving occurs during daylight.
  • Low harsh-braking frequency.
  • Strong safety program.
  • Few claims.

Plumbing Company B

  • 20 vans
  • Drivers average 30,000 miles annually.
  • Significant late-night driving.
  • Frequent hard braking.
  • Aggressive acceleration.
  • Multiple claims.

Traditional rating methods certainly won’t treat every fleet identically.

But telematics can give insurers considerably more detailed information about how vehicles are actually being operated.

The basic UBI principle is:

Lower demonstrated risk → potentially more favorable pricing.

The NAIC says telematics allows insurers to use real-time driver behavior and usage information to price risk more accurately and provide premium discounts in appropriate programs.

Why Commercial Auto Insurance Is a Major Business Expense

A fleet accident can generate much more than a repair bill.

One crash can potentially involve:

  • Vehicle damage
  • Third-party property damage
  • Bodily injury
  • Medical expenses
  • Legal defense
  • Lost productivity
  • Vehicle downtime
  • Replacement rental
  • Cargo damage

A serious liability claim can be especially expensive.

That means reducing accident frequency can have value beyond an insurance discount.

The better objective is:

Reduce losses first.

Potential insurance savings can follow.

Telematics 1.0 Was Mostly About Location

Early fleet telematics often answered relatively simple questions:

Where is the truck?

Where has it been?

How many miles did it travel?

This was extremely useful for:

  • Dispatch
  • Route planning
  • Vehicle recovery
  • Mileage records

But today’s systems can potentially provide much richer information.

Telematics 2.0 Is About Behavior

Modern fleet systems can potentially identify patterns such as:

Driver 1

Low-risk behavior.

Driver 2

Frequent hard braking.

Driver 3

Repeated speeding events.

Driver 4

High mileage.

Driver 5

Frequent aggressive acceleration.

Instead of managing fleet risk only after an accident, companies can potentially intervene:

before the accident happens.

That is the biggest difference.

Hard Braking Can Be an Early Warning

One hard-braking event doesn’t necessarily mean someone is a dangerous driver.

Perhaps:

another vehicle cut them off.

But repeated events can reveal a pattern.

Imagine:

Driver A: 3 harsh-braking events per 1,000 miles

versus:

Driver B: 35 events per 1,000 miles.

Driver B may deserve additional review.

Perhaps they are:

  • Following too closely
  • Driving too fast
  • Distracted
  • Operating on difficult routes

Telematics helps managers identify the pattern.

Speeding Matters

Commercial drivers often face schedule pressure.

A delivery driver may think:

“If I drive a little faster, I’ll finish the route earlier.”

But faster driving can increase accident severity and potentially contribute to more dangerous situations.

Telematics can help fleet managers identify repeated speeding patterns and coach drivers accordingly.

The objective should not be:

Catch the employee.

It should be:

Identify risk → coach driver → improve behavior → prevent crash.

Mileage Matters Too

A vehicle traveling:

5,000 miles annually

doesn’t have the same road exposure as one traveling:

50,000 miles annually.

The NAIC notes a strong relationship between mileage and claims/loss costs, which is one reason mileage is an important component of many usage-based programs.

For fleets whose vehicles are used irregularly, accurate mileage information can potentially be especially valuable.

Pay-As-You-Drive vs. Pay-How-You-Drive

These concepts are related but different.

Pay-As-You-Drive

Pricing emphasizes:

How much you drive.

Lower mileage may potentially mean lower cost.

Pay-How-You-Drive

Pricing considers:

How you drive.

That can include:

  • Braking
  • Acceleration
  • Cornering
  • Speed
  • Driving time

The NAIC identifies multiple UBI structures, including Pay-As-You-Drive and Pay-How-You-Drive.

Modern programs can combine both concepts.

Why the 20% Number Needs Caution

Suppose your current commercial auto premium is:

$100,000 per year.

A 20% reduction would equal:

$20,000.

That’s attractive.

But businesses should never assume:

Telematics installed = automatic 20% discount.

Actual results can depend on:

  • Insurer
  • State
  • Fleet size
  • Vehicle class
  • Driving behavior
  • Mileage
  • Claims history
  • Program rules
  • Underwriting
  • Regulatory requirements

Some drivers or fleets may receive meaningful savings.

Others may receive less.

And depending on the program, poor driving data may affect pricing unfavorably.

The NAIC explicitly warns consumers that UBI does not guarantee lower premiums and that driving behavior can potentially lead to higher premiums in some programs.

The Bigger Savings May Come From Fewer Accidents

This is where fleet managers should look beyond the insurance invoice.

Suppose telematics helps reduce:

speeding + harsh braking + distracted driving + unnecessary mileage.

That can potentially reduce:

  • Collisions
  • Fuel use
  • Maintenance
  • Tire wear
  • Vehicle downtime
  • Workers’ compensation incidents
  • Liability claims

The NAIC notes that telematics can also help fleets identify efficient routes, potentially reducing personnel, fuel and maintenance costs.

So even if the insurance discount is modest, operational savings may still make the technology valuable.

Example: A 50-Vehicle Service Fleet

Consider a hypothetical HVAC company.

It operates:

50 service vans.

Annual commercial auto premium:

$175,000.

Management introduces telematics.

During the first month, the system identifies:

  • 11 drivers with frequent hard braking
  • 8 with repeated speeding events
  • 6 with unnecessary idling
  • 4 with inefficient routes

Instead of punishing employees, management starts monthly coaching.

After six months:

harsh driving declines

speeding declines

mileage becomes more efficient

accident frequency improves.

At renewal, the company can present its broker and insurer with actual risk-management information.

That doesn’t guarantee a particular premium reduction.

But the business is in a stronger position than simply saying:

“We think our drivers are safe.”

It has data.

Data Can Improve the Renewal Conversation

Traditional insurance renewal discussions can sometimes look like:

Insurer: Your loss history is poor.

Business: We’ve improved safety.

Insurer: Prove it.

Telematics potentially provides that evidence.

The company can demonstrate:

Driver coaching completed

Speeding events down

Harsh braking down

Mileage controlled

Safety scores improving

Claims trending downward

This can give the broker better information when presenting the risk to insurers.

Telematics Can Help After an Accident

Consider this scenario.

A company driver says:

“I was traveling within the speed limit when another car pulled in front of me.”

The other driver says:

“The commercial van was speeding.”

Telematics data may potentially provide useful information about:

  • Speed
  • Location
  • Time
  • Braking
  • Vehicle movement

The NAIC notes that telematics can help insurers analyze driving data around an accident and potentially improve damage assessment and fraud detection.

Depending on the system, businesses may also combine telematics with dashcam footage.

Video Telematics Adds Another Layer

Modern commercial fleets increasingly combine:

Vehicle data + camera information.

This may help identify:

  • Distracted driving
  • Following distance
  • Road conditions
  • Collision circumstances
  • Unsafe behavior

But video introduces additional considerations involving:

privacy + employee monitoring + data retention + cybersecurity.

Businesses should establish clear policies before deploying driver-facing cameras.

Telematics Can Help Identify Distracted Driving

Phone distraction is particularly dangerous for commercial fleets.

Some modern systems may identify:

  • Phone handling
  • Driver distraction
  • Unsafe following
  • Seatbelt behavior

When appropriate technology and policies are used, fleet managers can coach drivers before risky behavior produces an accident.

Again, the objective should be:

prevention rather than surveillance for its own sake.

Driver Coaching Is Where the Real Value Appears

Installing a device doesn’t automatically make drivers safer.

Imagine:

Telematics installed January 1.

The dashboard generates:

15,000 alerts.

Nobody reviews them.

Nothing changes.

The company has collected:

data

but hasn’t created:

risk management.

A stronger process is:

Detect → Review → Coach → Measure → Improve.

Don’t Punish Every Alert

Telematics data requires context.

Hard braking might mean:

aggressive driving

or:

avoiding a child running into the road.

Managers shouldn’t treat every alert as proof of misconduct.

Look for:

patterns.

A driver with one event isn’t necessarily concerning.

A driver with consistently poor behavior may require intervention.

Create a Driver Scorecard

A fleet could track:

MetricDriver ADriver B
Speeding Events224
Harsh Braking431
Rapid Acceleration319
Seatbelt Compliance99%87%
Safety TrendImprovingDeclining

The precise metrics should match the technology and company’s operations.

Managers can then focus coaching where it matters.

Reward Good Drivers Too

Telematics shouldn’t only identify problems.

It can identify excellent drivers.

Consider recognition for:

  • Safe-driving streaks
  • Improved safety scores
  • Accident-free performance
  • Consistent seatbelt use
  • Reduced harsh-driving events

Positive reinforcement can help create a:

safety culture

rather than:

surveillance culture.

Route Optimization Can Reduce Exposure

Suppose your fleet collectively drives:

2 million miles annually.

Improved routing reduces that by:

100,000 miles.

That can mean:

  • Less fuel
  • Less maintenance
  • Less driver time
  • Less road exposure

The NAIC specifically recognizes route efficiency as a potential fleet benefit of telematics.

Insurance savings are therefore only one component of the business case.

Maintenance Data Can Help Too

Some fleet-management platforms can monitor vehicle information that may help identify maintenance needs.

That can help businesses address issues before a breakdown creates:

roadside incident + missed delivery + towing + downtime.

Preventive maintenance can also support broader fleet safety.

Telematics Can Help Fight Vehicle Theft

GPS-based vehicle location may help businesses recover stolen commercial vehicles.

The NAIC identifies vehicle theft recovery as one of the ancillary benefits associated with telematics technology.

For fleets with expensive:

trucks + equipment + tools

this can be valuable beyond insurance pricing.

Privacy Is the Big Trade-Off

Telematics works because it collects data.

That raises an obvious question:

How much monitoring is too much?

Depending on the system, information could include:

  • Vehicle location
  • Driving times
  • Routes
  • Speed
  • Driver behavior
  • Phone interaction
  • Video

The NAIC recognizes privacy as one of the major challenges surrounding telematics and usage-based insurance.

Businesses should be transparent about what is collected and why.

Employees Should Know What Is Being Monitored

A telematics policy should explain:

What data is collected?

When is it collected?

Why is it collected?

Who can access it?

How long is it retained?

Is it shared with the insurer?

Can it be used for disciplinary decisions?

Are cameras involved?

This is particularly important if employees can take company vehicles home.

After-Hours Tracking Can Be Sensitive

Suppose an employee is permitted personal use of a company vehicle.

The telematics device operates:

24/7.

The company could potentially see:

  • Evening trips
  • Weekend locations
  • Personal destinations

That creates legitimate privacy concerns.

Businesses should obtain appropriate employment and privacy advice before implementing monitoring programs, especially when personal vehicle use is permitted.

Cybersecurity Matters

Fleet telematics generates valuable information.

A system can contain:

vehicle locations + routes + employee information + operating schedules.

That data should be protected.

Ask vendors about:

  • Encryption
  • Authentication
  • Access controls
  • Data storage
  • Breach notification
  • Security testing
  • Data retention

Your fleet-management system shouldn’t become a new cybersecurity weakness.

Who Owns the Data?

This question should be answered before signing the telematics contract.

Is the data owned by:

Your business?

The telematics provider?

The insurer?

Can the vendor:

sell it?

aggregate it?

retain it after termination?

use it to train algorithms?

Review vendor terms carefully.

Don’t Install Telematics Only for the Discount

This is perhaps the most important practical advice.

If your entire strategy is:

Install device → get discount,

you’re missing most of the value.

A stronger strategy is:

Install telematics

Establish baseline

Identify risky drivers

Coach drivers

Improve routes

Reduce mileage

Reduce accidents

Document improvement

Present better risk to insurer

The insurance benefit becomes part of a larger fleet-safety program.

Which Fleets May Benefit Most?

Telematics may be particularly worth evaluating for businesses with:

  • Multiple commercial vehicles
  • High annual mileage
  • Delivery operations
  • Service technicians
  • Construction vehicles
  • Sales fleets
  • Distributed drivers
  • Expensive commercial auto premiums
  • Recent accident problems

It can also be useful for smaller fleets where the owner cannot personally observe every driver’s behavior.

Telematics Isn’t Right for Every Fleet

There can be costs.

Businesses may face:

  • Hardware expense
  • Software subscriptions
  • Installation
  • Management time
  • Driver training
  • Privacy concerns
  • Data-management requirements

If a company operates:

two vehicles

with very limited mileage, the economics may differ from a:

500-vehicle fleet.

Calculate total value rather than chasing a percentage discount.

2026 Fleet Telematics Checklist

Before implementing a program:

  • Ask your insurer whether it offers commercial UBI.
  • Ask whether telematics can reduce premiums.
  • Ask whether poor scores can increase premiums.
  • Identify exactly what data is collected.
  • Review privacy requirements.
  • Create an employee telematics policy.
  • Establish a baseline safety score.
  • Monitor speeding.
  • Monitor harsh braking.
  • Monitor rapid acceleration.
  • Review mileage.
  • Review after-hours driving.
  • Evaluate route efficiency.
  • Create driver coaching.
  • Reward strong performance.
  • Review accident trends.
  • Establish data-retention rules.
  • Review vendor cybersecurity.
  • Review data ownership.
  • Review dashcam requirements.
  • Document safety improvements.
  • Provide results to your broker.
  • Compare insurers at renewal.
  • Calculate total fleet savings—not only premium savings.

Questions to Ask Your Commercial Auto Broker

  1. Does the insurer offer telematics-based commercial auto pricing?
  2. What maximum discount is available?
  3. Is the discount guaranteed?
  4. Can telematics increase our premium?
  5. Which driving behaviors affect pricing?
  6. Does mileage affect pricing?
  7. Does driving time matter?
  8. How long must data be collected?
  9. Who owns the telematics data?
  10. Does the insurer receive raw data?
  11. Can telematics data be used during claims?
  12. Are dashcams required?
  13. Are there installation costs?
  14. Are there fleet-size requirements?
  15. Does participation affect renewal underwriting?
  16. Can safety improvements help us obtain better quotes elsewhere?
  17. Are discounts available in every state where we operate?
  18. How are multiple drivers per vehicle handled?
  19. What happens if a device stops transmitting?
  20. Can we leave the program later?

Frequently Asked Questions

What is usage-based commercial auto insurance?

Usage-based insurance uses information about vehicle usage and/or driving behavior to help determine insurance pricing. Telematics technology commonly supplies that information.

Can telematics reduce commercial auto premiums?

Potentially. Lower-risk driving can qualify for more favorable pricing under some usage-based programs, but discounts vary by insurer, jurisdiction and performance.

Can telematics save my fleet exactly 20%?

Don’t assume so. A 20% figure should be treated as an example or program-specific possibility, not a universal guarantee.

What does commercial telematics monitor?

Depending on the program, it can monitor mileage, time of day, location, acceleration, braking, cornering and other driving characteristics.

Can my premium increase?

Potentially, depending on the specific program. The NAIC advises that usage-based programs don’t necessarily benefit every driver and that poor driving behavior can result in unfavorable pricing under some programs.

Does telematics use GPS?

Many systems can collect GPS/location information, although the exact information collected depends on the technology and program.

Is telematics only useful for insurance?

No. Fleet operators can also use telematics for route efficiency, safety monitoring, vehicle location and other operational purposes.

Does telematics prevent accidents?

A device itself doesn’t prevent an accident. The value comes from using the information to identify risky behavior, coach drivers and improve fleet operations.

Are there privacy concerns?

Yes. Location and driver-behavior monitoring create privacy considerations. Businesses should understand applicable laws and communicate monitoring practices clearly.

Should a small business use telematics?

It can be worthwhile, especially when commercial auto costs or accident frequency are significant. Compare potential insurance and operational savings with technology and management costs.

Final Thoughts

Commercial auto insurance used to depend heavily on:

who you are + what you drive + where you operate + what happened in the past.

Telematics adds another dimension:

How are your vehicles actually being driven?

For a well-managed fleet, that can be powerful.

Instead of telling an insurer:

“Our drivers are safer now,”

you may be able to demonstrate:

Speeding ↓

Hard braking ↓

Unnecessary mileage ↓

Risky driving ↓

Accidents ↓

The NAIC notes that telematics can allow insurers to more closely connect premiums with actual driving performance while also helping fleets optimize routes and reduce fuel and maintenance costs.

But don’t build the business case around a promised 20% discount.

Build it around:

Safer drivers → fewer accidents → lower operating costs → better loss history → stronger insurance position.

If a substantial insurance discount follows, that’s an additional benefit.