Home Blog Page 10

Airbnb & Short-Term Rental Insurance: Why your standard home owners policy will likely deny a guest injury claim.

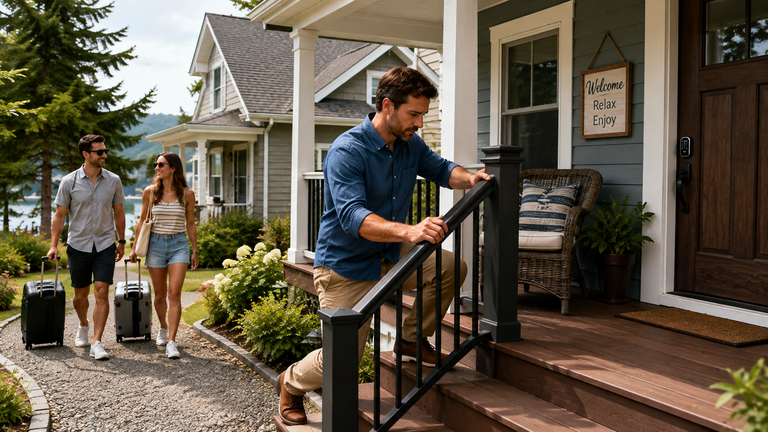
Short-term rental host inspecting exterior stairs and handrails before Airbnb guests arrive at a vacation rental home.

Introduction

Imagine this.

You list your home on Airbnb for a long weekend.

A guest arrives Friday evening.

Saturday morning, they walk down your exterior stairs.

A loose handrail gives way.

The guest falls, suffers a serious injury and later seeks compensation for:

Medical expenses

Lost income

Rehabilitation

and:

Pain and suffering.

You call your homeowners insurer expecting the personal-liability section of your policy to respond.

Instead, the insurer starts asking:

“Were you charging the guest to stay there?”

“How frequently do you rent the property?”

“Did you tell us the home was being used as a short-term rental?”

Those questions can completely change the claim.

Why?

Because a standard homeowners policy is principally designed for:

personal residential risk—not an undisclosed hospitality business.

The Insurance Information Institute (Triple-I) warns that standard homeowners and renters policies generally aren’t designed to cover regular short-term rental activity and that homeowners should discuss their plans with their insurer before renting through a home-sharing platform.

The National Association of Insurance Commissioners (NAIC) likewise warns consumers that standard homeowners or renters insurance may exclude losses arising from business activity and that home-sharing can create gaps requiring endorsements or specialized coverage.

So the title needs one important qualification:

Your standard homeowners insurer won’t automatically deny every Airbnb guest injury claim.

Occasional rental activity may be treated differently depending on the policy, insurer, state and circumstances.

But assuming your ordinary homeowners liability coverage automatically protects a short-term rental business is dangerous.

Here’s why.


The Core Problem: Home Insurance vs. Business Activity

A standard homeowners policy commonly provides personal liability protection.

Suppose a friend visits your house.

They slip on a dangerously broken step.

They suffer an injury.

Your homeowners liability coverage may potentially respond, depending on:

The circumstances

Your legal liability

Policy limits

Deductibles or conditions

and:

Exclusions.

Now change one fact.

The person wasn’t:

your friend.

They paid:

$300 per night

to stay in your home.

The property is listed publicly on a short-term rental platform.

That introduces:

business activity.

And business-related exclusions or limitations may become relevant.


Why Short-Term Rentals Create a Different Risk

From an insurer’s perspective, your ordinary home and an active vacation rental aren’t necessarily the same exposure.

A normal household may have:

a few visitors.

A busy short-term rental might have:

dozens of unrelated guests every month.

Those guests may:

Use unfamiliar stairs

Cook in the kitchen

Use a swimming pool

Walk around at night

Use balconies

Operate fireplaces

Bring children

and:

Invite additional visitors.

More guest turnover can create different liability and property risks.

That’s why insurers want to know how the property is actually being used.


What Does Personal Liability Insurance Normally Do?

Homeowners insurance generally includes personal-liability protection.

This can potentially help when you’re legally responsible for bodily injury or property damage suffered by someone else.

For example:

A visitor trips because of a dangerous condition.

Or:

Your dog injures someone.

Or:

Your negligence causes damage to another person’s property.

Coverage depends on policy terms and exclusions.

The problem for Airbnb hosts is that:

personal liability isn’t automatically business liability.


The Business Exclusion Problem

Standard homeowners policies commonly contain restrictions involving:

business activity.

The exact wording varies.

That’s crucial.

Don’t assume every homeowners policy contains identical Airbnb language.

But when you’re earning money by repeatedly providing accommodation to members of the public, the insurer may consider whether the claim arises from:

a business pursuit.

If it does, ordinary personal-liability protection may not operate the way you expected.


Example: The Staircase Injury

Suppose your home is listed for:

$250 per night.

A guest falls from a defective staircase.

The guest alleges that you:

Failed to maintain the stairs

and:

Failed to warn them about the hazard.

Potential damages could include:

Emergency treatment

Surgery

Physical therapy

Lost wages

and:

Legal damages.

Your first assumption might be:

“My homeowners policy has $500,000 of liability coverage.”

But the relevant question is:

Does that $500,000 apply to liability arising from paying short-term guests?

You need the answer before the accident.


Occasional Rental and Regular Airbnb Hosting May Be Treated Differently

This is an important distinction.

Imagine:

Homeowner A

Rents their home once per year during a major local sporting event.

Homeowner B

Rents the home:

150 nights per year.

Those aren’t necessarily identical insurance exposures.

Triple-I notes that some insurers may allow short-term rentals when they are occasional, potentially through an endorsement, while frequent rental activity may require a business or commercial insurance solution.

That’s why you should disclose:

How frequently you rent

How many nights

Whether you rent rooms or the entire property

and:

Whether you live there.


Don’t Hide Airbnb Activity From Your Insurer

This is one of the worst strategies.

Some homeowners worry:

“If I tell my insurer, my premium may increase.”

Maybe.

Or the insurer could:

Require an endorsement

Change coverage

Decline the exposure

or:

Recommend another product.

But hiding material changes in how the property is used can create much larger problems when you file a claim.

Insurance underwriting depends on accurate information about:

the risk being insured.

Tell the insurer how you’re actually using the property.


Airbnb’s Host Protection Is Not the Same as Homeowners Insurance

Airbnb currently provides hosts with its:

AirCover for Hosts

program.

Airbnb says AirCover includes $1 million in Host liability insurance, which can provide protection if a host is found legally responsible for a guest’s bodily injury or for damage or theft involving certain guest property during an Airbnb stay.

Airbnb also advertises Host damage protection.

But Airbnb specifically states that:

AirCover isn’t a substitute for homeowners or renters insurance.

That distinction is extremely important.


Platform Coverage Should Be a Layer—Not Your Entire Insurance Plan

Imagine your insurance strategy is:

“Airbnb covers everything.”

That’s risky.

Platform protection:

Has terms

Has exclusions

Has limits

Has eligibility requirements

and:

May not duplicate the protection available from a properly structured property policy.

Airbnb itself recommends reviewing your own insurance coverage because AirCover doesn’t replace personal insurance.

Treat platform protection as:

one layer of risk management.

Not:

the entire structure.


What About Vrbo?

The same principle applies regardless of platform.

Whether you’re using:

Airbnb

or:

Vrbo,

don’t assume the platform’s protections make your personal homeowners insurance irrelevant.

Read the platform’s current:

Host protection terms

Liability limits

Exclusions

and:

Claims procedures.

Then compare those with your own insurance.


Your Property Risk Doesn’t Stop at Guest Injuries

Short-term rentals create several categories of insurance exposure.

1. Guest Bodily Injury

Example:

A guest falls down stairs.

2. Guest Property Damage

Example:

A guest claims their laptop was damaged because of a condition at the property.

3. Damage to Your Home

Example:

A guest damages:

Walls

Furniture

Flooring

or:

Appliances.

4. Theft

Property disappears during or after a stay.

5. Fire

A guest accidentally causes a kitchen fire.

6. Water Damage

A guest leaves water running.

7. Loss of Rental Income

A covered loss makes the rental unavailable for weeks or months.

These aren’t necessarily handled by the same coverage.


Guest Injury Can Become the Most Expensive Risk

A damaged television might cost:

$1,000.

A damaged sofa:

$2,500.

A serious bodily injury lawsuit can potentially involve:

hundreds of thousands of dollars

or more.

That’s why hosts shouldn’t focus exclusively on:

property damage caused by guests.

Liability exposure can be much larger.


Swimming Pools Increase the Stakes

Suppose your Airbnb has a:

swimming pool.

Now consider:

Slips

Diving injuries

Children

Alcohol

Night swimming

and:

Unsupervised guests.

Pools already represent a significant liability exposure for ordinary homeowners.

Combining:

Pool + Paying Guests + Frequent Turnover

creates a risk that deserves a specific conversation with your insurer.

Don’t assume a generic short-term-rental endorsement automatically handles every pool-related exposure.


Hot Tubs Create Similar Problems

Vacation rentals often advertise:

private hot tubs.

But hot tubs create:

Slip-and-fall exposure

Burn risk

Sanitation issues

Electrical risk

and:

Potential child-safety concerns.

Tell the insurer about:

Pool

Hot tub

Trampoline

Dock

Boat access

and other potentially hazardous features.


Balconies and Decks Matter Too

A balcony that feels familiar to you may be unfamiliar to a guest arriving:

after dark.

Inspect:

Railings

Stairs

Deck boards

Lighting

and:

Handrails.

If you know something is defective:

repair it before hosting.

Insurance isn’t a substitute for maintaining a reasonably safe property.


Smoke and Carbon Monoxide Alarms

Guest safety should include functioning:

Smoke alarms

and:

Carbon monoxide alarms

where appropriate and legally required.

Requirements can vary by:

State

City

County

and:

Property type.

Short-term rental ordinances may impose additional safety rules.

Insurance doesn’t replace legal compliance.


Fire Extinguishers and Emergency Information

Consider providing clearly accessible:

Fire extinguishers

Emergency exits

Emergency contact information

and:

Property safety instructions.

Keep instructions simple.

Guests may never have entered the home before.

They won’t necessarily know:

where anything is.


Local Short-Term Rental Laws Matter

Insurance is only one piece of the puzzle.

Cities may regulate:

Licensing

Registration

Occupancy

Parking

Taxes

Safety equipment

Primary-residence requirements

and:

Maximum rental periods.

Rules can change rapidly.

Before listing a property, check:

state law

plus:

city/county rules.

A valid insurance policy doesn’t automatically make an illegal rental legal.


HOA and Condo Rules Matter Too

Suppose your insurer allows short-term rentals.

But your:

homeowners association

prohibits rentals shorter than:

30 days.

You still have a problem.

Condo and HOA owners should review:

CC&Rs

Bylaws

Rental restrictions

and:

Association insurance.

Short-term rental activity can create both:

insurance risk

and:

contractual risk.


What About Condo Hosts?

Condo owners face another layer.

You may have:

Association master policy

Personal condo policy

Platform host protection.

Those policies don’t necessarily cover the same things.

A paying guest could cause damage to:

Your unit

Common hallway

Elevator

Neighbouring unit

or:

Shared facilities.

Ask whether your personal condo policy permits:

short-term rental activity.

Don’t assume the association’s master policy solves the problem.


Renting One Bedroom Still Counts

Some hosts think:

“I’m not renting my house—only the spare room.”

But you’re still accepting payment for accommodation.

That can create insurance implications.

Tell the insurer whether you’re renting:

One bedroom

Basement apartment

Accessory dwelling unit

Guesthouse

or:

Entire property.

The correct insurance solution may differ.


What If You Live in the House?

Owner-occupied hosting can be different from renting an entire second home.

Imagine:

Scenario A

You live in the property and occasionally rent a bedroom.

Scenario B

You own a vacation property used exclusively for short-term rentals.

Scenario C

You operate five short-term rental properties.

These aren’t the same insurance risks.

Scenario C looks much more like:

a commercial hospitality business.

Don’t assume the same policy works for all three.


Landlord Insurance Isn’t Automatically Airbnb Insurance Either

Another misconception:

“I have landlord insurance, so I’m covered.”

Traditional landlord policies may be designed for:

long-term tenants.

A one-year lease creates a different occupancy pattern from:

new guests every three days.

If you’re converting a long-term rental into an Airbnb, tell the insurer.

Ask whether the existing landlord policy allows:

short-term vacation rental use.


What Type of Insurance Might a Host Need?

There isn’t one universal product.

Depending on your situation, possible solutions may include:

Home-Sharing Endorsement

For certain eligible short-term rental activity added to a personal policy.

Specialized Short-Term Rental Policy

Designed specifically for vacation rentals.

Landlord Policy With Appropriate Short-Term Rental Provisions

Where available.

Commercial Insurance

Potentially appropriate for more extensive rental businesses.

Umbrella Liability Coverage

Potentially providing additional liability protection, subject to underlying-policy requirements and exclusions.

Your insurer or licensed agent should determine which structure fits the exposure.


Don’t Assume an Umbrella Policy Fixes Everything

Suppose your homeowners policy excludes a particular Airbnb business claim.

You might think:

“My $2 million umbrella will cover it.”

Not necessarily.

Umbrella policies have:

Underlying-insurance requirements

Definitions

Exclusions

and:

Business limitations.

If the underlying exposure isn’t properly insured, your umbrella may not magically correct the problem.

Tell the umbrella insurer about your short-term rental too.


Ask About Commercial General Liability

If your rental activity is substantial enough to operate like a business, commercial liability coverage may become relevant.

A commercial policy may be structured around business exposures that a personal homeowners contract wasn’t designed to insure.

But don’t buy a generic commercial policy without professional advice either.

You need coverage that actually addresses:

short-term accommodation.


Loss of Rental Income Can Be Significant

Imagine your vacation rental earns:

$5,000 per month.

A covered fire makes it unusable for:

six months.

Potential lost revenue:

$30,000.

Your ordinary homeowners loss-of-use coverage is generally focused on additional living expenses associated with your residence—not necessarily business income from vacation guests.

Specialized short-term rental coverage may offer:

loss-of-rental-income protection,

subject to policy terms.

Ask specifically.


Homeowners Loss of Use and Rental Income Are Different

This distinction is easy to miss.

Loss of Use

Helps address qualifying additional living expenses when your insured residence becomes uninhabitable.

Business/Rental Income Coverage

May address qualifying income lost because an insured rental property can’t operate.

Those aren’t interchangeable.

If rental revenue matters financially, ask how it’s insured.


What About Guest-Caused Fire?

Imagine a guest:

leaves cooking unattended.

The kitchen catches fire.

Damage:

$80,000.

Will your homeowners policy pay?

Don’t guess.

The insurer may consider:

The policy wording

Short-term rental endorsement

Business exclusions

Occupancy

and:

Circumstances of the loss.

This is exactly the kind of scenario you should discuss before hosting.


What About Guest Theft?

Suppose after checkout you discover:

television missing.

Or:

jewelry missing.

The way theft is treated can depend on:

Who committed it

Whether the property was entrusted to them

Policy exclusions

and:

Platform protection.

Don’t assume ordinary homeowners theft coverage automatically treats guest theft like a burglary by a stranger.


What About Intentional Damage?

Guest deliberately damages:

Walls

Furniture

and:

Doors.

Intentional acts can be treated differently from accidental damage.

Platform host-damage programs may have their own rules.

Your personal policy may have exclusions that matter.

Again:

multiple insurance layers may be involved.


Keep Business and Personal Property Separate

If you’re operating a dedicated Airbnb, identify property used specifically for the rental.

Examples:

Guest furniture

Smart locks

Rental linens

Commercial cleaning equipment

Guest electronics

and:

Business supplies.

Personal homeowners policies can contain limits on:

business property.

A dedicated short-term rental policy may treat those assets differently.


Document the Property Before Every Guest

This doesn’t need to take hours.

Take timestamped photographs or video of:

Living room

Bedrooms

Kitchen

Bathrooms

Furniture

Television

Appliances

Doors

and:

High-value items.

For expensive or professionally operated rentals, more detailed digital documentation may be worthwhile.

Your goal is to establish:

pre-stay condition.


Document Safety Features Too

Keep records showing:

Smoke alarms

CO alarms

Fire extinguishers

Handrails

Pool barriers

Exterior lighting

and:

Other safety equipment

were installed and maintained.

This doesn’t eliminate liability.

But good maintenance and documentation are sensible risk-management practices.


Use Smart Locks Carefully

Smart locks can make short-term rentals easier to operate.

You can:

Issue temporary codes

Remove expired access

and:

Avoid physical-key duplication.

But maintain:

cybersecurity

and:

guest privacy.

Don’t install invasive surveillance devices in private spaces.

Platform rules and applicable privacy laws must be followed.


Exterior Security Cameras Need Care

Some hosts use cameras around:

Driveway

Exterior entrance

or:

Parking area.

Before doing so, check:

Platform policies

State privacy law

Local regulations

and:

Disclosure requirements.

Insurance risk management doesn’t justify violating guest privacy.


Keep Maintenance Records

Create a simple log.

DateItemAction
Jan. 10Smoke alarmsTested
Feb. 5Exterior stairsInspected
Mar. 1HandrailRepaired
Apr. 8Pool gateTested
May 14HVACServiced

After a serious injury, being able to show:

consistent property maintenance

may be valuable.


Don’t Ignore Guest Complaints

Suppose a guest messages:

“The second stair feels loose.”

Then you host:

seven more guests

without inspecting it.

Later someone falls.

That prior warning could become extremely important.

Treat safety complaints as:

maintenance alerts.

Investigate promptly.


Your Cleaning Team Can Help Spot Risks

Cleaners enter the property between guests.

Train them to report:

Loose railings

Broken furniture

Wet floors

Damaged electrical outlets

Missing smoke alarms

Cracked steps

and:

Other hazards.

A good turnover process isn’t only about:

clean sheets.

It can also be part of:

risk management.


Don’t Underestimate Slip-and-Fall Claims

A guest doesn’t need a spectacular accident to create a major liability claim.

Potential hazards include:

Wet tile

Loose rugs

Poor lighting

Uneven stairs

Ice

Broken pavement

and:

Unmarked elevation changes.

Walk through the property as if you’ve:

never seen it before.

Because your guest hasn’t.


What If the Guest Sues You?

If a covered liability claim results in a lawsuit, liability insurance can potentially provide:

Legal defense

and:

Covered settlements or judgments

subject to the contract and policy limits.

That’s one reason liability insurance can be more important than simply protecting furniture.

Legal defense itself can be expensive.


Is $1 Million Enough?

There’s no universal answer.

Airbnb currently advertises up to $1 million in Host liability insurance through AirCover for qualifying situations.

But a serious injury can potentially produce substantial damages.

Hosts should evaluate:

Personal assets

Property characteristics

Guest volume

Pool/hot-tub exposure

Business scale

and:

Available umbrella/commercial limits.

A licensed insurance professional can help assess appropriate limits.


Ask Your Insurer These 15 Questions

Before your first guest arrives, ask:

  1. Does my homeowners policy allow short-term rentals?
  2. How does the policy define business activity?
  3. Is occasional home sharing treated differently from regular hosting?
  4. Do I need a home-sharing endorsement?
  5. Would guest bodily injury be covered?
  6. What liability limit applies?
  7. Is guest-caused property damage covered?
  8. Is theft by a guest covered?
  9. Are intentional guest acts covered?
  10. Is loss of rental income covered?
  11. Does coverage apply while I’m away?
  12. Are pools or hot tubs covered?
  13. Does my umbrella policy permit short-term rental activity?
  14. Does platform insurance affect my coverage?
  15. At what point do I need commercial insurance?

Document the answers.


Give the Insurer Accurate Hosting Numbers

Don’t say:

“Occasionally.”

Instead say:

“Approximately 60 nights per year.”

Or:

“One bedroom, about two weekends per month.”

Or:

“The entire home approximately 150 nights annually.”

Specific information allows the insurer to assess the actual exposure.


The Cheapest Insurance Isn’t Always the Best Host Policy

Imagine:

Policy A — $1,600/year.

Policy B — $2,200/year.

Policy A looks better.

But then you discover Policy A:

excludes short-term rental activity.

Policy B specifically allows it.

You’re not comparing:

cheap vs. expensive insurance.

You’re comparing:

potentially relevant coverage vs. potentially irrelevant coverage.


Short-Term Rental Insurance Checklist for 2026

Before listing your property:

  1. Contact your homeowners insurer.
  2. Disclose short-term rental activity.
  3. Estimate annual rental nights.
  4. Explain whether you rent a room or entire home.
  5. Confirm whether you’re owner-occupied.
  6. Ask about business exclusions.
  7. Ask about a home-sharing endorsement.
  8. Compare specialized short-term rental insurance.
  9. Review Airbnb/Vrbo host protection.
  10. Don’t treat platform coverage as a homeowners-policy replacement.
  11. Check liability limits.
  12. Check guest-caused property damage.
  13. Check theft coverage.
  14. Check loss-of-rental-income coverage.
  15. Review your umbrella policy.
  16. Check pool/hot-tub restrictions.
  17. Check HOA/condo rules.
  18. Check local licensing laws.
  19. Install required smoke/CO alarms.
  20. Inspect stairs and handrails.
  21. Inspect balconies and decks.
  22. Maintain adequate exterior lighting.
  23. Document property condition.
  24. Maintain repair records.
  25. Investigate guest safety complaints promptly.
  26. Review coverage annually.

Frequently Asked Questions

Does homeowners insurance cover Airbnb rentals?

Not automatically. Standard homeowners insurance is primarily designed for personal residential use, and regular short-term rental activity can create business-related coverage issues. Triple-I recommends informing your insurer and determining whether an endorsement or specialized policy is needed.

Will homeowners insurance cover an Airbnb guest who gets injured?

Possibly, but you shouldn’t assume it will. Coverage depends on the policy, rental frequency, endorsements, exclusions and circumstances. Business exclusions can create a serious coverage gap.

Does Airbnb provide liability insurance?

Airbnb currently says AirCover for Hosts includes $1 million in Host liability insurance for qualifying claims.

Is AirCover a replacement for homeowners insurance?

No. Airbnb specifically says AirCover isn’t a substitute for homeowners or renters insurance.

Do I need special insurance if I rent my home only occasionally?

Possibly. Some insurers may allow occasional rentals or offer an endorsement, while regular hosting may require different coverage. Tell the insurer exactly how often you plan to rent.

What if I rent only one room?

You should still disclose it. Accepting payment from guests can introduce business-related exposure even if you remain in the home.

Does landlord insurance cover Airbnb?

Not necessarily. Traditional landlord policies may be designed for long-term tenants rather than frequent short-term guests. Confirm short-term rental use with the insurer.

Does homeowners insurance cover damage caused by Airbnb guests?

It depends. Standard policies may have restrictions involving business use, theft, intentional acts or property entrusted to others. Specialized coverage or platform protection may respond differently.

Should Airbnb hosts have umbrella insurance?

Potentially, but hosts must confirm that the umbrella policy permits the underlying short-term rental exposure. An umbrella isn’t automatically a workaround for exclusions in the underlying policy.

What is the biggest insurance risk for Airbnb hosts?

Serious guest bodily injury can create substantial liability exposure. Property damage is important, but a major injury claim can be financially much larger.


Final Thoughts

Turning your house into an Airbnb can feel simple.

Create the listing.

Upload photographs.

Set the nightly price.

Accept bookings.

But from an insurance perspective, something fundamental has changed:

Your private home may now also be generating business income from paying guests.

That matters.

Your ordinary homeowners policy may provide excellent personal-liability protection when:

a friend visits.

It doesn’t necessarily provide identical protection when:

a paying guest books your home online.

The NAIC warns that home-sharing can create coverage gaps because homeowners policies may restrict business-related losses.

Triple-I similarly recommends discussing short-term rental activity with your insurer and considering an endorsement or business policy depending on how frequently the property is rented.

And while Airbnb provides Host liability insurance through AirCover, Airbnb itself makes clear that AirCover:

doesn’t replace your own insurance.

So before accepting your next booking, ask your insurer one straightforward question:

“If my paying guest is seriously injured tomorrow, which policy protects me?”

If you can’t answer that confidently, your short-term rental insurance strategy isn’t finished.


Disclaimer

This article is for informational and educational purposes only and isn’t legal, financial, business, safety or insurance advice. Homeowners, landlord, commercial, umbrella and platform-provided insurance coverage varies by insurer, state, property, platform and policy wording. Short-term rental laws also vary by jurisdiction. Review your policies, platform terms and local requirements and speak with a licensed insurance professional before renting your property to paying guests.
Flood Insurance Beyond the NFIP: Why private flood insurance is becoming the better choice in Florida and the Carolinas.


Elevated coastal home in Florida protected by private flood insurance with floodwater surrounding the property after a hurricane.

Flooding remains one of the most expensive and common natural disasters in the United States. Coastal storms, hurricanes, heavy rainfall, and inland flooding can cause extensive property damage, often leaving homeowners with repair bills that reach tens or even hundreds of thousands of dollars.

Many homeowners assume their standard homeowners insurance policy covers flood damage. In most cases, it does not. Separate flood insurance is generally required to protect against damage caused by rising water.

For decades, the National Flood Insurance Program (NFIP) has been the primary source of residential flood insurance. However, private insurers have expanded their flood insurance offerings in recent years, giving homeowners additional options that may provide broader coverage, higher policy limits, or more flexible pricing depending on the property and insurer.

This guide explains how NFIP and private flood insurance differ and why many homeowners in Florida and the Carolinas are exploring private market alternatives.


Why Flood Insurance Matters

Floods can happen almost anywhere—not only in coastal communities.

Flooding may result from:

  • Hurricanes
  • Tropical storms
  • Heavy rainfall
  • Storm surge
  • Overflowing rivers
  • Flash floods
  • Drainage system failures
  • Urban flooding
  • Snowmelt in some regions

Even properties located outside officially designated high-risk flood zones can experience flood damage.

Because homeowners insurance generally excludes flood losses, separate flood insurance can play an important role in protecting both the structure and, depending on the policy, personal belongings.


Understanding the National Flood Insurance Program (NFIP)

The National Flood Insurance Program was established to improve access to flood insurance for property owners and to encourage sound floodplain management.

Participating communities adopt floodplain management standards, allowing eligible property owners to purchase NFIP flood insurance.

NFIP policies generally provide:

Building Coverage

May help cover damage to:

  • Foundation
  • Electrical systems
  • Plumbing
  • HVAC equipment
  • Water heaters
  • Permanently installed flooring
  • Built-in appliances
  • Structural components

Contents Coverage

Separate contents coverage may help protect:

  • Furniture
  • Clothing
  • Electronics
  • Personal belongings
  • Certain household items

Building and contents coverage are generally purchased separately under NFIP policies.


Why Flood Risk Is Growing in Florida and the Carolinas

Florida, North Carolina, and South Carolina regularly experience weather events capable of producing significant flooding.

Common causes include:

  • Atlantic hurricanes
  • Tropical storms
  • Coastal storm surge
  • Heavy seasonal rainfall
  • Inland river flooding
  • Urban drainage challenges
  • Rising sea levels affecting some coastal communities

As weather patterns evolve and development expands into flood-prone areas, many homeowners are reassessing their flood insurance needs.


Common Misconceptions About Flood Insurance

Many homeowners mistakenly believe:

“I’m not in a flood zone.”

Flooding can occur outside high-risk flood areas. Moderate- and low-risk areas may also experience damaging floods.


“My homeowners insurance covers floods.”

Standard homeowners insurance policies typically exclude flood damage caused by rising water.


“Federal disaster assistance will pay for everything.”

Disaster assistance may not be available after every flood event, and when available, it may not fully cover rebuilding costs or personal property losses.


Limitations of NFIP Coverage

The NFIP has helped millions of homeowners obtain flood insurance, but it may not meet every property’s needs.

Some limitations can include:

  • Coverage limits that may not fully protect higher-value homes.
  • Separate building and contents coverage selections.
  • Certain property types or improvements may have limited coverage.
  • Temporary living expenses are generally not included.
  • Waiting periods often apply before new coverage becomes effective, subject to certain exceptions.

Coverage details vary by policy and circumstances, so homeowners should review the official policy language carefully.


What Is Private Flood Insurance?

Private flood insurance is offered by insurance companies outside the NFIP.

These policies may provide additional flexibility depending on the insurer, including:

  • Higher coverage limits.
  • Broader protection.
  • Additional optional coverages.
  • Flexible deductibles.
  • Customized underwriting.
  • Digital claims services.

Availability varies by location, property characteristics, and insurer.


Why More Homeowners Are Considering Private Flood Insurance

Competition within the private insurance market has increased significantly over the past several years.

Some homeowners choose private flood insurance because it may offer:

  • More coverage choices.
  • Higher dwelling limits.
  • Coverage for additional living expenses (depending on the policy).
  • Broader protection for personal belongings.
  • Replacement cost options for eligible homes.
  • Streamlined online application processes.

Not every private policy offers all of these features, making policy comparison especially important.


NFIP vs. Private Flood Insurance

FeatureNFIPPrivate Flood Insurance
ProviderFederal programPrivate insurance companies
Coverage LimitsStandard program limitsMay offer higher limits, depending on insurer
Optional CoverageLimited optionsMay offer additional endorsements
PricingBased on program rules and property characteristicsVaries by insurer and underwriting
Temporary Living ExpensesGenerally not includedMay be available with some policies
Online Policy ManagementLimitedOften more extensive digital tools
CustomizationStandardizedGreater flexibility may be available

Advantages of Private Flood Insurance

Higher Coverage Limits

Owners of higher-value homes may find that private insurers offer coverage limits beyond those available through standard NFIP policies.


Broader Personal Property Protection

Some private policies may provide more comprehensive contents coverage or additional options for valuable personal property.


Additional Living Expenses

Certain private flood insurance policies may help cover temporary housing costs if the home becomes uninhabitable following a covered flood loss. This benefit is generally not included in standard NFIP residential policies.


Flexible Deductible Options

Many private insurers offer multiple deductible choices, allowing homeowners to balance premium costs with out-of-pocket expenses.


Modern Digital Experience

Private insurers often provide:

  • Mobile claims reporting.
  • Online policy management.
  • Digital document submission.
  • Faster communication.
  • Claim tracking through mobile apps.

These features can improve convenience throughout the claims process.


Is Private Flood Insurance Always Better?

Not necessarily.

The best choice depends on several factors, including:

  • Property value.
  • Flood risk.
  • Mortgage lender requirements.
  • Desired coverage limits.
  • Budget.
  • Available insurers in your area.

For some homeowners, the NFIP may remain the most appropriate option. Others may benefit from comparing private market offerings before making a decision.

When Private Flood Insurance May Be a Better Choice

Private flood insurance is not automatically the best option for every homeowner, but it may be worth considering in several situations.

1. Higher-Value Homes

If the cost to rebuild your home exceeds the coverage available through a standard NFIP policy, a private insurer may offer higher dwelling limits that better reflect your property’s replacement cost.


2. Valuable Personal Property

Homeowners with expensive furniture, electronics, artwork, or other high-value belongings may benefit from private policies that provide broader personal property coverage or higher coverage limits.


3. Need for Additional Living Expenses (ALE)

After a major flood, some homeowners may need temporary housing while repairs are completed.

Certain private flood insurance policies may include Additional Living Expenses (ALE) or Loss of Use coverage if the home becomes uninhabitable due to a covered flood event. Standard residential NFIP policies generally do not provide this benefit.


4. Flexible Deductible Options

Private insurers often allow homeowners to choose from several deductible amounts, making it easier to balance premium costs with potential out-of-pocket expenses after a claim.


5. Modern Claims Experience

Many private insurers offer:

  • Mobile claim reporting
  • Online policy management
  • Electronic document uploads
  • Digital payment options
  • Real-time claim status tracking

These features can improve convenience during the claims process.


Cost Comparison

Flood insurance premiums vary based on many factors, including:

  • Property location
  • Flood zone designation
  • Elevation
  • Construction type
  • Foundation design
  • Replacement cost
  • Deductible selected
  • Coverage amount
  • Claims history
  • Underwriting guidelines

Depending on the insurer and the property, a private policy may cost less, about the same, or more than an NFIP policy. Comparing quotes from multiple providers can help homeowners evaluate available options.


What Mortgage Lenders Require

If your property is located in a federally designated Special Flood Hazard Area and your mortgage is backed by a federally regulated or insured lender, flood insurance may be required.

Some lenders accept qualifying private flood insurance policies that meet applicable legal and regulatory requirements. Others may have additional documentation or underwriting requirements.

Before changing coverage, confirm with your mortgage lender that the proposed policy satisfies all applicable requirements.


How to Compare Flood Insurance Policies

When evaluating flood insurance options, consider more than just the premium.

Review:

Coverage Limits

Ensure the policy provides enough protection for both the structure and personal belongings.


Replacement Cost vs. Actual Cash Value

Understand how covered property will be valued after a loss. Some policies may pay replacement cost for eligible property, while others may apply depreciation.


Waiting Periods

Many flood insurance policies include a waiting period before coverage becomes effective, although exceptions may apply in certain situations.


Deductibles

Compare deductible options carefully. A lower premium may come with a higher deductible, increasing your out-of-pocket costs after a covered loss.


Exclusions

Review what is not covered, such as certain outdoor property, landscaping, or specific improvements, depending on the policy.


Claims Process

Ask how claims are reported, documented, and settled. Understanding the insurer’s process before purchasing a policy can help set expectations after a loss.


Tips for Homeowners in Florida and the Carolinas

  • Review your flood risk every year.
  • Don’t rely solely on FEMA flood maps; local conditions can change over time.
  • Keep a current home inventory with photos and receipts.
  • Maintain digital copies of insurance documents.
  • Consider flood mitigation measures where appropriate.
  • Reassess your coverage after major home renovations or additions.
  • Compare quotes from multiple insurers before each renewal.

Common Mistakes to Avoid

Assuming Flood Insurance Is Included

Standard homeowners insurance policies generally do not cover flood damage caused by rising water.


Buying Coverage Only After a Storm Is Forecast

Flood insurance usually includes a waiting period before coverage begins, so purchasing a policy after a storm is approaching may not provide immediate protection.


Underestimating Rebuilding Costs

Construction costs can change over time. Review your dwelling coverage periodically to help ensure it reflects current rebuilding estimates.


Forgetting Personal Property Coverage

Some flood insurance policies require separate contents coverage or offer different limits for personal belongings.


Choosing the Cheapest Policy Without Comparing Coverage

A lower premium may come with lower limits, higher deductibles, or fewer covered benefits. Compare the full policy, not just the price.


Frequently Asked Questions

Is private flood insurance accepted by mortgage lenders?

Many lenders accept qualifying private flood insurance policies that meet applicable legal requirements. Check with your lender before changing coverage.


Can I switch from the NFIP to a private flood insurance policy?

In many situations, homeowners can switch if they find a policy that better meets their needs and satisfies any lender requirements. Review the details carefully before making changes.


Does private flood insurance always cost less?

No. Premiums depend on many factors, including the property’s characteristics, flood risk, insurer, and selected coverage. Comparing quotes is the best way to evaluate available options.


Does flood insurance cover hurricane damage?

Flood insurance generally covers flood damage caused by rising water. Wind damage from a hurricane is typically addressed under a homeowners insurance policy, subject to its terms and conditions. Depending on the event, separate claims may be required for wind and flood damage.


Should homeowners outside high-risk flood zones consider flood insurance?

Flooding can occur in moderate- and lower-risk areas. Homeowners should evaluate their property’s location, local flood history, and financial ability to recover from a flood loss when deciding whether coverage is appropriate.


Final Thoughts

Flood insurance remains an important part of financial protection for homeowners in Florida, the Carolinas, and many other parts of the United States. While the National Flood Insurance Program continues to serve millions of property owners, the growth of private flood insurance has expanded the range of available options.

For some homeowners, private policies may offer higher coverage limits, broader benefits, or additional features such as temporary living expense coverage. Others may find that an NFIP policy better suits their needs or satisfies lender requirements.

Before purchasing or changing coverage, compare policy terms, coverage limits, deductibles, exclusions, and claims processes carefully. Taking the time to understand your options can help you choose coverage that aligns with your property’s risks and your financial goals.

Final Expense (Burial) Insurance: A sensitive guide for seniors on avoiding “Pre-need” funeral scams.


Senior couple meeting with a licensed insurance advisor to discuss final expense insurance and safe funeral planning.

Planning for end-of-life expenses can be a difficult topic, but it is an important part of financial planning. Many people purchase final expense insurance to help reduce the financial burden on loved ones by providing funds that can be used for funeral costs, outstanding bills, or other eligible expenses after death.

Unfortunately, older adults are also frequent targets of misleading sales tactics and fraudulent schemes involving funeral planning and so-called “pre-need” arrangements. Understanding how final expense insurance works—and how it differs from funeral contracts—can help families make informed decisions and reduce the risk of financial loss.

This guide explains final expense insurance, pre-need funeral plans, common scam warning signs, and practical steps seniors can take to protect themselves.


What Is Final Expense Insurance?

Final expense insurance is a type of permanent life insurance designed to provide a relatively modest death benefit that beneficiaries can use for end-of-life costs.

Funds may be used for expenses such as:

  • Funeral services
  • Burial or cremation costs
  • Cemetery expenses
  • Outstanding medical bills
  • Small debts
  • Legal or administrative expenses
  • Household bills during the transition period

Unlike pre-need funeral contracts, the benefit is generally paid to the named beneficiary, who can decide how the money is used according to the policy terms and applicable law.


How Final Expense Insurance Works

Most final expense policies:

  • Provide permanent coverage as long as required premiums are paid.
  • Offer smaller coverage amounts than many traditional life insurance policies.
  • Are often designed with simplified underwriting.
  • May not require a medical examination, depending on the insurer and policy.
  • Build no investment portfolio, though some policies may accumulate limited cash value over time.

Coverage amounts vary by insurer and applicant eligibility.


Who May Benefit from Final Expense Insurance?

Final expense insurance may be appropriate for:

  • Retirees.
  • Older adults without existing life insurance.
  • Individuals seeking modest coverage for funeral expenses.
  • People who want to reduce the financial burden on family members.
  • Those looking for simplified underwriting options.

Every person’s financial needs are different, so it is important to evaluate whether this type of coverage fits your circumstances.


What Is a Pre-Need Funeral Plan?

A pre-need funeral plan is generally an agreement made directly with a funeral home or funeral service provider.

These arrangements often allow individuals to preselect funeral services and, in some cases, prepay for certain items.

Depending on the contract, a pre-need arrangement may include:

  • Funeral service planning.
  • Burial or cremation selections.
  • Casket or urn choices.
  • Cemetery arrangements.
  • Memorial service preferences.

Terms, guarantees, refund policies, and transfer options vary by provider and state law.


Final Expense Insurance vs. Pre-Need Funeral Plans

Although both involve planning for funeral expenses, they work differently.

Final Expense InsurancePre-Need Funeral Plan
Life insurance policyContract with a funeral provider
Benefit paid to beneficiaryServices arranged through provider
Money may be used for various eligible expensesTypically focused on funeral-related services
Choice of funeral provider remains flexibleMay be tied to the contracting provider
Coverage continues according to policy termsContract terms vary

Understanding these differences can help families choose the approach that best meets their needs.


Why Seniors Are Often Targeted

Scammers may focus on older adults because they know many seniors are planning for retirement, healthcare, or end-of-life expenses.

Common tactics include:

  • High-pressure sales presentations.
  • False urgency.
  • Misleading promises.
  • Requests for immediate payment.
  • Confusing contract language.
  • Claims of “limited-time” offers.
  • Impersonating trusted organizations.

These tactics do not represent the practices of reputable insurance companies or licensed funeral providers.


Common Funeral-Related Scams

Fake Insurance Representatives

Fraudsters may falsely claim to represent well-known insurance companies and request personal information or upfront payments.

Always verify the representative’s identity before providing sensitive information.


High-Pressure Sales Tactics

Be cautious if someone insists you must:

  • Buy immediately.
  • Sign documents without reviewing them.
  • Avoid discussing the purchase with family members.
  • Pay unusually large deposits.

Legitimate providers generally allow time to review policy documents and ask questions.


Guaranteed Acceptance Claims Without Details

While some policies offer simplified underwriting or guaranteed issue coverage, reputable companies clearly explain eligibility, waiting periods, premiums, and policy terms.

Avoid offers that promise unrealistic benefits without providing written documentation.


Requests for Large Cash Payments

Be cautious when asked to pay substantial amounts in cash without clear receipts, contracts, or supporting documentation.


Fake Government Affiliation

Some scams falsely imply they are connected to government agencies or Medicare.

Government programs generally do not endorse specific funeral providers or private insurance companies.


Warning Signs of a Potential Scam

Watch for these red flags:

  • Pressure to “act today.”
  • Refusal to provide written information.
  • Unclear refund policies.
  • Missing licensing information.
  • Requests for unusual payment methods.
  • Guarantees that sound too good to be true.
  • Difficulty answering basic questions.
  • Contracts that cannot be reviewed before signing.

If something feels suspicious, take additional time to verify the information.


How Seniors Can Protect Themselves

Simple precautions can reduce the risk of fraud.

Compare Multiple Companies

Request quotes from several insurers or providers before making a decision.


Verify Licensing

Confirm that insurance agents and companies are properly licensed in your state.


Read Every Document Carefully

Review policy terms, exclusions, waiting periods, cancellation rights, and beneficiary information before signing.


Discuss Decisions with Family

A trusted family member or financial professional may help identify concerns or clarify unfamiliar contract language.


Never Feel Pressured

Legitimate providers understand that purchasing insurance is an important financial decision and generally allow time for thoughtful review.


Questions to Ask Before Buying

Before purchasing a final expense policy or signing a funeral contract, consider asking:

  • What exactly is covered?
  • Are there waiting periods?
  • Who receives the benefit?
  • Can beneficiaries choose any funeral home?
  • Are premiums guaranteed?
  • Is the policy renewable?
  • Are there exclusions?
  • What happens if payments stop?
  • Is the contract transferable?
  • What is the cancellation policy?

Understanding these details can help prevent misunderstandings later.

Choosing a Legitimate Final Expense Insurance Company

Selecting a reputable insurance company is just as important as choosing the right policy. A financially stable insurer with a strong customer service record can provide greater confidence that beneficiaries will receive the policy benefits according to the contract.

When evaluating insurers, consider:

  • Financial strength ratings from recognized rating agencies.
  • State licensing status.
  • Years in business.
  • Customer service reputation.
  • Clear policy documentation.
  • Straightforward application process.
  • Transparent premium information.
  • Availability of licensed customer support.

Take time to compare more than one company before making a decision.


Final Expense Insurance vs. Pre-Need Funeral Contracts

Both options help prepare for future funeral costs, but they serve different purposes.

FeatureFinal Expense InsurancePre-Need Funeral Contract
TypePermanent life insurance policyFuneral planning agreement
Benefit RecipientNamed beneficiaryFuneral provider under the contract
FlexibilityBeneficiaries generally decide how funds are usedServices are typically tied to the contract
Provider ChoiceFuneral home can usually be selected laterOften linked to the contracted funeral home
Use of FundsFuneral costs and other eligible expensesFuneral services specified in the agreement

Some families choose one option, while others use both as part of a broader financial plan.


Should You Buy Final Expense Insurance or a Pre-Need Plan?

The answer depends on your priorities.

A final expense insurance policy may be more suitable if you:

  • Want your family to decide how the benefit is used.
  • Prefer flexibility in choosing a funeral provider.
  • Wish to leave funds for other final expenses, such as medical bills or small debts.
  • Want coverage that is not tied to a specific funeral home.

A pre-need funeral contract may appeal to individuals who:

  • Want to prearrange specific funeral services.
  • Prefer documenting personal funeral preferences in advance.
  • Feel comfortable working with a particular funeral provider after reviewing the contract carefully.

Some families choose to combine both approaches.


Common Mistakes to Avoid

Buying Without Comparing Policies

Coverage amounts, waiting periods, premiums, and policy features differ among insurers. Comparing multiple options can help you make a more informed decision.


Naming the Wrong Beneficiary

Review your beneficiary designation regularly, especially after major life events such as marriage, divorce, or the death of a previously named beneficiary.


Overlooking Waiting Periods

Some guaranteed issue or simplified issue policies include waiting periods before the full death benefit becomes payable for certain causes of death. Read the policy carefully so you understand how coverage works.


Purchasing More Coverage Than Needed

Final expense insurance is intended to help with end-of-life expenses. Consider your financial situation and existing life insurance before choosing a coverage amount.


Ignoring Policy Reviews

Your financial needs may change over time. Review your life insurance coverage periodically to determine whether it still aligns with your goals.


Additional Planning Tips

Final expense insurance is only one part of end-of-life planning. You may also wish to:

  • Keep important legal documents organized.
  • Inform trusted family members where insurance policies are stored.
  • Review beneficiary information regularly.
  • Maintain a list of financial accounts and key contacts.
  • Discuss funeral preferences with family members if you are comfortable doing so.
  • Update your estate planning documents when appropriate.

Organized planning can reduce stress for loved ones during a difficult time.


Frequently Asked Questions

Is final expense insurance the same as life insurance?

Final expense insurance is generally a type of permanent life insurance designed to provide a smaller death benefit intended to help cover end-of-life expenses.


Does the beneficiary have to spend the money on funeral costs?

In many cases, the beneficiary receives the insurance proceeds and may use them according to the policy terms and applicable law. Funds are often used for funeral expenses, but they may also help cover other eligible financial obligations.


Can I buy final expense insurance without a medical exam?

Some insurers offer simplified issue or guaranteed issue policies that may not require a medical examination. Eligibility requirements, waiting periods, and premiums vary by insurer and policy.


How much coverage do I need?

Coverage needs depend on your expected funeral costs, outstanding obligations, and any other financial resources available to your family. Consider reviewing your needs with a licensed insurance professional.


How can I avoid funeral scams?

  • Work with licensed insurance agents and reputable funeral providers.
  • Read all contracts before signing.
  • Ask questions about costs, refund policies, and cancellation rights.
  • Compare multiple providers.
  • Discuss major financial decisions with trusted family members or advisors.
  • Never feel pressured to make an immediate purchase.

Final Thoughts

Planning ahead for final expenses can provide financial relief and peace of mind for both you and your loved ones. Final expense insurance offers a flexible way to help cover funeral costs and other end-of-life expenses, while pre-need funeral contracts allow individuals to arrange specific funeral services in advance.

Whichever option you choose, take the time to compare providers, understand the policy or contract, verify licensing, and avoid high-pressure sales tactics. Careful planning and informed decision-making can help ensure your wishes are respected while reducing the financial burden on those you leave behind.

Life Insurance for High-Risk Occupations: How pilots, divers, and high-rise construction workers can get standard rates.

Pilot, commercial diver and high-rise construction worker representing life insurance for high-risk occupations.

Introduction

You’re healthy.

You don’t smoke.

Your blood pressure is excellent.

You exercise regularly.

You expect an attractive life-insurance rate.

Then the application asks:

What do you do for a living?

You answer:

Commercial pilot.

Or:

Commercial diver.

Or:

High-rise steelworker.

Suddenly the underwriting process can become more complicated.

Life insurers don’t assess only:

your health.

They can also consider:

what you do for work.

Sun Life’s 2026 Canadian life-insurance guidance specifically identifies occupation as a pricing factor and notes that higher-risk jobs, including pilots, can result in higher premiums.

But here’s the important correction to the title:

Working in a high-risk occupation does not automatically prevent you from getting standard life-insurance rates.

Nor is there a trick that guarantees standard rates.

The outcome depends on the:

Exact job

Duties

Training

Experience

Safety environment

Frequency of hazardous work

Type of aviation or diving

Depth or altitude exposure

and:

Insurer’s underwriting guidelines.

One current Canadian insurer’s underwriting guide says most occupations are accepted at standard rates, while certain higher-risk occupations may receive additional ratings.

The key isn’t to hide the dangerous part of your job.

It’s to:

help the underwriter understand your actual risk accurately.


What Does “Standard Rate” Mean?

Life-insurance applicants are commonly placed into underwriting classifications.

The terminology differs between insurers, but broadly you may encounter:

Preferred

A particularly favourable classification for applicants meeting stricter health and lifestyle criteria.

Standard

The insurer accepts you at its ordinary rate for the relevant age/product/profile.

Rated

The insurer accepts you but charges:

an additional premium

because of increased risk.

Declined

The insurer isn’t prepared to offer the requested coverage under its current underwriting rules.


High-Risk Occupation Does Not Equal Automatic Decline

This distinction is essential.

Some people assume:

“I’m a pilot, so life insurance will be extremely expensive.”

Or:

“I’m a commercial diver, so nobody will insure me.”

Neither conclusion is universally correct.

Underwriters don’t necessarily evaluate:

an occupation title alone.

They want to understand:

what you actually do.

Sun Life’s field-underwriting guidance says most occupations are accepted at standard rates, while certain occupations representing higher risk may receive additional ratings.

That means:

job details matter.


Why Occupation Matters to Life Insurers

Life insurance underwriting evaluates:

mortality risk.

Canada’s Financial Consumer Agency explains that insurers assess the risk of insuring an applicant and use underwriting to determine:

Eligibility

Amount of coverage

Possible exclusions

and:

Premium.

For life insurance, insurers typically evaluate factors such as:

Age

Health

Smoking status

Medical history

Lifestyle

and:

Occupation.

If your job exposes you to a greater probability of fatal injury, the insurer may want additional information.


Three Workers With the Same Job Title Can Be Different Risks

Consider three people who all describe themselves as:

“construction workers.”

Worker A spends most days:

operating equipment at ground level.

Worker B regularly works:

15 floors above ground.

Worker C erects structural steel:

hundreds of feet above ground.

An insurance application that asks only:

“Occupation: Construction”

doesn’t tell the underwriter enough.

Similarly:

“Pilot”

could mean:

Major-airline captain

Commercial charter pilot

Flight instructor

Agricultural pilot

Helicopter pilot

or:

Experimental test pilot.

Those aren’t necessarily equivalent underwriting risks.


The Same Is True for Divers

“Diver” could describe:

recreational scuba diver

who makes a handful of vacation dives each year.

Or:

professional instructor.

Or:

commercial diver.

Or:

deep-sea industrial diver.

The underwriting outcome can be dramatically different.

That’s why:

specificity matters.


How High-Risk Occupations Can Affect Your Premium

An insurer may handle occupational risk in several ways.

Depending on the insurer and circumstances, the applicant could receive:

Standard pricing

Preferred pricing if otherwise eligible

A flat extra premium

A percentage/table rating

An exclusion where contract/product rules allow

or:

A decline.

The treatment isn’t standardized across every Canadian insurer.


What Is a Flat Extra?

A flat extra is an additional premium charged because of a specific increased risk.

For example, Sun Life’s current field-underwriting guide says certain higher-risk occupations may receive a permanent flat extra of approximately:

$2.50 to $7.50 per $1,000

of life-insurance coverage.

That is an insurer-specific underwriting range—not an industry-wide rule.


Why Flat Extras Can Become Expensive

Suppose an insurer hypothetically adds:

$2.50 per $1,000

for occupational risk.

On:

$500,000

of coverage:

500 × $2.50 =

$1,250 additional annual premium.

At:

$5 per $1,000,

the extra becomes:

$2,500 annually.

That’s why finding an insurer whose underwriting approach fits your actual occupational profile can matter enormously.


Don’t Assume Every Insurer Will Reach the Same Decision

Life insurers maintain different:

Underwriting manuals

Risk tolerances

Reinsurance arrangements

and:

Occupational classifications.

One insurer might offer:

standard.

Another could offer:

standard + flat extra.

Another might request additional evidence.

And another might:

decline.

That’s why high-risk applicants shouldn’t necessarily treat one insurer’s decision as:

the final word on the market.


1. Life Insurance for Pilots

Pilots are a classic example of why underwriting needs detail.

An insurer may want to know:

Type of aircraft

Professional vs recreational flying

Commercial or private

Fixed-wing vs helicopter

Annual flight hours

Total experience

Routes

Purpose of flights

Qualifications

Accident history

and:

Future aviation plans.

Manulife’s insurance application materials, for example, specifically ask whether applicants intend to pilot an aircraft and request further details about hazardous activities.


Airline Pilot vs. Private Pilot

These aren’t necessarily treated the same.

Imagine:

Pilot A

Major commercial airline
Extensive flight experience
Highly regulated operation
Modern commercial aircraft
Established routes

versus:

Pilot B

Recently licensed private pilot
Small aircraft
Frequent recreational flying
Limited total flight hours

The word:

“pilot”

appears on both applications.

But their:

risk profiles can differ.


Commercial Airline Pilots May Have Better Options Than They Expect

People sometimes assume airline pilots automatically receive:

occupational ratings.

That isn’t necessarily true.

Experienced pilots working in highly regulated commercial operations may be viewed differently from applicants involved in:

Experimental aviation

Aerobatics

Agricultural aviation

Bush flying

or:

Other higher-risk aviation activities.

The insurer’s current underwriting guidelines determine the outcome.


How Pilots Can Improve Their Underwriting Presentation

Provide accurate details upfront.

Useful information may include:

Licence type

Years of experience

Total flight hours

Annual flight hours

Aircraft type

Employer/operator

Nature of flying

Geographic routes

Commercial vs private activity

Accident history

Aviation violations

and:

Future aviation intentions.

Don’t simply write:

“Pilot.”


Example

Consider:

Applicant A

Age: 38
Non-smoker
Healthy
Occupation: Commercial airline captain
Total flight experience: substantial
Regular scheduled passenger operations

versus:

Applicant B

Age: 38
Non-smoker
Healthy
Occupation: Pilot
Regular experimental-aircraft activity

Even though their medical profiles are identical:

occupational underwriting could differ substantially.


2. Life Insurance for Divers

Diving is another area where:

depth and type of activity matter.

Sun Life’s underwriting materials distinguish ordinary recreational scuba diving from more hazardous diving activity.

Its term underwriting guidance identifies recreational scuba diving up to and including:

120 feet

as potentially compatible with favourable underwriting criteria, while other rateable hazardous activities may prevent applicants from qualifying for those classifications.

That’s important because:

not every diver is automatically high risk.


Recreational Diver vs. Commercial Diver

Consider:

Diver A

Recreational scuba
20 dives annually
Moderate depths
Certified
Buddy system
No cave diving
No technical diving

versus:

Diver B

Commercial industrial diver
Underwater construction
Deep-water work
Frequent dives
Hazardous environments

Those risks aren’t comparable.


Commercial Diving Can Receive Much More Scrutiny

Sun Life’s current field-underwriting guide identifies:

military or commercial experimental/deep-sea divers

among higher-risk occupational categories and specifically lists commercial divers at depths of:

150 feet and deeper

among especially difficult risks.

This doesn’t mean every commercial diver receives the same outcome.

But it demonstrates how important:

depth and work type

can be.


What Divers Should Be Prepared to Disclose

An insurer may ask about:

Maximum depth

Average depth

Number of dives annually

Commercial vs recreational diving

Certification

Diving location

Solo vs buddy diving

Cave diving

Wreck penetration

Ice diving

Technical diving

Mixed-gas diving

Decompression diving

and:

Previous diving accidents.


Don’t Understate Depth

Suppose your typical dive is:

60 feet.

But occasionally your commercial work reaches:

170 feet.

Writing:

“Usually 60 feet”

without disclosing deeper work could materially misrepresent the risk.

Use:

accurate maximum exposure

when the application asks for it.


Certification Can Help Explain the Risk

If applicable, document professional credentials and training.

Depending on the occupation, this might include:

Commercial-diving certification

Scuba certification level

Safety training

Employer-required qualifications

and:

Emergency-response training.

Certification doesn’t guarantee standard rates.

But it helps the underwriter understand that the applicant isn’t:

an inexperienced worker performing hazardous activities without formal training.


3. Life Insurance for High-Rise Construction Workers

Construction covers an enormous range of occupations.

Examples include:

Carpenters

Electricians

Crane operators

Roofers

Steelworkers

Ironworkers

Glaziers

and:

High-rise maintenance workers.

The insurer may care much more about:

what you actually do

than the broad label:

“construction.”


Height Exposure Matters

Consider:

Construction Worker A

Interior finishing
Mostly ground-level work

Construction Worker B

Roof installation
Regular elevated work

Construction Worker C

Structural steel erection
High-rise projects
Regular substantial height exposure

These can produce different underwriting questions.

Sun Life’s field-underwriting guidance specifically identifies:

bridge and steel-erection workers

among occupational risks likely to require additional underwriting consideration.


High-Rise Doesn’t Automatically Mean Uninsurable

This needs emphasis.

Working:

30 floors above ground

doesn’t automatically mean:

“No life insurance.”

The insurer may examine:

Exact trade

Percentage of time at height

Maximum working height

Fall-protection systems

Training

Supervisory vs hands-on role

Employer safety standards

and:

Accident history.


Example: High-Rise Electrician

Suppose you’re an electrician working on:

high-rise residential projects.

But:

90% of your work

takes place inside completed or enclosed floors.

Your actual exposure may be very different from a structural ironworker who spends:

most working hours

on exposed steel.

Writing simply:

“High-rise construction”

could cause the underwriter to assume a risk that doesn’t accurately reflect your duties.


Describe Your Job Precisely

Instead of:

“Construction worker”

consider an accurate description such as:

“Licensed commercial electrician; approximately 90% interior work; occasional elevated work using engineered platforms and employer-required fall protection.”

Only provide details that are:

true.

The goal isn’t to make the occupation sound safer.

It’s to make it:

accurate.


Can High-Risk Workers Actually Get Standard Rates?

Yes:

some can.

Sun Life’s underwriting guidance explicitly says:

most occupations are accepted at standard rates.

But standard pricing isn’t guaranteed merely because someone is:

Healthy

Experienced

or:

Safety trained.

The insurer still evaluates the actual exposure.


The Biggest Mistake: Applying to the Wrong Insurer First

Suppose:

Insurer A

has conservative underwriting for commercial diving.

Insurer B

has more favourable guidelines for your particular diving profile.

Submitting blindly to Insurer A could result in:

a substantial rating.

This is why applicants with unusual occupational risks may benefit from an advisor or broker familiar with:

impaired-risk and occupational underwriting.


Consider Preliminary Underwriting

For complicated cases, it may be useful to investigate likely underwriting treatment before submitting a full formal application.

Sun Life currently describes preliminary underwriting assessments for certain clients with:

Significant health conditions

Hazardous sports

or:

Hazardous professions.

Availability depends on insurer and distribution channel.


Why Preliminary Assessment Can Help

Imagine you’re seeking:

$1 million

of term life insurance.

You are:

a commercial diver.

Instead of blindly sending full applications to several insurers, an experienced advisor may be able to present an anonymized or preliminary profile to appropriate underwriting channels.

The objective is to learn:

which insurers may view the risk most favourably.

That can potentially reduce unnecessary formal applications.


Your Underwriting “Risk Resume”

High-risk workers can prepare a concise occupational summary.

Think of it as:

a risk resume.

It could include:

Job title

Exact duties

Employer/industry

What kind of operation?

Experience

Years doing the job.

Training

Relevant certifications.

Exposure

How often you perform hazardous duties.

Maximum exposure

Maximum depth, height or aviation activity.

Safety procedures

Relevant protective systems.

Accident history

Accurate history of occupational incidents.

Future plans

Expected changes in duties.


Example: Pilot Risk Resume

Occupation: Commercial airline pilot

Experience: 14 years

Aircraft: Commercial passenger jets

Flying: Scheduled airline operations

Annual hours: Approximately 700

International routes: Yes

Private aviation: None

Aerobatics: None

Experimental aircraft: None

Accidents: None

That’s far more useful to an underwriter than:

“Pilot — 14 years.”


Example: Commercial Diver Risk Resume

Occupation: Commercial diver

Experience: 9 years

Typical depth: 40–80 feet

Maximum depth: 110 feet

Technical/cave diving: None

Employer: Established commercial contractor

Certification: Current professional certification

Diving frequency: Approximately X dives annually

Accident history: None

Again:

only provide information that is true.


Example: High-Rise Worker Risk Resume

Occupation: High-rise electrician

Experience: 11 years

Primary duties: Interior electrical installation

Time at exposed height: Limited

Fall protection: Employer-required engineered systems

Training: Current workplace safety/fall-protection training

Structural steel work: None

Accident history: None

The insurer can now evaluate:

the real exposure.


Experience Can Matter

Imagine two people performing the same hazardous activity.

Worker A:

6 months experience.

Worker B:

18 years experience.

Worker B may have:

More training

Established procedures

and:

Demonstrated experience.

But don’t assume experience automatically eliminates the occupational rating.

An insurer could still consider the activity inherently hazardous.


Safety Training Helps Tell the Story—but Doesn’t Guarantee a Discount

A common mistake is:

“I have safety certification, so I should get standard rates.”

Not necessarily.

Training can help the underwriter understand:

how the risk is managed.

But it doesn’t remove:

the underlying occupational exposure.

A commercial diver at substantial depth remains exposed to diving hazards even with excellent training.


Your Health Still Matters

Occupation is only:

one part of underwriting.

A high-rise worker who is:

Young

Healthy

Non-smoking

and has:

Excellent medical results

could still have favourable underlying medical underwriting.

The occupational assessment can then be considered separately.

Sun Life’s 2026 consumer guidance says age, health, smoking, lifestyle, occupation, coverage amount and term length can all influence life-insurance premiums.


Preferred Rates May Be Harder to Obtain

Standard and preferred aren’t the same.

An applicant might be:

insurable

but not qualify for:

preferred pricing.

Sun Life’s term underwriting material, for example, indicates that preferred classifications require no rateable occupation and no rateable hazardous aviation or avocation exposure.

So a high-risk worker’s realistic goal may sometimes be:

standard rather than preferred.


Don’t Confuse Occupation With Hobby Risk

Suppose you’re:

an accountant.

But every weekend you:

skydive.

Your occupation is low risk.

Your:

avocation

isn’t.

Conversely, you could be:

a high-rise construction worker

who spends weekends:

reading and gardening.

Underwriters can examine:

both occupational and recreational risks.


Pilots Can Have Both Occupational and Avocational Aviation Risk

Suppose you’re a:

commercial airline pilot

who also flies:

experimental aircraft recreationally.

The insurer may evaluate those separately.

Your commercial aviation could be acceptable at one classification while the recreational activity introduces:

additional risk.

Disclose both.


Divers Can Have the Same Issue

A professional diver may also participate in:

Cave diving

Deep wreck diving

or:

Technical diving

recreationally.

The insurer may consider:

occupational diving

and:

avocational diving

separately.

Don’t assume your employer’s safety record makes unrelated recreational activity irrelevant.


Never Hide Your Occupation

This is perhaps the most important advice in the article.

Don’t write:

“Engineer”

when your actual work includes:

offshore high-risk operations

simply because your formal job title is engineer.

Don’t write:

“Transportation”

instead of:

pilot.

And don’t describe commercial diving as:

“Marine services.”

Canada’s Financial Consumer Agency says applicants should answer insurance questions completely and honestly; inaccurate or incomplete information can lead to cancellation or refusal of a future claim.


Don’t Try to “Game” the Application

The objective isn’t:

finding wording that avoids triggering underwriting questions.

It’s:

accurate risk classification.

An apparently cheaper policy obtained through material misrepresentation isn’t:

a bargain.

It can create serious problems when your family eventually needs the coverage.


Medical Exam vs. Occupational Questionnaire

High-risk workers may receive:

ordinary medical underwriting

plus:

an occupational questionnaire.

The questionnaire could request:

Exact duties

Hours

Training

Safety procedures

Depth

Height

Flight hours

or:

Type of aircraft.

That doesn’t automatically mean you’re being declined.

It means:

the insurer needs more information.


A Longer Underwriting Process Isn’t Necessarily Bad

Some applicants prefer:

instant approval.

But for unusual occupational risks, automated underwriting may not always capture the full story.

A human underwriter may sometimes be useful because your case can be evaluated based on:

detailed circumstances.

Sun Life notes that underwriting can take anywhere from hours or days to weeks or months depending on the product and complexity.


A Good Cover Letter Can Help Complex Cases

For complicated underwriting cases, additional context can be valuable.

Sun Life’s underwriting guidance specifically discusses using customized cover letters when applications don’t capture information critical to underwriting, including:

high-risk activities such as scuba diving.

A useful cover letter might explain:

Exact occupational duties

Experience

Training

Risk exposure

and:

Why the broad job title doesn’t tell the complete story.


Standard Rates Aren’t Always the Best Possible Outcome

Suppose:

Insurer A

offers standard.

Insurer B

offers preferred.

Insurer C

offers standard plus a flat extra.

Clearly:

Insurer B

may look best on price.

But you still need to compare:

Policy term

Renewability

Conversion rights

Coverage amount

Financial strength

Contract wording

and:

Premium.

Don’t choose based solely on:

underwriting label.


A Flat Extra Isn’t Automatically a Bad Deal

Imagine an insurer offers:

standard medical rate

plus:

occupational flat extra.

That may still provide excellent protection.

The real comparison should be:

final premium + policy quality.

A policy with an occupational rating can still be more attractive than another insurer’s supposedly “standard” product if the overall pricing or contract is better.


Ask Whether the Occupational Rating Can Be Reconsidered

Occupations change.

Suppose you’re currently:

a commercial diver.

Five years later, you become:

an operations manager

and no longer dive.

Or you’re a:

structural ironworker

who becomes:

a project supervisor.

Ask whether the insurer permits:

reconsideration of an occupational rating.

Policies and insurer practices differ.

Don’t assume the extra premium must remain forever.


Don’t Cancel the Old Policy First

Suppose you already have:

$500,000

of life insurance.

You’re applying for:

$1 million

with another insurer.

Don’t cancel your existing coverage because:

“The broker thinks I’ll get standard rates.”

Wait until the new policy has been:

Approved

Issued

Reviewed

and:

Put into force.

Then evaluate any replacement carefully.


Group Life Insurance Can Help—but Don’t Depend on It Alone

Pilots, union tradespeople and construction workers may have:

employer or union life insurance.

That’s valuable.

Canada’s Financial Consumer Agency notes that associations, clubs and unions may offer group insurance, but coverage can end when membership ends or when other eligibility conditions change.

Ask:

What happens if I change employers?

Leave the union?

Retire?

Become disabled?

Move into management?

Individual life insurance can provide:

portability independent of the employer.


Example: High-Rise Worker

Suppose a 35-year-old worker has:

$300,000 employer life insurance.

Their family actually needs:

$1 million.

Insurance gap:

$700,000.

They could investigate an individual term policy for that additional amount.

If they later change jobs, the individual coverage generally remains theirs as long as the policy remains in force according to its terms.


Term Life Can Be Particularly Useful

Many high-risk workers need large amounts of coverage during:

Mortgage years

Child-raising years

and:

Peak earning years.

Term life can provide substantial temporary death benefits at generally lower initial premiums than permanent insurance.

Sun Life’s 2026 Canadian cost guidance similarly describes term life as the more affordable type of coverage for temporary protection compared with permanent life.


Match the Term to Your Career

Suppose you’re:

37

and expect to retire from commercial diving at:

52.

A:

15- or 20-year insurance need

could overlap much of your remaining hazardous-career period.

But don’t choose the term solely around:

retirement.

Also consider:

Mortgage

Children

Income replacement

Debts

and:

Family goals.


How Much Coverage Does a High-Risk Worker Need?

Occupation doesn’t determine:

coverage amount.

Your family’s financial exposure does.

Consider:

Mortgage

$450,000

Other debt

$40,000

Income replacement

$600,000

Children’s education

$120,000

Final expenses

$25,000

Total:

$1,235,000.

Existing savings and insurance:

$235,000.

Potential gap:

$1 million.

That’s a better basis for coverage than simply saying:

“My job is dangerous, so I’ll buy $2 million.”


What If Standard Rates Aren’t Available?

You still have options to investigate.

Option 1: Compare another insurer

Underwriting guidelines differ.

Option 2: Accept a rating

A higher premium may still be affordable.

Option 3: Adjust coverage amount

If necessary, prioritize essential family protection.

Option 4: Combine individual and group insurance

Employer coverage can supplement personal insurance.

Option 5: Revisit underwriting later

If your occupational duties materially change.

Option 6: Consider another product

Depending on available underwriting options.

But:

don’t sacrifice necessary protection merely to obtain the word “standard.”


What Not to Do

Don’t hide your job.

Don’t understate diving depth.

Don’t understate flight hours.

Don’t describe high-rise work as office work.

Don’t omit recreational aviation or diving.

Don’t apply randomly to multiple insurers without strategy.

Don’t cancel existing insurance before replacement is active.

Don’t assume one decline means every insurer will decline.

Don’t assume safety certification guarantees standard pricing.

Don’t assume a hazardous job automatically means expensive insurance.


How to Improve Your Chances of a Fair Underwriting Decision

The strongest strategy is surprisingly simple:

1. Be healthy where you can.

Maintain sensible health habits.

2. Don’t smoke.

Smoking can independently increase life-insurance costs substantially.

3. Describe your occupation accurately.

Explain duties rather than only job title.

4. Document experience.

Show how long you’ve safely performed the work.

5. Provide certifications.

Where relevant.

6. Explain actual exposure.

Hours, height, depth, aircraft type and frequency.

7. Disclose accidents honestly.

Don’t hide them.

8. Separate occupational and recreational exposure.

Especially aviation/diving.

9. Use an advisor familiar with complex underwriting.

Particularly for unusual occupations.

10. Compare underwriting outcomes.

Not merely online quotes.


High-Risk Occupation Underwriting Checklist

Before applying, gather:

Exact job title

Detailed job duties

Years of experience

Employer type

Professional licences

Safety certifications

Maximum height/depth where relevant

Percentage of work at elevated risk

Annual flight/dive hours

Aircraft or diving type

International work exposure

Occupational accident history

Recreational hazardous activities

Existing life insurance

Desired coverage

and:

Expected career changes.

A complete application can help prevent:

unnecessary delays

and:

incorrect assumptions.


Questions to Ask Your Insurance Advisor

Ask:

Does this insurer normally rate my exact occupation?

Have you handled applicants with my job before?

Can we request preliminary underwriting guidance?

Is the extra premium temporary or permanent?

Can it be reconsidered if my job changes?

Does my recreational activity create an additional rating?

Could another insurer view my occupation differently?

Am I eligible for preferred rates?

Is standard pricing realistically possible?

What information does the underwriter need?

Should we include an underwriting cover letter?

Are my employer benefits enough?

What happens if I change occupations?

These questions can be much more valuable than simply asking:

“Who’s cheapest?”


Frequently Asked Questions

Can pilots get standard life-insurance rates?

Potentially, yes. Pilot underwriting depends on the nature of aviation, experience, aircraft, flight hours and other factors. Commercial airline flying can be evaluated differently from private, experimental or other higher-risk aviation. Insurer guidelines vary.

Can commercial divers get life insurance?

Yes, depending on the nature of the work. However, commercial and deep-sea diving can attract additional underwriting scrutiny. Sun Life’s current field guide specifically identifies certain commercial/deep diving risks as potentially rateable or difficult to insure.

Does recreational scuba diving increase life-insurance premiums?

Not necessarily. One Sun Life underwriting guide indicates recreational scuba diving up to and including 120 feet can fit within certain favourable underwriting criteria, subject to all other requirements.

Can high-rise construction workers get standard rates?

Potentially. Exact duties, height exposure, trade, safety procedures and insurer guidelines matter. High-rise work isn’t automatically a decline.

Do life insurers check your occupation?

Yes. Occupation can be part of life-insurance underwriting. Sun Life’s 2026 consumer guidance identifies high-risk occupations such as pilots as factors that may increase premiums.

Does wearing safety equipment guarantee standard rates?

No. Safety procedures and training can help an insurer understand the risk, but they don’t guarantee any particular underwriting classification.

What is an occupational flat extra?

It’s an additional premium applied because of increased occupational risk. One current Canadian underwriting guide indicates possible flat extras of $2.50–$7.50 per $1,000 for certain higher-risk occupations, but insurer practices vary.

Can the extra premium disappear if I change jobs?

Potentially, depending on insurer rules and the policy. Ask whether occupational ratings can be reconsidered after a genuine change in duties.

Should I hide a hazardous part of my occupation?

No. Canada.ca advises insurance applicants to answer application questions completely and honestly because inaccurate information can create serious policy and claim consequences.

Is one life-insurance decline final?

Not necessarily. Insurers have different underwriting guidelines. However, disclose prior insurance applications and decisions whenever an application asks for that information.


Final Thoughts

Pilots.

Divers.

Steelworkers.

High-rise construction workers.

These occupations can sound alarming to an insurance underwriter.

But the job title alone doesn’t always tell the:

real risk story.

A pilot flying scheduled commercial passenger aircraft isn’t necessarily equivalent to someone flying experimental aircraft.

A recreational diver staying within ordinary recreational depths isn’t equivalent to a deep-sea commercial diver.

An electrician working mostly inside a high-rise isn’t necessarily equivalent to a structural ironworker spending most of the day on exposed steel.

That’s why the best strategy isn’t:

“How do I hide the risky part so I get standard rates?”

It’s:

“How do I make sure the insurer understands my actual risk?”

Current Canadian underwriting material confirms both sides of this issue: most occupations can be accepted at standard rates, while genuinely higher-risk occupations may attract substantial additional premiums.

Your best approach is therefore to:

Describe your duties precisely

Provide complete exposure information

Document experience and relevant training

Separate occupational from recreational risk

Disclose everything honestly

Consider preliminary underwriting for complex cases

and:

compare insurers.

You may still receive:

standard rates.

You may receive:

standard plus a flat extra.

You might even qualify for:

preferred pricing

if the occupational exposure isn’t rateable and you meet the insurer’s other requirements.

Or the occupation may genuinely require:

additional premium.

The objective isn’t to force the insurer to call you:

“standard.”

The objective is to obtain:

the best legitimate underwriting decision available for your real occupational risk—and enough coverage to protect your family.


Disclaimer

This article is for general informational and educational purposes only and does not constitute personalized insurance, financial, legal, occupational-safety or underwriting advice. Life-insurance classifications differ by insurer, product, occupation, duties, health, lifestyle and individual circumstances. References to specific underwriting guidelines illustrate current insurer practices and do not guarantee the same outcome for any applicant. Always answer insurance applications completely and accurately.

Short-Term Health Insurance: Pros and cons of “Bridge” coverage for digital nomads.

Digital nomad comparing short-term health insurance and travel medical coverage while working remotely.

Quick Takeaway

Short-term health insurance—often called short-term, limited-duration insurance (STLDI)—was designed primarily to fill temporary gaps between more comprehensive health plans.

That sounds appealing for digital nomads who may be:

Between jobs, waiting for employer benefits, freelancing temporarily, moving between states or waiting for longer-term coverage to begin.

But short-term coverage isn’t simply a cheaper version of an Affordable Care Act plan.

It generally isn’t subject to many of the federal consumer protections applicable to comprehensive individual-market coverage. Depending on the policy, it may exclude pre-existing conditions, impose benefit limits or omit important categories of care.

For digital nomads, there’s another problem:

Where does the policy actually cover you?

A plan that works reasonably well while you’re temporarily living in Colorado may be far less useful during three months in Portugal or Thailand.

So before buying “bridge” coverage, evaluate two separate questions:

Is the medical coverage adequate?

and:

Does the coverage follow you where you’re actually going?


What Is Short-Term Health Insurance?

Short-term health insurance is temporary medical coverage designed primarily for gaps between comprehensive insurance arrangements.

Common situations include:

Leaving one job before another begins

Waiting for employer benefits

Temporary unemployment

Transitioning between insurance plans

or:

Needing limited-duration coverage.

It isn’t intended to function exactly like comprehensive ACA individual-market insurance.


Important 2026 Duration Rules

Federal rules adopted in 2024 limited newly issued STLDI policies to an initial contract term of:

No more than three months

and a maximum coverage period, including applicable renewals or extensions, of:

No more than four months.

Those duration provisions apply to applicable policies sold or issued on or after September 1, 2024.

However, state laws can impose additional restrictions, and the regulatory environment can change. Consumers should therefore verify the current rules where they reside before purchasing coverage.


Why Digital Nomads Consider Short-Term Coverage

Digital nomads don’t always fit neatly into traditional insurance arrangements.

Imagine you’re a 31-year-old software consultant.

You leave a full-time employer on:

May 31.

You’re starting another position on:

August 1.

Your new employer’s health insurance begins:

September 1.

That creates a:

three-month coverage gap.

A temporary policy may look attractive because you’re not trying to insure yourself for several years.

You need a bridge.

That’s exactly the type of situation short-term insurance was originally designed to address.


Pros of Short-Term Health Insurance

1. It Can Fill a Genuine Temporary Gap

This is the strongest argument for short-term coverage.

Suppose your old insurance terminates June 30 and your new plan starts September 1.

Going completely uninsured for:

July and August

creates financial risk.

Even a healthy person could experience:

Appendicitis

A broken bone

An unexpected infection

or:

An accident.

A properly chosen temporary policy could provide some protection during that transition.


2. Premiums Can Look Attractive

Short-term policies can sometimes have lower premiums than comprehensive coverage.

But there’s an important reason.

They aren’t required to provide all of the protections that apply to ACA-compliant individual-market coverage.

CMS notes that STLDI isn’t subject to key federal individual-market requirements such as prohibitions against pre-existing-condition exclusions and certain annual or lifetime benefit limits.

So don’t compare:

Premium vs. premium.

Compare:

Coverage vs. coverage.

A $150 plan and a $450 plan may not be providing remotely equivalent protection.


3. It Can Be Useful for People Between Jobs

Digital workers frequently move between:

Traditional employment

Freelancing

Contract work

and:

Startup employment.

If comprehensive coverage begins in a few months, a temporary policy may provide a bridge rather than leaving the person completely uninsured.

But always compare it against alternatives such as:

COBRA

and:

ACA Marketplace coverage.


4. Enrollment Can Be Relatively Quick

Short-term plans are often marketed toward consumers needing coverage quickly.

That can be convenient when your insurance gap appears unexpectedly.

But faster enrollment shouldn’t distract you from:

medical underwriting.

Unlike ACA-compliant individual-market coverage, short-term coverage isn’t guaranteed the same protections regarding health status and pre-existing conditions.


5. It May Cover Major Unexpected Events

Depending on the specific policy, short-term insurance may provide benefits for major unexpected covered events such as:

Hospitalization

Emergency care

Surgery

and:

Physician services.

That’s potentially much better than having:

no coverage.

But the words:

“depending on the policy”

are critical.


The Biggest Cons

1. Pre-Existing Conditions Can Be a Major Problem

ACA-compliant individual-market insurance generally cannot exclude you because of a pre-existing condition.

Short-term insurance is different.

CMS explains that STLDI isn’t subject to the federal prohibition against pre-existing-condition exclusions applicable to comprehensive individual-market insurance.

That can make short-term coverage particularly risky for someone with ongoing healthcare needs.


Example: The Old Knee Injury

Imagine a digital nomad injured their knee:

two years ago.

They purchase short-term coverage.

During the temporary policy period, the knee becomes painful and requires treatment.

Whether that treatment is covered may depend on:

The policy’s definition of a pre-existing condition

Your medical history

Policy exclusions

and:

Applicable state law.

Don’t assume:

“It happened years ago, so it can’t be pre-existing.”

Read the definition.


2. Essential Health Benefits Aren’t Guaranteed

ACA-compliant plans must provide specified essential health benefits.

Short-term coverage isn’t subject to the same federal requirement.

CMS specifically warns that STLDI isn’t guaranteed to cover all essential health benefits.

Depending on the policy, limitations could affect areas such as:

Prescription drugs

Mental-health treatment

Maternity care

Preventive services

or other healthcare.


3. Benefit Limits Can Be Dangerous

Comprehensive ACA coverage has important protections involving annual and lifetime dollar limits on essential health benefits.

STLDI doesn’t necessarily receive those same protections.

A policy might have:

benefit maximums.

That’s particularly important if you experience:

Cancer

Major trauma

Extended hospitalization

or:

Complex surgery.

A cheap premium isn’t very helpful if the policy stops paying long before your medical bills stop arriving.


4. Out-of-Pocket Exposure Can Be Higher Than Expected

A short-term policy may combine:

High deductible

Coinsurance

Copays

and:

Benefit limits.

Imagine:

Premium: $180/month

Deductible: $5,000

Coinsurance: 30%

You might initially think:

“Great—only $180 per month.”

But a significant medical event could expose you to thousands of dollars.

The premium tells you:

what coverage costs to maintain.

It doesn’t tell you:

what getting sick will cost.


5. No Surprises Act Protections May Not Apply

This is a particularly important limitation.

CMS states that services covered under short-term limited-duration plans aren’t subject to the federal billing protections of the No Surprises Act in the same way qualifying comprehensive coverage is.

For consumers, that makes understanding:

Networks

Emergency-care provisions

and:

Out-of-network exposure

especially important.


The Digital Nomad Problem: Domestic Coverage Isn’t International Coverage

Suppose you’re a U.S. resident spending:

January — California

February — Arizona

March — Mexico

April — Costa Rica

A U.S. short-term medical policy shouldn’t automatically be assumed to cover healthcare in:

Mexico or Costa Rica.

Short-term U.S. health insurance and:

international/travel medical insurance

are different products.

A digital nomad who regularly works abroad needs to investigate international medical coverage separately.


Domestic Nomads Have a Network Problem Too

You don’t need to leave America for geography to matter.

Imagine your short-term policy uses a regional provider network centered in:

Texas.

You spend two months working remotely from:

Oregon.

You become sick.

Now you discover that the providers available near you aren’t participating in your plan’s preferred network.

Before buying coverage, ask:

Is the network nationwide?

What happens outside my home state?

How are emergencies handled?

Is urgent care covered nationally?

What happens if I relocate temporarily?

These questions matter enormously to digital nomads.


Short-Term Insurance vs. Travel Insurance

They’re not interchangeable.

Short-Term Health Insurance

Primarily addresses temporary health coverage, generally within its specified geographic and provider structure.

Travel Medical Insurance

Typically focuses on medical emergencies occurring during travel.

Comprehensive International Health Insurance

Can provide broader ongoing medical coverage for people living internationally.

Digital nomads frequently confuse these three categories.


Example: Six Months in Thailand

Suppose you’re a U.S. citizen working remotely from Thailand for:

six months.

Buying an American short-term health plan without verifying international coverage could create a dangerous assumption:

“I have health insurance.”

You might technically own a policy.

But the real question is:

Will it pay for treatment where you are?

For long-term international nomads, an international health policy may be more relevant than domestic STLDI.


Short-Term Insurance vs. ACA Marketplace Coverage

ACA Marketplace coverage generally provides much stronger federal consumer protections.

Marketplace plans cover essential health benefits and cannot deny coverage or charge more because of a pre-existing health condition.

Short-term insurance can be less comprehensive.

The trade-off may look like this:

FeatureShort-Term PlanACA Plan
Temporary bridge useStrong use casePossible
Pre-existing condition protectionNot federally guaranteedYes
Essential health benefitsNot guaranteedRequired
Medical underwritingMay applyHealth-status underwriting prohibited
Benefit limitsMay applyStronger ACA protections
Premium tax creditsNo Marketplace subsidyPossible if eligible
Long-term primary coverageGenerally poor fitDesigned for it

Don’t Forget Special Enrollment Periods

Losing employer-sponsored health insurance may allow you to enroll in Marketplace coverage outside the annual Open Enrollment Period.

So if you leave a job, don’t automatically conclude:

“Open Enrollment is over, therefore I need short-term insurance.”

Check whether you qualify for a:

Special Enrollment Period.

This could give you access to comprehensive ACA coverage instead.


What About COBRA?

If you’re leaving an employer with qualifying group health coverage, COBRA may allow you to temporarily continue that plan.

Its major disadvantage is often:

cost.

You may become responsible for much more of the premium previously subsidized by your employer.

But COBRA can offer an important advantage:

continuity.

You may be able to keep:

The same doctors

The same network

The same prescription coverage

and:

The same plan structure.

For someone undergoing ongoing treatment, that continuity may be worth paying for.


Short-Term vs. COBRA vs. Marketplace

Before buying bridge coverage, compare all three.

Short-Term Insurance

Potentially lower premium, but weaker protections.

COBRA

Potentially expensive, but excellent continuity.

ACA Marketplace Plan

Comprehensive protections and potentially premium subsidies if eligible.

Don’t assume the cheapest monthly premium is the cheapest overall choice.


Digital Nomads Need a Fourth Comparison

Add:

International Health/Travel Medical Coverage

if you’re leaving the United States.

Your decision matrix becomes:

STLDI vs. Marketplace vs. COBRA vs. International Coverage

The correct answer depends heavily on:

where you’ll physically live during the coverage period.


When Short-Term Coverage May Make Sense

A bridge plan can potentially make sense when:

Your gap is genuinely brief.

You understand the exclusions.

You’re eligible for the policy.

You don’t need ongoing treatment excluded by the plan.

The provider network works where you’ll be staying.

You’re remaining within the covered geographic territory.

Comprehensive alternatives are significantly more expensive.

and:

You understand the financial exposure.


When It May Be a Poor Choice

Short-term insurance may be particularly risky if:

You have significant pre-existing conditions.

You take expensive medications.

You need regular mental-health treatment.

You’re planning pregnancy.

You expect surgery.

You travel internationally for long periods.

You need predictable comprehensive benefits.

or:

You can’t financially absorb large uncovered expenses.


The “I’m Healthy” Trap

A common argument is:

“I’m 27 and healthy. I don’t need comprehensive insurance.”

But insurance isn’t primarily for the healthcare expenses you already expect.

It’s also for:

unpredictable financial risk.

A healthy 27-year-old can still experience:

Appendicitis

A cycling accident

A serious infection

A sports injury

or:

An unexpected diagnosis.

Being healthy makes major medical expenses:

less predictable.

It doesn’t make them impossible.


Read the Exclusions Before Buying

Don’t just read:

“Benefits up to $1 million.”

Find the exclusions.

Look specifically for:

Pre-existing conditions

Prescription drugs

Mental health

Maternity

Preventive care

Sports injuries

Adventure activities

International treatment

Out-of-network services

Emergency evacuation

and:

Annual/lifetime maximums.

For digital nomads, geographic exclusions deserve special attention.


Adventure Activities Can Matter

Digital nomads often combine work with activities such as:

Surfing

Scuba diving

Mountain biking

Skiing

Climbing

or:

Motorcycle travel.

Insurance policies can contain exclusions or limitations involving certain higher-risk activities.

If your lifestyle includes them, don’t assume they’re covered.

Read the contract before participating.


Emergency Evacuation Is a Different Benefit

Imagine you’re working remotely from an island.

You suffer a serious injury.

The local clinic can’t provide appropriate treatment.

You need transport to:

a larger medical facility.

That can involve:

medical evacuation.

A domestic short-term health policy may not provide the international evacuation protection a travel or international policy offers.

For global nomads, this can be a major coverage gap.


Repatriation Is Different Again

International policies may also offer:

repatriation benefits.

These can involve transportation back to your home country under specified circumstances.

Don’t assume:

Emergency medical treatment

Medical evacuation

and:

Repatriation

are one benefit.

They’re separate concepts.


Prescription Coverage Deserves Extra Attention

If you regularly take medication, check:

Is the drug covered?

Is there a separate deductible?

Is there a formulary?

Are prescriptions outside the U.S. covered?

Can you obtain an extended supply before travelling?

Is mail-order available?

A plan that’s excellent for hospital emergencies but poor for prescriptions may be unsuitable for someone managing a chronic condition.


Telehealth Can Help Nomads—but Check the Rules

Some insurance products provide access to:

virtual care.

That’s attractive for someone frequently changing locations.

But availability can depend on:

Your current location

Provider licensing

Plan network

and:

The medical service required.

Don’t assume a telehealth provider can treat you from every state or every country simply because the appointment happens online.


A Practical Nomad Example

Meet Alex.

He’s a 29-year-old U.S.-based graphic designer.

He leaves his employer on:

March 31.

He’ll freelance for three months before beginning a new job on:

July 1.

His new health benefits begin:

August 1.

Alex plans to spend those months in:

Colorado

and:

Utah.

His decision isn’t simply:

“Should I buy short-term insurance?”

He should compare:

Marketplace eligibility

COBRA

Short-term coverage

Provider networks in both states

Prescription coverage

and:

Worst-case out-of-pocket exposure.

Because he’s staying within the U.S., international medical coverage isn’t the primary issue.


Now Change One Detail

Instead of Colorado and Utah, Alex spends those three months in:

Portugal

and:

Spain.

The insurance analysis changes dramatically.

Now he needs to investigate:

International medical coverage

Emergency evacuation

Local provider access

Direct billing

Repatriation

and:

Coverage when briefly returning to America.

Same person.

Same three-month gap.

Completely different insurance needs.


Calculate the Worst-Case Scenario

Don’t compare only monthly premiums.

Imagine:

Short-Term Plan

Premium: $170/month

Deductible: $5,000

Coinsurance: 30%

Benefit maximum: Limited according to policy

versus:

Comprehensive Plan

Premium: $420/month

Deductible: $2,000

Stronger consumer protections.

Over three months, the short-term option saves:

$750 in premiums.

That’s meaningful.

But ask:

How much additional financial exposure am I accepting to save $750?

That’s the right comparison.


Your 2026 Digital Nomad Insurance Checklist

Before buying bridge coverage:

  • Determine exactly how long you need insurance.
  • List every state and country you’ll visit.
  • Check whether STLDI is available under applicable state law.
  • Verify the policy’s geographic coverage.
  • Review the provider network.
  • Check emergency coverage outside your home area.
  • Review pre-existing-condition exclusions.
  • Check prescription-drug coverage.
  • Review mental-health benefits.
  • Review maternity coverage where relevant.
  • Check benefit maximums.
  • Review deductible and coinsurance.
  • Check out-of-pocket exposure.
  • Read exclusions for sports and adventure activities.
  • Verify international coverage.
  • Check emergency medical evacuation.
  • Check repatriation benefits.
  • Compare COBRA.
  • Check Marketplace Special Enrollment eligibility.
  • Compare comprehensive ACA plans.
  • Consider international medical coverage if living abroad.
  • Check telehealth availability.
  • Don’t buy based on premium alone.
  • Keep a digital copy of your policy and insurance card while travelling.

Frequently Asked Questions

What is short-term health insurance?

Short-term, limited-duration insurance is temporary health coverage primarily intended to bridge gaps between comprehensive health plans.

How long can short-term health insurance last?

Under the 2024 federal rule applicable to newer STLDI policies, the initial contract term is limited to no more than three months and the maximum coverage period to four months, including renewals or extensions. State restrictions can be stricter.

Does short-term insurance cover pre-existing conditions?

It isn’t subject to the same federal prohibition against pre-existing-condition exclusions that applies to comprehensive individual-market coverage, so exclusions can apply depending on the policy and state rules.

Does short-term insurance cover all essential health benefits?

Not necessarily. STLDI isn’t required under federal law to provide the same comprehensive essential-health-benefit protections as ACA individual-market plans.

Is short-term insurance good for digital nomads?

It can potentially work for a short domestic coverage gap, but nomads must pay particular attention to geographic coverage, networks and exclusions.

Does U.S. short-term insurance cover me overseas?

Don’t assume it does. International benefits depend on the specific policy. Someone living or travelling abroad should separately compare travel medical and international health insurance.

Is travel insurance the same as short-term health insurance?

No. Travel medical insurance, comprehensive international health insurance and U.S. short-term health insurance serve different purposes.

Are short-term plans protected by the No Surprises Act?

CMS states that services covered by short-term limited-duration insurance aren’t subject to the federal No Surprises Act billing protections in the same way qualifying comprehensive health coverage is.


Final Thoughts

Short-term health insurance can be useful when it does exactly what its name suggests:

covers a short transition.

For a digital nomad spending a couple of months between employer plans, a carefully selected bridge policy could provide useful protection.

But cheap premiums can conceal important limitations.

Short-term plans don’t necessarily provide the same federal protections regarding:

Pre-existing conditions

Essential health benefits

Annual or lifetime limits

and other areas that consumers receive with comprehensive ACA-regulated coverage.

And digital nomads face an additional challenge:

Insurance must work where you physically are—not merely where your permanent address says you live.

A domestic short-term policy might make sense for three months spent working around the United States.

The same policy could be entirely inappropriate for three months travelling through Southeast Asia or Europe.

Before buying, compare:

Short-Term + ACA Marketplace + COBRA + International Coverage

and evaluate:

Premium + Deductible + Exclusions + Maximum Benefits + Geographic Coverage.

The best bridge isn’t necessarily the cheapest policy.

It’s the one that actually reaches the other side of your coverage gap without leaving a major financial hole underneath you.

Medicare Part D “Donut Hole” in 2026: New changes to prescription drug out-of-pocket caps.

Medicare beneficiary reviewing 2026 Part D prescription drug costs and the $2,100 annual out-of-pocket cap.

Quick Takeaway

If you remember Medicare Part D’s infamous:

“Donut hole,”

there’s an important update.

The traditional Part D coverage gap no longer exists.

The old coverage-gap phase was eliminated beginning in 2025 as part of the Inflation Reduction Act’s redesign of Medicare Part D. In 2026, the standard Part D benefit has three main stages:

Deductible → Initial Coverage → Catastrophic Coverage.

And there is another major number Medicare beneficiaries should know:

$2,100

That’s the 2026 annual out-of-pocket threshold for covered Part D prescription drugs. Once your qualifying out-of-pocket spending reaches that threshold, you enter catastrophic coverage and owe $0 in cost sharing for covered Part D drugs for the remainder of the calendar year.

The 2026 standard Part D deductible is:

$615

although individual plans can charge a lower deductible—or no deductible at all.

For people who take expensive medications, these changes fundamentally alter how prescription-drug expenses should be planned.


First: What Was the Medicare Part D Donut Hole?

For years, Medicare Part D had several coverage phases.

Beneficiaries could move from:

Deductible

to:

Initial Coverage

then into:

Coverage Gap

and eventually:

Catastrophic Coverage.

That middle phase became popularly known as the:

Donut Hole.

Historically, entering the coverage gap could significantly change what beneficiaries paid for prescriptions.

It became one of the most recognizable—and confusing—features of Medicare Part D.

But today’s Part D structure is different.


The Donut Hole Was Eliminated in 2025

This is an important distinction for a 2026 article.

The donut hole didn’t disappear for the first time in 2026.

CMS confirms that the coverage-gap phase was eliminated in:

2025.

The 2026 benefit continues that redesigned structure.

So rather than four traditional phases, the standard Part D benefit now essentially has:

1. Deductible

2. Initial Coverage

3. Catastrophic Coverage

That’s much easier for beneficiaries to understand.


What’s New for 2026?

The major annual change is the out-of-pocket threshold.

In 2025, the Part D annual out-of-pocket cap was:

$2,000.

For 2026, CMS increased the threshold to:

$2,100.

CMS explains that the increase reflects the statutory annual adjustment based on changes in average expenditures for covered Part D drugs.

So the protection remains—but the dollar amount increased by:

$100.


Medicare Part D in 2026 at a Glance

Part D Feature2026
Maximum standard deductible$615
Initial standard coinsurance25%
Annual out-of-pocket threshold$2,100
Cost sharing after reaching threshold$0 for covered Part D drugs
Traditional coverage gap / donut holeEliminated

CMS confirms both the $615 deductible and $2,100 out-of-pocket threshold for the defined standard 2026 Part D benefit.

Individual plans can structure benefits differently while satisfying Medicare requirements.


Stage 1: The Deductible

Let’s start at the beginning of the year.

Under the defined standard Part D benefit, the 2026 deductible is:

$615.

During the deductible stage, you generally pay the cost of your covered prescriptions until the deductible is satisfied.

However:

Your specific plan may have a lower deductible.

Some plans have:

$0 deductibles.

Medicare confirms that no Medicare drug plan may charge more than $615 for its deductible in 2026.


Not Every Drug Necessarily Faces the Full Deductible

Plan design matters.

A Part D plan could potentially provide coverage for certain drug tiers before the full deductible is satisfied.

For example, a plan might offer low copays for certain generic medications while applying its deductible differently to other drugs.

That’s why you shouldn’t choose a Part D plan simply by looking at:

deductible size.

You need to enter your actual prescriptions into Medicare’s Plan Compare tool and evaluate the plan’s formulary and estimated annual costs.

Medicare Plan Compare


Stage 2: Initial Coverage

Once the applicable deductible is satisfied, you enter:

Initial Coverage.

Under the defined standard benefit, the beneficiary generally pays:

25% coinsurance

for covered Part D drugs during this phase.

But actual Medicare drug plans may use:

Fixed copays

Coinsurance

Drug tiers

and other Medicare-compliant benefit structures.

So your pharmacy receipt won’t necessarily say:

exactly 25%.


Stage 3: Catastrophic Coverage

This is where the new Part D structure provides its strongest protection.

Once qualifying annual out-of-pocket spending reaches:

$2,100 in 2026

you enter catastrophic coverage.

Then:

You pay $0 for covered Part D drugs for the remainder of the calendar year.

Medicare’s official 2026 handbook confirms that after reaching the $2,100 threshold, beneficiaries owe no copayment or coinsurance for covered Part D prescriptions for the rest of the year.


Why the $2,100 Cap Matters

Consider someone taking several inexpensive generic medications.

They might never approach:

$2,100.

For that person, the cap may not materially affect annual spending.

Now consider someone taking an expensive medication for:

Cancer

Rheumatoid arthritis

Multiple sclerosis

Diabetes

or another serious condition.

Historically, beneficiaries taking very expensive prescriptions could face substantial ongoing Part D cost sharing.

The annual cap creates a much clearer limit on qualifying out-of-pocket Part D drug spending.


Example: An Expensive Specialty Medication

Imagine a Medicare beneficiary takes an expensive covered specialty medication.

Their prescription expenses push qualifying Part D out-of-pocket spending to:

$2,100

by May.

Under the 2026 rules, after reaching that threshold, they enter catastrophic coverage.

For the rest of the calendar year, their cost sharing for covered Part D drugs becomes:

$0.

That doesn’t mean the medication itself suddenly becomes free.

The remaining cost is allocated among the Part D plan, manufacturers where applicable and Medicare according to the redesigned benefit structure.

But the beneficiary no longer owes additional cost sharing for those covered Part D drugs.


Does the $2,100 Include Your Premium?

No.

This is one of the most important details to understand.

The:

$2,100

threshold refers to qualifying out-of-pocket spending associated with covered Part D prescriptions.

Your:

monthly Part D premium

is separate.

Medicare beneficiaries continue paying applicable plan premiums even after reaching the drug out-of-pocket threshold.


So $2,100 Isn’t Your Maximum Total Medicare Spending

Suppose your Part D premium is:

$50/month.

That’s:

$600 annually.

If you also reach the $2,100 Part D out-of-pocket threshold, your combined spending could already be:

$2,700

before considering other Medicare expenses.

And that’s only the drug side.

You may separately have costs involving:

Medicare Part B

Hospital care

Dental care

Vision

Medicare Advantage

or:

Medigap.

So don’t interpret the $2,100 limit as:

“My entire Medicare healthcare spending is capped at $2,100.”

It isn’t.


The Cap Applies to Covered Part D Drugs

Another crucial phrase is:

Covered Part D drugs.

Suppose you purchase a medication that your Part D plan doesn’t cover.

You shouldn’t automatically assume that expenditure will count toward the $2,100 threshold.

Formulary status therefore remains extremely important.

A low-premium plan that doesn’t appropriately cover your medications can still be a poor choice.


The Donut Hole Is Gone—but Formulary Rules Aren’t

Eliminating the coverage gap doesn’t eliminate:

Formularies

Drug tiers

Prior authorization

Step therapy

Quantity limits

or:

Pharmacy networks.

These rules can still affect:

whether your prescription is covered

and:

how much you pay.

The $2,100 cap makes covered-drug financial exposure more predictable, but it doesn’t turn Part D into unrestricted prescription coverage.


Medicare Drug Price Negotiation Also Arrived in 2026

There’s another major Medicare prescription-drug change happening simultaneously.

On:

January 1, 2026

negotiated prices for the first 10 drugs selected under Medicare’s Drug Price Negotiation Program took effect.

Medicare’s official 2026 guidance confirms that negotiated prices for the first group of Part D drugs became effective at the start of 2026.

This is separate from the:

$2,100 out-of-pocket cap.

But both reforms can affect what beneficiaries pay.


The First 10 Negotiated Drugs

The initial group includes widely used and expensive medications covering conditions such as:

Diabetes

Blood clots

Heart failure

Kidney disease

Arthritis

Psoriasis

Crohn’s disease

and:

Certain blood cancers.

For beneficiaries taking one of the selected drugs, the new negotiated prices can influence prescription costs in addition to the annual Part D cap.


Insulin Protection Continues in 2026

Insulin has its own important cost-sharing protection.

CMS says that beginning in 2026, beneficiary cost sharing for a month’s supply of each covered insulin product is capped at the lowest of:

$35

25% of the applicable Medicare-negotiated maximum fair price

or:

25% of the plan’s negotiated price.

That’s an important change from thinking of:

$35

as automatically being the amount every beneficiary pays.

For some covered insulin products, the applicable amount can potentially be:

lower.


Certain Vaccines Remain $0

Another Inflation Reduction Act benefit continues.

Medicare Part D beneficiaries continue to owe:

$0 cost sharing

for adult vaccines recommended by the Advisory Committee on Immunization Practices and covered under Part D.

Depending on eligibility, that can include vaccines protecting against diseases such as:

Shingles

and:

Tetanus/diphtheria/pertussis.

These vaccine benefits aren’t dependent on reaching the $2,100 threshold first.


The Medicare Prescription Payment Plan Continues

There’s another program that can help people with high prescription costs:

Medicare Prescription Payment Plan.

All Medicare prescription drug plans must offer this payment option.

The program lets participants spread eligible out-of-pocket Part D prescription costs across monthly payments during the calendar year rather than necessarily paying large amounts at the pharmacy all at once.

But there’s a critical distinction:

It doesn’t reduce your total drug cost.

It changes:

when you pay.

Medicare explicitly says the payment plan can help manage monthly expenses but doesn’t lower the total cost of your prescriptions.


Example: High Costs Early in the Year

Suppose you fill an expensive prescription in:

January.

Without payment smoothing, you might face substantial out-of-pocket costs immediately.

Using the Medicare Prescription Payment Plan could allow those eligible expenses to be spread across the remaining months of the calendar year.

That can help with:

cash flow.

But if your total qualifying Part D out-of-pocket responsibility reaches $2,100, participating in the payment program doesn’t make that annual cap smaller.


$2,100 Cap vs. Payment Plan

These are easy to confuse.

$2,100 Out-of-Pocket Cap

Limits qualifying annual Part D drug spending.

Medicare Prescription Payment Plan

Lets you spread your applicable prescription expenses across the year.

The first can:

reduce financial exposure.

The second can:

smooth cash flow.

They’re different protections.


Why “Donut Hole” Is Now an Outdated Shopping Metric

Years ago, consumers comparing Part D plans had to worry heavily about:

entering the coverage gap.

That’s no longer the right framework.

In 2026, focus instead on:

Annual premium

Deductible

Your medications

Formulary coverage

Drug tiers

Pharmacy network

Prior authorization

Estimated annual cost

and:

$2,100 out-of-pocket protection.

That’s a much more useful way to evaluate Part D today.


Don’t Choose a Plan Only Because the Premium Is $0 or Very Low

Imagine:

Plan A

Premium: $5/month

but your expensive medication sits on an unfavorable tier.

Plan B

Premium: $45/month

but provides better coverage for the prescriptions you actually take.

Plan B could potentially produce a lower:

total annual cost.

Always compare:

Premium + Prescription Costs

rather than premium alone.


Pharmacy Networks Still Matter

Your Part D plan may have:

Preferred pharmacies

Standard pharmacies

and possibly:

Out-of-network restrictions.

The same prescription can potentially cost different amounts depending on where it’s filled.

So when comparing plans, enter:

your actual pharmacy.

Then compare alternatives.

Mail-order options may also be worth evaluating.


What About Medicare Advantage?

Many Medicare Advantage plans include Part D prescription coverage.

These are commonly called:

MA-PD plans.

The $2,100 annual Part D out-of-pocket threshold applies to Medicare drug coverage in 2026, including applicable MA-PD coverage.

But don’t confuse the prescription-drug cap with your Medicare Advantage medical out-of-pocket maximum.

Those are:

separate concepts.


What About Extra Help?

Some beneficiaries qualify for:

Extra Help

with Medicare prescription costs.

People receiving Extra Help can have substantially different:

Deductibles

Copays

and:

Prescription costs.

Medicare’s 2026 handbook specifically notes that Extra Help beneficiaries won’t have some of the standard Part D costs discussed above.

If your income and resources are limited, investigate eligibility rather than assuming standard Part D prices apply to you.


Example: Three Medicare Beneficiaries

Robert — Low Drug Use

Robert takes two inexpensive generic prescriptions.

His annual drug spending is modest.

He may never approach:

$2,100.

For him, important comparison factors might include:

Premium

Generic copays

and:

Pharmacy network.

Susan — Moderate Drug Use

Susan takes several brand-name medications.

Her costs are meaningful but don’t reach the annual threshold.

For her, formulary tiers and coinsurance become extremely important.

Michael — Very High Drug Use

Michael takes an expensive specialty medication.

He reaches:

$2,100

in qualifying out-of-pocket spending relatively early in the year.

After reaching the threshold, his cost sharing for covered Part D prescriptions becomes:

$0 for the remainder of 2026.

For Michael, the redesigned catastrophic protection can be financially significant.


What Happens on January 1, 2027?

The Part D out-of-pocket threshold operates on a:

calendar-year basis.

That means the 2026 protection doesn’t simply continue accumulating indefinitely.

A new annual threshold applies in the next calendar year.

The statutory cap is indexed, so consumers should check Medicare’s published Part D parameters annually rather than assuming:

$2,100

will remain unchanged forever.


Why Annual Plan Shopping Still Matters

The existence of an out-of-pocket cap doesn’t eliminate the need to compare Part D plans.

Plans can change:

Premiums

Formularies

Drug tiers

Pharmacy networks

Prior-authorization requirements

and:

Cost sharing.

Your medications can change too.

So even if your current plan worked well in 2026, review it during the next Medicare Open Enrollment period.


Your 2026 Part D Checklist

Before choosing or renewing drug coverage:

  • List every prescription you currently take.
  • Record the exact dosage and frequency.
  • Check whether each medication is on the plan’s formulary.
  • Check the drug tier.
  • Check prior-authorization requirements.
  • Check step-therapy requirements.
  • Review quantity limits.
  • Compare preferred pharmacies.
  • Compare mail-order pricing where appropriate.
  • Check the monthly premium.
  • Check the deductible.
  • Remember the 2026 maximum standard deductible is $615.
  • Understand the $2,100 annual out-of-pocket threshold.
  • Remember the traditional donut hole is gone.
  • Check whether you qualify for Extra Help.
  • Review insulin cost-sharing rules if applicable.
  • Remember qualifying Part D vaccines can have $0 cost sharing.
  • Consider the Medicare Prescription Payment Plan if high early-year expenses would strain your budget.
  • Compare total estimated annual costs rather than premiums alone.
  • Recheck coverage every year.

Frequently Asked Questions

Is there still a Medicare Part D donut hole in 2026?

No. The traditional coverage-gap phase was eliminated beginning in 2025. The redesigned standard benefit now moves from deductible to initial coverage and then catastrophic coverage.

What is the Medicare Part D out-of-pocket cap for 2026?

The annual out-of-pocket threshold is:

$2,100.

What happens after I spend $2,100?

Once qualifying out-of-pocket spending reaches $2,100, you enter catastrophic coverage and pay $0 in cost sharing for covered Part D drugs for the remainder of 2026.

What is the Part D deductible in 2026?

The maximum deductible is $615. Some plans have a smaller deductible or no deductible.

Does my monthly Part D premium count toward the $2,100?

No. The annual out-of-pocket threshold concerns qualifying spending on covered Part D prescription drugs, not your monthly plan premium.

Is insulin still capped at $35?

For 2026, CMS says cost sharing for a month’s supply of a covered insulin product is capped at the lesser of $35, 25% of the applicable negotiated maximum fair price, or 25% of the plan’s negotiated price.

Does the Medicare Prescription Payment Plan reduce my drug costs?

No. It allows eligible costs to be spread across the calendar year but doesn’t itself lower the total amount you owe.

Do I need to enroll in the payment plan to get the $2,100 cap?

No. Medicare says the $2,100 out-of-pocket limit applies to everyone with Medicare drug coverage, regardless of whether they participate in the Medicare Prescription Payment Plan.


Final Thoughts

For years, the:

Medicare Part D donut hole

symbolized one of Medicare prescription coverage’s biggest financial uncertainties.

That’s no longer how Part D works.

The coverage-gap phase was eliminated in 2025, and in 2026 the redesigned standard benefit provides a much clearer progression:

Deductible → Initial Coverage → Catastrophic Coverage

with a:

$2,100 annual out-of-pocket threshold.

After reaching that threshold, beneficiaries owe $0 in cost sharing for covered Part D prescriptions for the rest of the calendar year.

That doesn’t make prescription insurance simple.

You still need to evaluate:

Formularies

Drug tiers

Pharmacy networks

Premiums

Prior authorization

and:

Plan-specific cost sharing.

But the redesigned system provides something beneficiaries taking expensive medications historically lacked:

a much clearer ceiling on annual covered Part D drug cost sharing.

For 2026, remember three numbers:

$615 — Maximum standard deductible

$2,100 — Annual out-of-pocket threshold

$0 — Cost sharing for covered Part D drugs after reaching that threshold

Those numbers are far more useful today than worrying about falling into the old:

“donut hole.”

Rideshare Insurance for Uber/Lyft: Does your personal policy’s “Rideshare Rider” cover “Period 1” (app on, no passenger)?

Driving for Uber or Lyft can look simple from an insurance perspective.

You have personal auto insurance.

Uber or Lyft provides insurance while you’re working.

So you might assume you’re continuously protected.

Unfortunately, the transition between personal driving and commercial rideshare driving creates one of the most misunderstood coverage issues in the gig economy.

The critical moment is commonly known as:

Period 1.

Period 1 begins when you turn on your rideshare app and become available to receive requests—but you haven’t accepted a trip yet.

You may be:

  • Parked waiting for a request
  • Driving toward a busy neighborhood
  • Circling an airport area where permitted
  • Heading toward downtown
  • Moving between potential pickup areas

There is no passenger in your vehicle.

You haven’t accepted a request.

But from an insurance perspective, you’re no longer necessarily just driving for personal purposes.

The National Association of Insurance Commissioners (NAIC) identifies this exact stage as a persistent area where coverage gaps can arise.


What Are Periods 0, 1, 2 and 3?

Understanding rideshare insurance starts with understanding the different stages of a trip.

Period 0 — App Off

Your Uber or Lyft driver app is off.

You’re using your vehicle personally.

Your personal auto insurance normally applies according to your policy.

Uber states that when you’re offline, your personal auto insurance covers you. Lyft similarly says its rideshare policy doesn’t apply while its app is off.

Period 1 — App On, Waiting for a Request

You’ve turned the app on and are available to accept passengers.

But:

No ride has been accepted.

This is the stage we’re focusing on.

Period 2 — Ride Accepted

You’ve accepted a ride and are driving toward the passenger.

Period 3 — Passenger in Vehicle

You’ve picked up the passenger and are completing the trip.

NAIC uses this three-period rideshare framework, with Period 1 representing the time when the app is on and the driver is waiting for a request.


Why Period 1 Is So Important

Imagine this situation.

You’re driving home from work.

Your Uber app is:

OFF.

You cause an accident.

Your personal auto policy generally applies according to its terms.

Now imagine the same road.

Same car.

Same driver.

Same accident.

But five minutes earlier, you switched your Uber app:

ON.

You’re waiting for a ride request.

Suddenly, the insurance situation can change dramatically.

That’s because many personal auto policies contain exclusions relating to:

  • Livery
  • Transportation for compensation
  • Commercial use
  • Availability for hire
  • Transportation network company activity

NAIC warns consumers that personal auto insurance typically excludes coverage for business use or while drivers are available for hire.


Does Your Personal Auto Insurance Cover Period 1?

A standard personal auto policy may not provide full coverage once you log into the Uber or Lyft app.

NAIC notes that most personal auto policies continue to exclude rideshare or livery-related activity and specifically identifies Period 1 as a point where coverage gaps can occur.

That means you shouldn’t assume:

“I don’t have a passenger, so I’m still covered personally.”

Your app status can matter.

This is exactly why insurers developed:

rideshare endorsements

sometimes informally called:

rideshare riders.


What Is a Rideshare Endorsement?

A rideshare endorsement is additional coverage added to an eligible personal auto insurance policy.

Its purpose is generally to modify some of the normal exclusions that can apply when you use your personal vehicle for rideshare work.

Depending on the insurer, it may provide additional protection during:

Period 1

and sometimes interact with Uber or Lyft coverage during later periods.

However, there is no universal rideshare endorsement.

Coverage differs by:

  • Insurer
  • State
  • Policy
  • Vehicle
  • Rideshare platform

This is why the answer to:

“Does my rideshare endorsement cover Period 1?”

is:

It may—but you must verify exactly what your insurer covers.


What Does Uber Cover During Period 1?

Uber currently states that when you’re online and available for a trip but haven’t accepted one, it maintains third-party liability insurance for covered accidents.

Uber lists at least:

$50,000 bodily injury per person

$100,000 bodily injury per accident

$25,000 property damage per accident

with actual requirements and coverage varying by state.

This is commonly written as:

50/100/25.

But notice what this primarily protects:

Liability to other people.

It doesn’t mean your own vehicle has collision and comprehensive coverage during Period 1.


Does Uber Cover Your Car During Period 1?

This is the coverage gap every Uber driver should understand.

Uber states that there is no Uber-maintained collision or comprehensive coverage when you’re online but haven’t yet accepted a trip.

Consider an example.

You’re online waiting for a passenger.

You accidentally hit a concrete pillar.

Your vehicle suffers:

$9,000 in damage.

No other vehicle is involved.

You have Collision coverage on your normal personal auto policy.

But your personal insurer excludes rideshare activity once the app is active.

Uber’s contingent Collision coverage hasn’t started because you haven’t accepted a trip.

You could potentially face a significant coverage problem.

A suitable rideshare endorsement may help address this situation.


What Does Lyft Cover During Period 1?

Lyft’s structure is similar.

When its app is on and the driver is available to receive ride requests, Lyft says it maintains third-party liability insurance for covered accidents if the driver’s personal insurance does not apply.

Lyft currently lists at least:

$50,000 per person for bodily injury

$100,000 per accident for bodily injury

$25,000 per accident for property damage

in most markets.

Certain jurisdictions have different requirements.

Again, this is principally third-party liability protection.


Does Lyft Provide Collision Coverage During Period 1?

Lyft’s published insurance information describes contingent comprehensive and collision protection during the period after you’ve accepted a request and while you’re completing the ride, provided you maintain Comprehensive and Collision coverage on your personal policy.

Its published Period 1 coverage, when you’re simply waiting for a request, is third-party liability coverage rather than the same contingent physical-damage protection available during an accepted trip.

That distinction matters if your personal policy excludes rideshare activity.


Period 1 vs. Period 2: The Insurance Difference

Imagine you’re parked outside a coffee shop.

Your Uber app is on.

8:00 PM

No request yet.

You’re in:

Period 1.

8:02 PM

A passenger requests a ride.

You accept.

You’re now driving toward them.

You’re in:

Period 2.

Those two minutes can make a substantial difference to your insurance.

Uber’s published coverage increases after you’ve accepted a trip, including at least $1 million in third-party liability coverage in applicable markets and contingent comprehensive and collision coverage when you maintain those coverages on your personal policy.

Lyft similarly states that in most markets it maintains at least $1 million in third-party liability once you’re en route to pick up a passenger or during a ride, along with contingent Comprehensive and Collision where applicable.


Uber/Lyft Coverage by Driving Period

Driving StagePersonal PolicyTNC LiabilityTNC Collision/Comprehensive
App offNormally appliesGenerally noNo
Period 1: App on, waitingMay be restricted/excludedLimited liability appliesGenerally no
Period 2: Request acceptedPersonal coverage may be restrictedHigher TNC liabilityContingent coverage may apply
Period 3: Passenger onboardPersonal coverage may be restrictedHigher TNC liabilityContingent coverage may apply

Exact coverage varies by platform, insurer, state, and policy.


Why Your Rideshare Endorsement Matters Most During Period 1

Period 1 is where a well-designed rideshare endorsement can become particularly valuable.

The NAIC specifically notes that insurers have developed rideshare endorsements and hybrid personal-commercial products designed to address coverage gaps, including the historically underinsured Period 1.

Depending on the policy, an endorsement may extend certain personal-policy protections while you’re logged into the rideshare app but haven’t accepted a trip.

Potentially, that could include:

  • Collision
  • Comprehensive
  • Liability enhancements
  • Medical payments
  • PIP
  • UM/UIM

But never assume all of these are included.

Read your endorsement.


Example: Period 1 Collision

Suppose Maria drives for Lyft part-time.

Her personal auto policy includes:

Collision deductible: $500

She also purchased her insurer’s rideshare endorsement.

One evening, she turns on Lyft.

She’s waiting for a request.

While driving toward a busier neighborhood, she rear-ends another vehicle.

Damage to Maria’s car:

$12,000

Damage to the other car:

$7,000

Maria needs to determine two separate issues.

Damage to the Other Vehicle

Lyft’s Period 1 liability protection may respond to a covered claim according to its applicable terms.

Damage to Maria’s Vehicle

Lyft’s Period 1 coverage doesn’t automatically provide the same contingent Collision coverage available after a ride has been accepted.

Maria therefore needs to know whether her personal rideshare endorsement extends Collision protection into Period 1.

That answer depends on her policy.


What Happens Without a Rideshare Endorsement?

Suppose another driver has:

  • Personal auto insurance
  • Collision coverage
  • Comprehensive coverage

but:

No rideshare endorsement.

The driver turns on Uber.

Before accepting a request, they crash.

Their personal insurer determines that the loss occurred while the vehicle was being used for rideshare activity and the applicable policy exclusion applies.

Uber provides applicable Period 1 third-party liability protection.

But Uber doesn’t provide Collision coverage for the driver’s own vehicle during this stage.

The driver could potentially have to pay for their own vehicle repairs.

This is one of the clearest examples of the Period 1 coverage gap.


What Happens After You Accept a Ride?

Coverage changes significantly.

Uber says that after you’ve accepted a ride request, it maintains insurance that can cover your vehicle up to its actual cash value with a $2,500 deductible, provided your personal auto policy includes Comprehensive and Collision coverage.

Lyft also states that once you’re en route to pick up a passenger or during a ride, contingent Comprehensive and Collision coverage may apply up to the vehicle’s actual cash value with a $2,500 deductible, provided you maintain Comprehensive and Collision on your personal policy.

This creates another issue:

Deductible differences.


Your Rideshare Endorsement May Help With the Deductible Gap

Suppose your personal Collision deductible is:

$500.

But the rideshare company’s applicable contingent Collision deductible is:

$2,500.

Difference:

$2,000.

Some rideshare insurance products may offer deductible-gap protection.

That could potentially reduce your out-of-pocket cost after an eligible rideshare accident.

But this feature isn’t universal.

Ask specifically whether your endorsement includes:

rideshare deductible reimbursement

or

deductible gap coverage.


What About Comprehensive Claims During Period 1?

Period 1 problems aren’t limited to collisions.

Imagine you’re online waiting for an Uber request.

A severe hailstorm damages your car.

Or someone vandalizes your vehicle.

Or a tree branch falls onto it.

Those are typically the types of losses associated with Comprehensive coverage.

But Uber says it doesn’t maintain Comprehensive or Collision coverage while you’re online but haven’t accepted a trip.

Whether your own Comprehensive coverage responds can therefore depend on your personal policy and rideshare endorsement.


What About Uninsured Motorist Coverage?

Suppose you’re waiting for a Lyft request.

Another driver crashes into you.

The other driver has no insurance.

You suffer injuries.

You may assume Lyft automatically provides Uninsured Motorist coverage during Period 1.

Don’t assume that.

NAIC notes that the TNC model framework does not universally require Period 1 coverage for categories such as:

  • Medical payments
  • PIP
  • Collision
  • Comprehensive
  • UM
  • UIM

State-specific requirements can differ.

Ask your insurer how your rideshare endorsement handles:

Uninsured Motorist (UM)

and

Underinsured Motorist (UIM)

during Period 1.


What About PIP and Medical Payments?

The same issue applies to your own injuries.

If you are hurt during Period 1, you need to know whether applicable:

  • Personal Injury Protection
  • Medical Payments coverage
  • Occupational accident protection
  • Health insurance

will respond.

The answer varies by state and policy.

This is especially important in no-fault states.

Don’t evaluate rideshare insurance solely by asking about damage to the car.


Driving for Both Uber and Lyft at the Same Time

Many rideshare drivers keep both apps active while waiting for a request.

For example:

Uber: Online

Lyft: Online

No ride accepted.

Then an accident occurs.

Which company’s policy applies?

This can create additional claims complexity.

NAIC specifically notes that many drivers may have multiple TNC apps active simultaneously.

If you multi-app, tell your insurer.

Ask whether your rideshare endorsement covers:

every rideshare platform you use.

Don’t assume an endorsement designed around one TNC automatically handles every platform.


Delivery Apps Can Create Another Coverage Issue

Maybe you drive for Uber and Lyft but also deliver food.

The insurance definitions may differ.

Your endorsement may cover:

rideshare passengers

but not necessarily:

food delivery

or other gig-driving activity.

Ask whether the endorsement applies to:

  • Uber rideshare
  • Lyft
  • Uber Eats
  • DoorDash
  • Other delivery services

You need coverage based on how you actually use the vehicle.


Don’t Hide Rideshare Driving From Your Insurer

Some drivers worry that telling their insurer about Uber or Lyft will increase their premium.

So they don’t disclose it.

That can create bigger problems after a claim.

Your insurer should know the vehicle is being used for rideshare work when required by the policy.

A denied claim involving thousands of dollars in vehicle damage can cost far more than the additional premium for appropriate coverage.


Example: $20,000 Period 1 Coverage Gap

Consider this hypothetical situation.

Daniel owns a relatively new SUV.

Vehicle value:

$38,000

Personal policy:

Comprehensive + Collision

Rideshare endorsement:

None

Daniel turns on Uber.

He hasn’t accepted a trip.

While driving toward a popular nightlife area, he loses control on a wet road and strikes a barrier.

Vehicle damage:

$20,000

No other person or vehicle is involved.

Daniel reports the accident.

His personal insurer determines that the applicable rideshare exclusion applies because he was logged into the Uber app.

Uber doesn’t provide Collision coverage because Daniel hadn’t accepted a trip.

That is exactly the type of scenario a rideshare driver should discuss with an insurer before going online.


Does Every Rideshare Endorsement Cover Period 1?

No universal rule says every endorsement provides identical protection.

A rideshare endorsement might:

  • Extend personal coverage through Period 1
  • Provide selected coverages only
  • Cover certain platforms
  • Address deductible differences
  • Exclude delivery activity
  • Operate differently under state law

Therefore, don’t buy an endorsement simply because it says:

“Rideshare Coverage.”

Ask what happens in specific scenarios.


The Most Important Question to Ask Your Insurer

Instead of simply asking, “Do I have rideshare insurance?” ask your insurer whether your policy provides Collision, Comprehensive, liability, UM/UIM, PIP or MedPay coverage when your Uber or Lyft app is switched on but you have not yet accepted a ride.

This wording identifies Period 1 precisely without relying on insurance terminology alone.

Then ask the insurer to show you the applicable endorsement or policy language.


Questions to Ask Before Driving for Uber or Lyft

  1. Does my personal policy permit rideshare driving?
  2. Do I need a rideshare endorsement?
  3. Does the endorsement cover Period 1?
  4. Is Collision covered during Period 1?
  5. Is Comprehensive covered during Period 1?
  6. What liability coverage applies?
  7. Is UM/UIM included?
  8. Does PIP or MedPay continue?
  9. Does the endorsement cover both Uber and Lyft?
  10. Can I use multiple rideshare apps simultaneously?
  11. Does it cover food delivery?
  12. What happens after I accept a passenger?
  13. Does the policy offer deductible-gap protection?
  14. What happens if the TNC denies a claim?
  15. What documentation should I provide after an accident?

Getting clear answers before driving can prevent expensive surprises.


Rideshare Insurance Checklist

Before switching the app to online:

  • Tell your insurer you drive for a TNC.
  • Confirm Uber and/or Lyft is covered.
  • Confirm Period 1 coverage.
  • Check Collision coverage.
  • Check Comprehensive coverage.
  • Check liability limits.
  • Review UM/UIM.
  • Review PIP or MedPay.
  • Compare your deductible with the TNC deductible.
  • Ask about deductible-gap protection.
  • Confirm multi-app coverage.
  • Confirm delivery coverage separately.
  • Save your policy documents.
  • Review Uber/Lyft coverage periodically.

Frequently Asked Questions

What is Period 1 in rideshare insurance?

Period 1 is when your rideshare app is on and you’re available to receive a ride request, but you haven’t yet accepted one. NAIC specifically identifies this as Period 1 in the rideshare insurance cycle.

Does my personal insurance cover Period 1?

Not necessarily. Many personal auto policies contain exclusions for rideshare, livery, commercial use, or being available for hire.

Does Uber provide insurance during Period 1?

Yes. Uber maintains third-party liability protection while you’re online and available for a trip. In many jurisdictions, its published minimum is $50,000 per person, $100,000 per accident for bodily injury and $25,000 for property damage, though state-specific rules can differ.

Does Uber provide Collision coverage during Period 1?

Uber says it does not maintain Collision or Comprehensive coverage when you’re online but haven’t accepted a trip.

Does Lyft provide Period 1 liability insurance?

Yes. Lyft currently maintains third-party liability coverage for covered Period 1 accidents when personal insurance does not apply, generally at least 50/100/25 in most markets, with jurisdictional exceptions.

Does Lyft cover damage to my car during Period 1?

Lyft’s published Period 1 protection is third-party liability. Its contingent Comprehensive and Collision coverage is described for the period after you’ve accepted a request and while completing a ride, assuming you carry those coverages personally.

What is a rideshare endorsement?

It’s an addition to an eligible personal auto policy designed to address certain coverage gaps created when the insured vehicle is used for rideshare activity.

Will a rideshare endorsement cover Period 1?

It may. Many rideshare products are designed specifically to address Period 1 gaps, but coverage differs by insurer and state.

Does rideshare insurance cover Uber and Lyft simultaneously?

Potentially, but don’t assume it does. Ask whether the endorsement covers every platform you use and whether multi-app driving affects coverage.

Do I need rideshare insurance if Uber already insures me?

It’s worth considering because Uber’s Period 1 protection does not provide the same physical-damage coverage available after you’ve accepted a trip.

Does rideshare insurance cover food delivery?

Not necessarily. Rideshare and delivery activity can be treated differently. Confirm both uses with your insurer.


Final Thoughts

The most dangerous assumption a rideshare driver can make is:

“Uber or Lyft covers me whenever the app is on.”

That’s only part of the story.

During Period 1, Uber and Lyft maintain third-party liability protection in applicable markets, but their insurance does not necessarily provide the same protection for your own vehicle that becomes available after you accept a ride. Uber explicitly states that it doesn’t maintain Collision or Comprehensive coverage while you’re online but haven’t accepted a trip.

Lyft’s published coverage similarly distinguishes between the period when you’re merely available for requests and the period after you’ve accepted a passenger.

Meanwhile, your standard personal auto policy may exclude rideshare activity once you’re available for hire.

That is the Period 1 gap.

A properly structured rideshare endorsement can potentially help address it.

Before driving, confirm exactly what your policy does when:

App off → App on → Request accepted → Passenger onboard.

If your insurer cannot clearly explain the coverage at each stage, ask for the applicable policy language.

A few minutes spent understanding Period 1 could prevent thousands of dollars in uninsured vehicle damage.

Tesla & EV Insurance Hikes: Why repair costs are driving premiums up and how to find specialized EV insurers.

Tesla & EV Insurance Hikes: Why repair costs are driving premiums up and how to find specialized EV insurers.

Electric vehicles can offer lower fuel costs, fewer traditional engine-maintenance requirements, strong performance, and increasingly sophisticated technology.

But some EV owners discover an unpleasant surprise after buying the vehicle:

Their insurance premium is significantly higher than expected.

Tesla owners can experience this particularly strongly with certain models.

The National Association of Insurance Commissioners notes that EVs can cost more to insure than comparable gasoline-powered vehicles in some consumer comparisons, with Tesla’s Model Y and Model 3 appearing among the more expensive EVs in some studies. Actual premiums still vary substantially by driver, insurer, location, vehicle, and coverage.

One major reason is relatively straightforward:

Modern EV collision claims can be expensive.

An electric vehicle may combine a high purchase price with sophisticated electronics, cameras, sensors, advanced driver-assistance systems, specialized structural components, and a large high-voltage battery.

A seemingly simple accident can therefore require much more than replacing and repainting a bumper.


Why EV Repair Costs Matter to Insurers

Insurance companies don’t price cars based only on how likely they are to crash.

They also consider:

  • How expensive repairs are
  • How frequently vehicles are totaled
  • How long repairs take
  • Parts availability
  • Vehicle values
  • Theft experience
  • Claims frequency
  • Injury costs
  • Driver profiles

Suppose one vehicle typically generates a $5,000 repair after a particular type of collision while another averages $8,000.

Even if the vehicles crash at similar rates, the second vehicle produces more expensive claims.

Over time, those claim costs can affect insurance pricing.


Are All EVs More Expensive to Insure?

No.

This is an important distinction.

You should not assume that:

EV = expensive insurance.

Insurance pricing varies greatly between individual models.

A modest electric hatchback can have a very different claims profile from a powerful luxury EV.

Two electric SUVs with similar purchase prices can also have very different premiums because insurers may experience different:

  • Repair costs
  • Theft rates
  • Parts availability
  • Total-loss frequency
  • Driver demographics

The only reliable way to know what an EV will cost you is to obtain actual insurance quotes before buying it.


Why Tesla Insurance Can Be Expensive

Tesla vehicles combine several characteristics insurers may consider.

Depending on the model, a Tesla can include:

  • High vehicle value
  • Sophisticated cameras
  • Advanced driver-assistance technology
  • Large glass panels
  • Specialized electronics
  • High-voltage battery systems
  • Manufacturer-specific repair procedures
  • Strong acceleration and performance

These characteristics don’t mean every Tesla is unusually expensive to insure.

But they can influence repair severity and insurer claims experience.

NAIC’s consumer information notes that Model Y and Model 3 have appeared among relatively expensive EVs in some insurance comparisons.


1. Modern EV Bumpers Are More Than Plastic

Consider a relatively minor front-end collision.

The visible damage might look like:

  • Cracked bumper
  • Scratched paint
  • Broken trim

But behind that bumper may be:

  • Parking sensors
  • Cameras
  • Radar equipment
  • Wiring
  • Mounting brackets
  • Driver-assistance components

The final repair may therefore include:

Replacement + paint + diagnostics + calibration.

That’s much more expensive than simply fitting a new plastic bumper.


2. ADAS Calibration Can Add to the Repair Bill

Advanced Driver Assistance Systems, or ADAS, are now common on many modern vehicles.

Features can include:

  • Automatic emergency braking
  • Adaptive cruise control
  • Lane assistance
  • Blind-spot monitoring
  • Parking assistance
  • Collision warnings
  • Camera-based vehicle detection

After certain repairs, sensors and cameras may require inspection or recalibration.

For example, replacing a windshield containing a forward-facing camera may involve:

Glass replacement

plus

camera calibration.

A front bumper repair may similarly require sensor checks.

These additional procedures can increase both labor time and repair cost.


3. Battery Assessment Can Be Complex

An EV battery pack is one of the most valuable components in the vehicle.

After a collision near the battery area, repairers may need to determine whether:

  • The battery enclosure was struck
  • High-voltage components were damaged
  • Cooling systems remain intact
  • Electrical isolation is safe
  • The pack can remain in service

That does not mean every accident requires a new battery.

In fact, improving the ability to safely repair batteries rather than automatically replacing them is an important focus of current industry research.

Thatcham Research launched an EV Insurability Blueprint in March 2026 aimed at reducing unnecessary EV write-offs and improving battery repairability.


A Minor Accident Does Not Automatically Mean a New Battery

This misconception can make EV repair discussions unnecessarily dramatic.

Imagine an EV is hit at the rear bumper.

The battery pack isn’t physically damaged.

There may be no reason to replace it.

But if an impact occurs near battery structures, proper assessment becomes important.

The insurance challenge isn’t simply that batteries are expensive.

It’s making sure repairers and insurers can accurately determine:

Is the battery safe?

Can it be repaired?

Does it need replacement?

Better diagnostics can potentially reduce unnecessary total losses.


4. Parts Can Be Expensive

Modern electric cars often contain expensive components.

Potential examples include:

  • LED or matrix headlamps
  • Camera assemblies
  • Sensors
  • Charge-port components
  • Electronic control modules
  • Specialized body panels
  • High-voltage components
  • Large glass roofs

One broken component can cost significantly more than its counterpart on a simpler older vehicle.

This can turn a visually modest accident into an expensive claim.


5. Specialized EV Repair Skills Matter

Not every repair facility is equally equipped to work on electric vehicles.

EV repairs may require technicians trained in:

  • High-voltage safety
  • Battery systems
  • Advanced diagnostics
  • ADAS calibration
  • Manufacturer repair procedures
  • Specialized structural repairs

That means some vehicles may need to be transported to approved or specially equipped repair centers.

A smaller repair network can also contribute to longer repair times.


6. Longer Repairs Can Increase the Total Claim

Suppose two vehicles each require $9,000 of actual repair work.

Vehicle A is repaired in:

10 days

Vehicle B is repaired in:

35 days

Vehicle B may generate additional insurance costs involving:

  • Rental vehicles
  • Storage
  • Additional claims administration
  • Parts delays

Insurance companies therefore care about more than the repair invoice.

They also care about how long the entire claim takes to resolve.


7. Many EVs Are Relatively High-Value Vehicles

Not every EV insurance difference comes from the battery.

Vehicle value matters too.

Suppose you’re comparing:

$55,000 EV

with

$20,000 gasoline sedan.

The insurer has significantly more physical damage exposure on the $55,000 vehicle.

Even if both cars were equally easy to repair, the higher-value car could still cost more to insure.

For a fair comparison, compare EVs with gasoline vehicles of similar:

  • Price
  • Performance
  • Size
  • Technology
  • Driver profile

8. Total-Loss Economics Can Be Difficult

Insurance companies compare the cost of repairing a vehicle with its value and applicable state total-loss rules.

Suppose an EV has a pre-loss value of:

$38,000

and estimated repairs reach:

$30,000.

The insurer may determine that repairing the vehicle is not economically reasonable.

Battery uncertainty, expensive components, and repair complexity can influence this decision.

Thatcham Research’s 2026 EV Blueprint specifically aims to keep more repairable EVs on the road by reducing unnecessary battery-related write-offs.


Tesla’s Construction Does Not Automatically Mean a Total Loss

Tesla vehicles sometimes attract claims that their structural design makes them impossible or excessively expensive to repair.

That should not be treated as a universal rule.

Repairability depends on:

  • Location of damage
  • Severity of impact
  • Model
  • Repair procedures
  • Vehicle value
  • Parts availability

The key question is not whether a Tesla uses a particular manufacturing technique.

It is whether the actual damaged components can be safely and economically repaired.


Does Tesla Offer Its Own Insurance?

Yes.

Tesla Insurance currently operates in a number of U.S. states. Tesla’s official support page lists availability in states including Arizona, California, Colorado, Florida, Illinois, Indiana, Maryland, Minnesota, Nevada, Ohio, Oregon, Tennessee, Texas, Utah, and Virginia.

Availability can change, so drivers should check Tesla’s current eligibility before relying on a static state list.

Tesla says policyholders can manage coverage and claims through the Tesla app.


How Tesla Real-Time Insurance Works

Tesla also offers a telematics-based insurance model in eligible states.

The system can use real-world driving behavior to help determine insurance pricing.

However, it does not operate the same way everywhere.

Tesla specifically states that Real-Time Insurance is not available in California, and its California product does not use Safety Score to determine monthly premiums.

This demonstrates why insurance information should always be checked at the state level.


Is Tesla Insurance Automatically Cheaper?

No.

Tesla Insurance may produce an attractive price for one driver and a poor price for another.

Your result can depend on factors such as:

  • State
  • Driving history
  • Model
  • Coverage limits
  • Deductibles
  • Mileage
  • Telematics where applicable
  • Other underwriting factors

The only meaningful comparison is your own quote.


What Is a Specialized EV Insurer?

A specialized EV insurer does not necessarily mean a company that insures only electric cars.

Instead, look for an insurer with strong experience in:

  • EV underwriting
  • High-voltage vehicle repairs
  • EV collision claims
  • Manufacturer-certified repair facilities
  • ADAS calibration
  • EV parts sourcing
  • Battery-related total-loss decisions

Tesla Insurance is one example of an EV-focused option.

But traditional insurers may also have extensive experience handling electric vehicles.

The best insurer is not necessarily the one with “EV” in its marketing.

It’s the insurer that offers the right combination of:

price + coverage + repair network + claims service.


How to Find Better Insurance for a Tesla or EV

Step 1: Get Insurance Quotes Before Buying the Vehicle

Do this before signing the sales contract.

Suppose you’re choosing between two electric SUVs.

EV A

Purchase price:

$47,000

Insurance:

$2,200 per year

EV B

Purchase price:

$48,000

Insurance:

$3,300 per year

Difference:

$1,100 annually.

Over five years, that could represent:

$5,500

before future rate changes.

Insurance should be included in your total ownership calculation.


Step 2: Compare Several Types of Insurers

Consider obtaining quotes from:

  • Your existing insurer
  • Major national insurers
  • Regional insurers
  • Independent agents
  • Manufacturer-linked insurance where available
  • Usage-based insurers

Don’t stop after receiving one expensive Tesla quote.

Different companies can price exactly the same vehicle very differently.


Step 3: Match Coverage Before Comparing Price

Suppose:

Policy A

Premium:

$2,000

Collision deductible:

$1,500

Policy B

Premium:

$2,200

Collision deductible:

$500

Policy A appears $200 cheaper.

But it requires you to accept an additional:

$1,000

of out-of-pocket risk after a qualifying collision claim.

Compare identical:

  • Liability limits
  • Collision deductibles
  • Comprehensive deductibles
  • UM/UIM coverage
  • Medical coverage
  • Rental reimbursement

Only then compare premiums.


Step 4: Ask About EV-Capable Repair Shops

Before purchasing, ask:

Does this insurer have repair facilities experienced with my specific EV?

Important questions include:

  • Can I use a manufacturer-certified body shop?
  • Does the network handle battery inspections?
  • Who performs ADAS calibrations?
  • How are parts ordered?
  • What happens if the nearest qualified repair shop is far away?
  • Is specialized towing covered?

The answers may become extremely important after a collision.


Step 5: Review OEM Parts Coverage

Some EV owners prefer original-equipment-manufacturer parts.

Ask the insurer:

  • Are OEM parts automatically used?
  • Does vehicle age affect parts selection?
  • Are aftermarket or recycled parts permitted?
  • Is an OEM endorsement available?

Two policies with similar premiums can provide very different repair experiences.


Step 6: Review Rental Reimbursement

Repair duration is particularly important with specialized vehicles.

Suppose your EV is in the shop for:

30 days.

A rental reimbursement limit of:

$30/day

may not fully cover your replacement transportation.

Compare:

  • Daily limit
  • Overall limit
  • Eligible rental period
  • Trigger for coverage

Sometimes paying slightly more for stronger rental reimbursement can be worthwhile.


Step 7: Consider GAP Insurance

A newly financed EV can create negative equity.

Example:

Current loan payoff:

$47,000

Vehicle value after total loss:

$41,000

Potential difference:

$6,000

GAP or loan/lease payoff coverage may help address qualifying financing shortfalls.

Consider it particularly when:

  • You made a small down payment
  • You financed for a long term
  • You rolled negative equity into the loan
  • You financed taxes or add-ons

Step 8: Compare New-Car Replacement Coverage

GAP and new-car replacement are different.

GAP insurance focuses primarily on the financing shortfall.

New-car replacement coverage can provide additional protection toward replacing a qualifying totaled new vehicle.

Insurer eligibility periods vary.

Ask about both rather than assuming they’re interchangeable.


Step 9: Consider Telematics

Usage-based insurance can be worth investigating for:

  • Safe drivers
  • Low-mileage drivers
  • Drivers who avoid late-night travel
  • Drivers comfortable sharing vehicle data

Tesla’s Real-Time Insurance is one example of this model in eligible states.

Traditional insurers also offer telematics programs.

Before enrolling, ask whether poor driving data can:

raise your premium

or simply:

reduce the available discount.


Step 10: Re-Shop at Renewal

Your cheapest insurer today may not be your cheapest insurer two years from now.

EV claims experience is evolving rapidly.

Repair processes improve.

Vehicle values change.

Insurers update their pricing.

Re-shop periodically, especially after:

  • A large renewal increase
  • Vehicle depreciation
  • Major mileage reduction
  • Changes in drivers
  • Improved driving history

Example: Comparing Three EV Insurance Quotes

Suppose a driver owns a relatively new electric SUV.

Insurer A

Annual premium: $2,750
Collision deductible: $500
Rental reimbursement: $50/day

Insurer B

Annual premium: $2,300
Collision deductible: $1,500
Rental reimbursement: None

Insurer C

Annual premium: $2,500
Collision deductible: $500
Rental reimbursement: $60/day
EV-certified repair network available

Insurer B has the lowest headline premium.

But Insurer C might offer better overall value because of:

  • Lower deductible
  • Rental protection
  • EV-specific repair access

This is why comparing premium only can be misleading.


Can You Reduce EV Insurance Costs?

Potentially.

Some of the same strategies that work for gasoline vehicles also apply to EVs.

Consider:

  • Comparing insurers
  • Increasing deductibles carefully
  • Bundling home and auto
  • Low-mileage discounts
  • Telematics
  • Multi-car discounts
  • Improving driving history
  • Reviewing optional coverage
  • Choosing a less expensive EV model

Some insurers also offer discounts related to alternative-fuel vehicles. NAIC consumer guidance has noted that such discounts may be available from some carriers.


Don’t Choose an EV Solely for Its Purchase Price

Consider the full ownership cost.

That includes:

Purchase price

Financing

Charging

Maintenance

Insurance

Depreciation

Suppose an EV saves you:

$700 annually in fuel

but costs:

$1,000 more annually to insure

than another vehicle you’re considering.

That changes the ownership calculation.

Insurance quotes should be obtained during vehicle shopping—not after delivery.


Are EV Insurance Costs Likely to Improve?

Potentially.

Several developments could reduce claims costs over time:

  • Better battery diagnostics
  • More repairable battery packs
  • Larger EV repair networks
  • Better parts availability
  • More trained technicians
  • Improved structural repair techniques
  • Greater insurer experience

Thatcham Research’s 2026 EV Insurability Blueprint is specifically aimed at improving repairability and reducing unnecessary write-offs, which could support more affordable insurance over time.

However, no one can guarantee that EV insurance premiums overall will fall.

Vehicle technology and repair costs continue evolving.


Questions to Ask an EV Insurer

Before purchasing a policy, ask:

  1. Do you regularly insure this exact EV model?
  2. Do you use EV-certified repair facilities?
  3. Can I choose a manufacturer-certified repair shop?
  4. How are battery inspections handled?
  5. How do you handle battery damage?
  6. Are OEM parts included?
  7. Does the policy cover ADAS calibration?
  8. What is my Collision deductible?
  9. What is my Comprehensive deductible?
  10. What rental coverage is included?
  11. Is specialized EV towing covered?
  12. Is GAP available?
  13. Is new-car replacement available?
  14. Are there EV discounts?
  15. Is telematics available?
  16. Can telematics increase my rate?
  17. Are charging cables covered after theft?
  18. What happens if parts delays keep my vehicle in the shop for weeks?

These questions reveal much more than asking whether an insurer is simply “EV-friendly.”


Common EV Insurance Mistakes

Buying the EV Before Checking Insurance

Always get quotes before purchase.

Assuming Every EV Is Expensive to Insure

Model-specific differences can be significant.

Assuming Tesla Insurance Is Automatically Cheapest

Compare several insurers.

Comparing Different Deductibles

Match coverage before comparing price.

Choosing an Excessively High Deductible

Only retain the amount of risk you can comfortably afford.

Ignoring Repair Networks

Specialized vehicles can benefit from insurers familiar with EV claims.

Forgetting GAP

Newly financed vehicles can become underwater.

Assuming Any Collision Damages the Battery

Battery damage must be assessed based on the actual accident.


EV Insurance Savings Checklist

Before buying or renewing:

  • Get quotes before buying the EV.
  • Compare at least several insurers.
  • Check Tesla Insurance where available.
  • Use an independent agent where helpful.
  • Match liability limits.
  • Match Collision deductibles.
  • Match Comprehensive deductibles.
  • Review EV repair networks.
  • Check OEM-parts provisions.
  • Review rental reimbursement.
  • Consider GAP.
  • Review new-car replacement.
  • Ask about telematics.
  • Ask about low-mileage pricing.
  • Check available EV discounts.
  • Re-shop at renewal.

Frequently Asked Questions

Why can Tesla insurance be expensive?

Potential factors include repair costs, vehicle value, cameras and electronics, ADAS calibration, parts prices, claims history, and individual driver risk. Tesla Model Y and Model 3 have appeared among relatively expensive EVs in some consumer insurance comparisons.

Are all EVs more expensive to insure?

No. Premiums differ significantly by model, insurer, driver, state, coverage, and claims experience.

Why can EV collision repairs cost more?

Modern EVs can require specialized high-voltage procedures, electronics repair, battery assessment, sensors, and calibration in addition to conventional bodywork.

Does every EV accident require battery replacement?

No. Battery replacement depends on actual damage and manufacturer procedures. Current industry research is specifically focused on improving battery repairability and reducing unnecessary replacement.

Does Tesla offer its own insurance?

Yes. Tesla Insurance is available in a number of U.S. states listed on Tesla’s current support site.

Does Tesla Insurance use driving data?

Tesla Real-Time Insurance uses driving behavior in eligible states. Tesla specifically says it is not available for premium setting in California.

Is Tesla Insurance always cheaper?

No. Tesla describes its product as competitively priced, but individual rates vary. Compare actual quotes.

Does ADAS increase repair costs?

It can. Some repairs require sensors or cameras to be inspected, replaced, or recalibrated.

Should I get GAP insurance for an EV?

Consider it when your loan payoff exceeds the vehicle’s value, particularly with small down payments or long financing terms.

Is a specialized EV insurer better?

Not automatically. Look for an insurer with competitive pricing, appropriate coverage, a strong EV repair network, and clear claims procedures.

Can telematics reduce EV insurance?

Potentially. Usage-based insurance may benefit some safe or low-mileage drivers, depending on insurer and state.

Should I change insurers if my EV renewal rises?

It’s worth comparing quotes. Make sure replacement policies have equivalent limits, deductibles, and EV repair provisions.


Final Thoughts

EV insurance costs aren’t explained by one simple factor.

The battery matters—but so do:

Vehicle value.

Sensors and cameras.

ADAS calibration.

Parts availability.

Specialized repair skills.

Repair duration.

Total-loss frequency.

For some drivers, those factors can make Tesla and other EV insurance significantly more expensive than expected.

At the same time, the industry is working to improve EV repairability. Thatcham Research’s 2026 EV Insurability Blueprint specifically aims to reduce unnecessary write-offs by improving battery assessment and repair processes.

Tesla owners also have another insurance option in states where Tesla Insurance is available, including telematics-based Real-Time Insurance in eligible jurisdictions. California is a notable exception because Tesla says Safety Score is not used there to determine monthly premiums.

The smartest strategy is therefore not simply:

Find the insurer advertising the cheapest EV insurance.

Instead:

Get multiple quotes before buying the vehicle.

Match coverage and deductibles carefully.

Check the insurer’s EV repair network.

Review OEM parts and rental coverage.

Consider GAP and replacement-cost protection.

Compare telematics if you’re comfortable using it.

A slightly higher premium can sometimes buy significantly better EV claims protection.

And a lower-cost EV insurance policy can be an excellent value when it offers the coverage and repair support your vehicle actually requires.

Non-Owner Auto Insurance: How to stay covered if you primarily use Turo or Zipcar in major cities.

Non-Owner Auto Insurance: How to stay covered if you primarily use Turo or Zipcar in major cities.

Owning a car isn’t essential for everyone.

If you live in a city such as:

New York, Boston, Chicago, Washington, D.C., San Francisco, or Seattle,

you might walk, take public transportation, cycle, or use rideshare services for most daily trips.

When you actually need a car, you may turn to services such as Turo or Zipcar.

It can be a smart lifestyle.

No monthly car payment.

No permanent parking expense.

No maintenance schedule.

No vehicle sitting unused for most of the week.

But there’s an insurance question that many car-free drivers overlook:

What protects you when you’re driving a vehicle you don’t own?

This is where non-owner auto insurance can enter the conversation.

Unfortunately, the answer isn’t as simple as buying a non-owner policy and assuming every vehicle you borrow or book is covered.

Turo and Zipcar have their own protection structures, and your personal insurance may interact with each platform differently.

Understanding those differences is essential before you get behind the wheel.


What Is Non-Owner Auto Insurance?

Non-owner car insurance is personal auto insurance designed primarily for someone who drives but doesn’t own a vehicle.

Unlike a traditional auto policy, it isn’t generally centered around one specific car that belongs to you.

Instead, its core protection is usually liability insurance attached to you as a driver, subject to the policy’s definitions and exclusions.

That can potentially protect you when you’re legally responsible for:

  • Injuring another person
  • Damaging another person’s vehicle
  • Damaging someone else’s property

while driving an eligible vehicle you don’t own.

But there’s an important limitation.

Non-owner insurance generally isn’t “full coverage” for whatever car you’re driving.

That’s especially important for Turo and other car-sharing users.


Who Might Need Non-Owner Insurance?

Non-owner coverage can be worth investigating if you:

  • Don’t own a car
  • Frequently borrow vehicles
  • Regularly rent vehicles
  • Occasionally drive friends’ cars
  • Use car-sharing services
  • Need continuous auto insurance history
  • Recently sold your vehicle but still drive
  • Need an SR-22 filing without owning a vehicle
  • Live in a city where owning a car isn’t practical

Consider someone living in downtown Chicago.

They commute by train Monday through Friday.

Twice a month, they use a car to:

  • Visit relatives
  • Buy large household items
  • Take weekend trips
  • Travel outside the city

Owning a car might make little financial sense.

But having appropriate liability protection may still matter.


What Does a Non-Owner Policy Typically Cover?

The central feature is usually:

Bodily Injury Liability

If you cause a covered accident and another person is injured, liability insurance may help pay eligible:

  • Medical costs
  • Lost income
  • Legal defense expenses
  • Settlements or judgments

up to applicable policy limits.

Property Damage Liability

If you cause an accident and damage another person’s:

  • Vehicle
  • Fence
  • Building
  • Other property

property damage liability may respond, subject to the policy.

Depending on the insurer and state, a non-owner policy may also offer or include coverage such as:

  • Uninsured motorist
  • Underinsured motorist
  • Medical payments
  • Personal Injury Protection (PIP)

Availability varies significantly.


What Non-Owner Insurance Usually Doesn’t Do

This is where misunderstandings become expensive.

A typical non-owner policy isn’t designed like the full auto policy you might buy for a vehicle you own.

It may not provide:

  • Collision coverage for the vehicle you’re driving
  • Comprehensive coverage for that vehicle
  • Towing
  • Rental reimbursement
  • Protection for personal belongings
  • Coverage for every car-sharing arrangement

This creates an important distinction.

Liability to Others

and

Damage to the Vehicle You’re Using

are separate risks.

You need to understand both.


Why Turo Makes the Question More Complicated

Turo isn’t simply the same thing as walking up to a traditional rental-car counter.

It’s a peer-to-peer vehicle-sharing platform.

Individual hosts make vehicles available to guests through the platform.

That difference matters for insurance.

Turo currently tells U.S. guests that they don’t need to have their own personal auto insurance simply to book a trip. U.S. trips include third-party liability coverage under a policy arranged by Turo, subject to the applicable terms.

However, that does not mean every possible loss is automatically fully covered.


How Turo Liability Protection Works

For U.S. guests, Turo states that trips include third-party liability insurance.

The liability protection addresses covered bodily injury or property damage that you cause to another party while operating the booked vehicle.

Turo currently explains that its U.S. third-party liability coverage is generally secondary to other applicable insurance, with state-specific exceptions.

That distinction matters enormously.

If you already have an applicable auto policy, it may potentially respond before Turo’s protection.

But there’s another complication:

Your personal policy might not cover peer-to-peer car sharing.

Turo itself warns guests to check directly with their insurer because many personal auto policies don’t cover peer-to-peer car-sharing trips.

That includes someone with a non-owner policy.

Don’t assume.

Ask.


The Most Important Question for a Non-Owner Policyholder Using Turo

Before relying on your policy, ask your insurer:

“Does my non-owner auto policy provide liability coverage when I book and drive a vehicle through Turo or another peer-to-peer car-sharing platform?”

Be specific.

Don’t simply ask:

“Does my insurance cover rental cars?”

The answer to that question may refer to conventional rental companies.

You want the insurer to understand you’re asking specifically about:

peer-to-peer vehicle sharing.

Ideally, obtain the answer in writing or locate the applicable policy provision.


Turo Protection Plans and Vehicle Damage

Third-party liability is only part of the problem.

What happens if you damage the Turo host’s vehicle?

Turo offers guests optional protection plans designed to limit their contractual financial responsibility for eligible physical damage to the booked vehicle. Turo emphasizes that, in most U.S. states, these protection plans are contractual limitations of responsibility rather than insurance policies themselves.

That’s an important distinction.

Depending on the selected plan, your potential out-of-pocket exposure for eligible physical damage can differ substantially.


What If You Decline Turo’s Physical Damage Protection?

This decision deserves careful consideration.

Turo’s current U.S. guest terms state that if you decline physical-damage protection, your contractual financial responsibility for damage to the booked vehicle isn’t limited by a Turo protection plan.

For example, imagine booking a:

$45,000 SUV.

You decline the available protection because you assume:

“I have non-owner insurance.”

You total the vehicle.

Then you discover your non-owner policy provides liability protection but doesn’t provide applicable physical damage coverage for the Turo vehicle.

That could create substantial personal exposure.

Turo states that guests declining protection can be responsible for vehicle damage up to the vehicle’s actual cash value plus qualifying related costs, minus applicable insurance proceeds and salvage value.

That’s why this issue deserves attention before booking.


Don’t Assume Your Credit Card Covers Turo

Many consumers associate rental cars with credit-card collision protection.

They may think:

“My credit card covers rentals, so I’ll decline Turo protection.”

That’s risky.

Peer-to-peer car sharing may be treated differently from traditional rental vehicles.

Turo itself warns that credit-card coverage is unlikely to apply to a Turo trip and advises guests to verify directly with the card issuer.

Before relying on a credit card, ask:

“Does my card’s rental-car benefit explicitly cover peer-to-peer rentals booked through Turo?”

Don’t rely on assumptions.


How Zipcar Insurance Works

Zipcar operates differently.

Members book vehicles from the Zipcar fleet for specific periods.

Zipcar currently states that members complying with its membership agreement receive physical damage protection for the Zipcar vehicle and secondary third-party liability coverage.

For compliant members, Zipcar says third-party liability generally meets the minimum financial-responsibility limits required by the jurisdiction where an accident occurs and is generally secondary to other applicable coverage unless the law requires otherwise.

That word minimum deserves attention.


State-Minimum Liability May Not Be Enough for You

Imagine causing a serious accident.

The other vehicle is a new luxury SUV.

Several people are injured.

Total claims reach:

$350,000.

If the only liability protection available to you is a relatively low statutory minimum, your financial exposure could potentially exceed the available insurance limits.

This is one reason some city residents consider maintaining their own non-owner liability policy with higher limits.

But again:

You must confirm that your particular non-owner policy applies to Zipcar use.


Zipcar’s Vehicle Damage Protection

Zipcar currently says compliant members are protected against physical damage to the Zipcar vehicle, but a damage fee of up to $2,500 may apply under its standard arrangement.

Zipcar also offers optional damage protection that can reduce that potential fee.

Its current published options include:

Zipcar ProtectionPotential Damage Fee
StandardUp to $2,500
PlusUp to $375
Premium$0

Eligibility and terms apply, and the options can change.

Importantly, Zipcar explains that purchasing its damage protection changes the member’s potential damage fee—it does not change the underlying insurance coverage.


Turo vs. Zipcar: Why You Shouldn’t Treat Them the Same

The services may feel similar from a consumer perspective:

Open app → choose car → drive.

Insurance-wise, however, they’re different.

FeatureTuroZipcar
Basic modelPeer-to-peer sharingMembership car sharing
Own insurance required to book?NoMembership terms apply
Third-party liabilityIncluded subject to trip termsIncluded subject to membership terms
Other applicable personal insuranceMay be primary in many situationsGenerally considered before Zipcar’s secondary protection
Vehicle damageProtection plans availableZipcar physical damage arrangement
User financial responsibilityDepends heavily on selected protectionDamage fee may apply
Non-owner policy compatibilityMust verifyMust verify

Turo’s U.S. liability arrangement and protection-plan structure are detailed in its guest protection documentation, while Zipcar’s structure is governed by its membership contract and insurance terms.


Why Non-Owner Insurance Can Still Be Valuable

You might reasonably ask:

“If Turo and Zipcar already provide some protection, why would I buy non-owner insurance?”

There are several potential reasons.


Benefit #1: Higher Personal Liability Limits

Platform-provided liability may not necessarily provide the amount of protection you personally want.

Suppose you purchase a non-owner policy with:

$250,000/$500,000 bodily injury liability

and

$100,000 property damage liability.

If the policy applies to the car-sharing arrangement, you may have substantially greater personal liability protection than relying solely on a low statutory minimum.

Exact interaction between policies depends on policy language and state law.


Benefit #2: Protection When Borrowing Cars Outside an App

Your driving life may involve more than Turo and Zipcar.

Maybe once a month you borrow:

  • Your sister’s car
  • A friend’s SUV
  • Your roommate’s vehicle
  • A relative’s car while visiting another city

A properly structured non-owner policy can potentially provide liability protection in certain situations involving eligible non-owned vehicles.

Again, exclusions matter.


Benefit #3: Maintaining Continuous Insurance History

Suppose you sell your car when moving from suburban New Jersey into Manhattan.

You spend three years without owning a vehicle.

Then you move somewhere where you need a car again.

A long period without personal auto insurance can sometimes affect how insurers evaluate you when you return to the market.

Maintaining a non-owner policy can provide continuous insurance history while you remain car-free.

Whether that produces a pricing benefit depends on the insurer and state.


Benefit #4: SR-22 Requirements

Some drivers must provide proof of financial responsibility following certain driving violations.

If you don’t own a vehicle but need an SR-22 filing, a non-owner policy may sometimes be used to satisfy the insurance requirement.

Requirements vary significantly by state.

An SR-22 isn’t itself insurance.

It’s generally a certificate filed by an insurer demonstrating that you carry required liability coverage.


Benefit #5: More Consistent Protection Across Different Cars

A city resident might use:

Zipcar this week.

A friend’s car next week.

A traditional rental on vacation.

A family member’s vehicle during the holidays.

Platform-specific protection changes every time.

A non-owner policy can potentially create a more consistent layer of personal liability coverage—but only for uses and vehicles that actually qualify under the policy.

That’s the critical limitation.


Non-Owner Insurance Doesn’t Automatically Cover Cars in Your Household

This is another common issue.

Suppose you don’t own a car.

But your spouse or roommate owns one, and you drive it regularly.

You might think:

“I’ll just buy non-owner insurance.”

That may not be appropriate.

Non-owner policies often contain restrictions involving vehicles:

  • Owned by household members
  • Furnished for your regular use
  • Available to you frequently

If you regularly drive one particular household vehicle, you may need to be listed appropriately on that vehicle’s insurance policy instead.

Ask the insurer.


Occasional Use vs. Regular Use

Consider two situations.

Situation A

You borrow your brother’s car twice per year.

Situation B

Your roommate owns a car and lets you drive it to work four days per week.

Those aren’t necessarily treated the same way.

A vehicle that’s regularly available for your use can fall outside the purpose of non-owner coverage.

This is another reason to disclose your actual driving habits when obtaining a quote.


What About Traditional Rental Cars?

Non-owner insurance may potentially provide liability protection when driving eligible traditional rental vehicles.

But it usually shouldn’t be assumed to provide physical damage protection to the rental car.

At a traditional rental counter, you may encounter products such as:

  • Collision/Loss Damage Waiver
  • Supplemental Liability Insurance
  • Personal Accident Insurance
  • Personal Effects Coverage

If your non-owner policy already provides adequate applicable liability protection, you may not need duplicate liability coverage.

But vehicle damage is a separate question.


Four Layers to Check Before Every Car-Sharing Trip

Rather than asking:

“Am I insured?”

ask four separate questions.

Layer 1 — Third-Party Liability

What happens if I injure someone or damage another person’s property?

Layer 2 — Damage to the Car I’m Driving

Who pays if I damage the Turo or Zipcar vehicle?

Layer 3 — My Own Injuries

Do I have applicable:

  • PIP
  • Medical payments
  • Health insurance
  • Other protection?

Layer 4 — Uninsured/Underinsured Motorists

What happens if another driver causes the accident but has insufficient insurance?

These coverages don’t necessarily come from the same policy.


Example: Turo Weekend Trip

Imagine Maya lives in Brooklyn and doesn’t own a vehicle.

She has a non-owner policy.

For a weekend trip, she books a Turo vehicle.

Before driving, she checks:

Non-owner liability:
Her insurer confirms in writing whether its liability coverage applies to Turo.

Turo liability:
She reviews the liability protection included with the reservation.

Vehicle damage:
She determines whether her personal policy provides physical damage protection. If not, she evaluates Turo’s protection plans.

Credit card:
She checks whether the card benefit covers peer-to-peer car sharing rather than assuming it does.

That’s a much safer approach than relying on the phrase:

“I already have insurance.”


Example: Zipcar Commuter

David lives in Boston.

He doesn’t own a car.

Twice per week, he uses Zipcar for meetings outside the city.

He purchases a non-owner policy primarily for higher personal liability limits.

Before relying on it, he confirms that his insurer covers his use of Zipcar.

He also reviews Zipcar’s current damage-fee structure.

Zipcar states that compliant members may face up to a $2,500 vehicle damage fee under standard protection, with optional protection available to reduce or eliminate that fee.

David therefore evaluates:

His personal liability exposure

separately from

his potential Zipcar damage fee.

That’s exactly how these decisions should be approached.


What If You Use Both Turo and Zipcar?

This is increasingly realistic for city residents.

You might use:

Zipcar for a three-hour IKEA trip

and

Turo for a four-day weekend vacation.

Don’t assume your insurance works identically for both.

Ask your non-owner insurer specifically:

“Does this policy cover liability while I’m using Zipcar?”

and separately:

“Does this policy cover liability while I’m using Turo?”

Then ask:

“Does it provide any physical damage coverage for either vehicle?”

The answers may be different.


What Happens After an Accident?

If you’re involved in a crash while using a car-sharing vehicle:

  1. Check for injuries and contact emergency services when necessary.
  2. Follow local legal requirements for reporting the accident.
  3. Notify the car-sharing platform promptly.
  4. Notify your personal insurer if potentially applicable.
  5. Document the vehicles and accident scene safely.
  6. Keep reservation and trip records.
  7. Don’t make assumptions about which policy is primary.

Turo requires guests to cooperate with claims involving applicable personal insurance, while Zipcar’s membership contract similarly requires members to comply with incident-reporting and assistance requirements.


Don’t Violate the Platform’s Terms

Insurance protection can depend on complying with the platform’s rules.

Examples of potentially problematic conduct can include:

  • Unauthorized drivers
  • Prohibited vehicle use
  • Driving outside permitted areas
  • Reckless use
  • Failing to report an accident
  • Allowing another person to drive without authorization

Turo specifically warns that violating its Terms of Service or engaging in prohibited use can void the contractual limitation of financial responsibility offered by its protection plans.

Zipcar likewise states that members who fail to comply with the membership contract may lose applicable protections and become responsible for accident-related costs.

Read the rules before handing someone else the keys.


The $100,000 Mistake City Drivers Should Avoid

Consider this hypothetical example.

You don’t own a car.

You book a high-value vehicle through a peer-to-peer platform.

You have:

Non-owner liability insurance.

You decline the platform’s physical-damage protection because you think your policy covers everything.

You total the car.

Then you discover:

Your non-owner policy covers liability to other people but doesn’t cover physical damage to the booked vehicle.

The vehicle’s value:

$70,000.

Related towing, appraisal and administrative costs add more.

That’s why the question:

“Do I have insurance?”

isn’t specific enough.

Ask:

“Who pays for THIS vehicle if I destroy it?”


How Much Liability Coverage Should You Consider?

There isn’t one correct limit for everyone.

State minimums can be relatively low compared with the cost of a severe accident.

Consider your:

  • Income
  • Savings
  • Assets
  • Driving frequency
  • Risk tolerance
  • State requirements

Then compare available liability limits.

For example, you might obtain quotes for:

100/300/100

versus

250/500/100

where available.

Higher limits generally cost more, but they provide a larger financial buffer after a serious covered accident.


Can You Buy an Umbrella Policy Without Owning a Car?

Potentially, depending on the insurer.

Personal umbrella policies commonly require underlying liability insurance meeting specified minimum limits.

A person who doesn’t own a vehicle but maintains non-owner auto liability may be able to structure an umbrella arrangement with some insurers.

But availability and requirements vary.

If you have significant assets and frequently use non-owned vehicles, ask an insurance professional whether your non-owner auto coverage can satisfy the insurer’s underlying auto-liability requirement.


How Much Does Non-Owner Insurance Cost?

There is no meaningful universal price.

Premiums can depend on:

  • State
  • City/ZIP code
  • Age
  • Driving history
  • Claims history
  • Liability limits
  • Required filings
  • Insurer
  • Other rating factors permitted by state law

Instead of searching for a national average and assuming that’s what you’ll pay, obtain several quotes.

The cheapest policy isn’t necessarily the best policy for a frequent Turo or Zipcar user.

Compatibility matters.


Questions to Ask Before Buying a Non-Owner Policy

Tell the agent exactly how you drive.

Ask:

  1. Does this policy cover Turo use?
  2. Does it cover Zipcar use?
  3. Does it cover traditional rental cars?
  4. Does it cover borrowed vehicles?
  5. What liability limits are available?
  6. Is liability primary or excess?
  7. Does the policy provide physical damage protection?
  8. Are peer-to-peer vehicles excluded?
  9. Are car-sharing vehicles excluded?
  10. Are vehicles available for my regular use excluded?
  11. What UM/UIM coverage is included?
  12. Is PIP or MedPay available?
  13. Can the policy support an SR-22 if needed?
  14. Will the policy maintain continuous insurance history?
  15. What happens if I later buy a car?

The first two questions are particularly important for app-based drivers.


Turo + Non-Owner Insurance Checklist

Before booking:

  • Confirm non-owner policy applies to Turo.
  • Check your liability limits.
  • Review Turo’s included liability protection.
  • Determine which coverage is primary.
  • Review the available Turo protection plan.
  • Determine your maximum physical-damage responsibility.
  • Check whether your credit card actually covers peer-to-peer sharing.
  • Confirm all drivers are authorized.
  • Photograph the vehicle before the trip.
  • Read prohibited-use rules.

Turo specifically recommends taking pre-trip photos to document the vehicle’s condition.


Zipcar + Non-Owner Insurance Checklist

Before driving:

  • Confirm your non-owner policy applies to Zipcar.
  • Check your personal liability limits.
  • Review Zipcar’s liability terms.
  • Check your current damage-fee exposure.
  • Consider optional damage protection.
  • Make sure every driver is authorized.
  • Inspect the vehicle before leaving.
  • Report existing damage.
  • Follow the membership agreement.

Zipcar currently allows eligible members to purchase additional damage protection either through a recurring option or on a per-trip basis, depending on the protection selected.


Non-Owner Policy vs. Platform Protection

ProtectionNon-Owner PolicyTuro/Zipcar Protection
Personal liabilityUsually core purposePlatform-specific
Damage to booked carOften limited/not includedPlatform options may apply
Borrowed friend’s carPotentiallyNo
Traditional rentalPotentiallyNo
Continuous insurance historyYesNo
Coverage outside bookingsPotentiallyNo
UM/UIMMay be availableState/platform dependent
PIP/MedPayState/policy dependentState/platform dependent
Applies automatically to car sharingNever assumeOnly during eligible booking

The biggest advantage of non-owner insurance is that it can potentially follow you, rather than being limited to a single app reservation.

Its biggest limitation is that it doesn’t automatically turn every borrowed vehicle into a fully insured vehicle.


Is Non-Owner Insurance Worth It for Turo Users?

It can be.

Consider it more seriously if you:

  • Use Turo frequently
  • Borrow other vehicles
  • Rent traditional cars
  • Want higher liability limits
  • Want continuous insurance history
  • Have significant assets to protect

But confirm the insurer explicitly allows the types of vehicles you use.

Turo itself tells guests that many personal insurance policies don’t cover peer-to-peer car sharing and recommends confirming coverage with the insurer.


Is Non-Owner Insurance Worth It for Zipcar Users?

Potentially.

Zipcar currently provides compliant members with secondary third-party liability protection meeting applicable jurisdictional minimum requirements.

A compatible non-owner policy could potentially provide higher personal liability limits and coverage for other eligible non-owned vehicles outside your Zipcar bookings.

But you must confirm how the policies interact.


When You Probably Don’t Need a Non-Owner Policy

It may be less useful if:

  • You almost never drive.
  • You only use vehicles with protection you’re comfortable relying upon.
  • You don’t borrow cars.
  • You don’t need continuous insurance history.
  • Another policy already appropriately covers you.

However, don’t base the decision solely on frequency.

Even someone who drives only six times per year can cause a serious accident.

The relevant question is:

What financial exposure are you comfortable retaining?


Frequently Asked Questions

What is non-owner auto insurance?

It’s auto insurance primarily designed for drivers who don’t own a vehicle but need personal liability protection while operating certain eligible vehicles they don’t own.

Does non-owner insurance cover Turo?

Possibly, but never assume it does. Turo warns that many personal insurance policies don’t cover peer-to-peer car sharing and recommends verifying directly with the insurer.

Does non-owner insurance cover Zipcar?

It may, depending on the insurer and policy. Ask specifically about Zipcar rather than simply asking about “rental cars.”

Does Turo require guests to have personal insurance?

No. Turo currently says guests don’t need their own personal auto insurance to book a trip, and trips include applicable third-party liability protection.

Does Turo cover damage to the host’s vehicle?

Turo offers protection plans that can contractually limit a guest’s responsibility for eligible physical damage. In most U.S. states, Turo explains that these guest protection plans themselves are not insurance.

Does Zipcar include insurance?

Zipcar currently provides compliant members with physical damage protection for the Zipcar vehicle and secondary third-party liability protection, subject to its membership contract.

How much could I owe if I damage a Zipcar?

Under Zipcar’s currently published U.S. standard damage protection, a damage fee of up to $2,500 may apply. Optional protection can reduce or eliminate that amount for eligible members.

Does my credit card cover Turo?

Don’t assume it does. Turo specifically warns that credit-card rental protection is unlikely to cover a Turo trip and recommends checking with the card issuer.

Does non-owner insurance cover the car I’m driving?

Non-owner policies primarily provide liability coverage. Physical damage to the vehicle itself may not be included. Check the actual policy.

Can non-owner insurance help maintain insurance history?

Yes, maintaining a policy can prevent a period in which you carry no personal auto insurance, although how insurers use prior-insurance history varies.


Final Thoughts

The rise of car sharing has created a new type of driver:

Someone who drives regularly but doesn’t own a car.

For people living in major cities, that can make perfect financial sense.

You might take the subway Monday through Friday, use Zipcar for errands on Saturday, book Turo for a weekend getaway, and occasionally borrow a relative’s vehicle.

But your insurance needs don’t disappear simply because there’s no car registered in your name.

A non-owner auto insurance policy can potentially provide an important personal liability layer.

The critical word is:

potentially.

Don’t assume that a policy designed for borrowed or rented cars automatically covers every car-sharing platform.

Turo specifically warns that many personal auto policies don’t cover peer-to-peer car sharing.

Zipcar, meanwhile, currently provides compliant members with its own physical damage arrangement and secondary third-party liability protection, but its standard liability protection generally corresponds to jurisdictional minimum requirements.

The safest approach is to examine three things separately:

Your personal liability coverage.

The platform’s liability protection.

Protection for physical damage to the vehicle you’re using.

If you regularly switch between Turo, Zipcar, traditional rentals and borrowed cars, tell your insurer exactly that.

Then ask them to confirm which situations your non-owner policy covers.

Because in a car-sharing world, not owning a car doesn’t necessarily mean you don’t need auto insurance.

Daycare & Social Services Insurance: Specialized risk management for child care centers in 2026.

Daycare center director reviewing specialized business insurance and child safety procedures.

Quick Takeaway

A child care center isn’t an ordinary small business.

Every day, operators take responsibility for children while managing employees, facilities, playgrounds, food, transportation, personal information and interactions with parents.

That creates risks involving:

injuries + supervision + allegations of abuse or misconduct + property + employees + transportation + cyber incidents + professional services.

These risks have become significant enough that the NAIC has a dedicated Child Care Insurance Working Group in 2026. Its current work includes examining cost drivers and limitations affecting liability insurance for child care and child social-service organizations, including child-placing agencies and group foster homes.

The central lesson for operators is simple:

A standard general liability policy alone may not address every major exposure faced by a daycare or social-service organization.

Why Daycare Insurance Is Different

Consider a typical child care center.

At 9:00 a.m., it may have:

60 children

12 employees

multiple classrooms

an outdoor playground

a commercial kitchen

parents arriving and leaving

and possibly:

a passenger van.

By lunchtime, employees may have:

  • Prepared food
  • Changed diapers
  • Administered medication
  • Supervised outdoor play
  • Helped children use playground equipment
  • Managed allergies
  • Communicated with parents
  • Recorded attendance
  • Stored personal information

Each activity creates a different type of risk.

Childcare.gov notes that licensed child care centers generally must meet health and safety requirements and are monitored for compliance.

Insurance needs to be evaluated alongside those operational responsibilities.

Start With General Liability Insurance

Commercial general liability is usually a fundamental coverage to consider.

It may address certain claims involving:

  • Bodily injury
  • Third-party property damage
  • Premises liability
  • Certain personal and advertising injuries

Imagine a parent enters the daycare.

Water has been spilled near the entrance.

The parent slips, falls and suffers an injury.

That is a conventional premises-liability exposure.

But child care creates more complicated scenarios.

What If a Child Is Injured?

Imagine a four-year-old falls from playground equipment and breaks an arm.

The parents allege:

inadequate supervision.

Now the center could face:

medical expenses + legal defense + potential liability claim.

Whether and how insurance responds depends on the facts and policy wording.

This is why operators should understand not only their general liability limit but also:

exclusions + endorsements + deductibles + defense-cost provisions.

Abuse and Molestation Coverage Deserves Special Attention

This is one of the most sensitive—and important—areas of child care risk management.

A daycare or social-service organization may face allegations involving:

  • Physical abuse
  • Sexual abuse
  • Inappropriate contact
  • Negligent supervision
  • Negligent hiring
  • Failure to report
  • Improper employee conduct

Do not assume a standard general liability policy automatically provides adequate protection for these allegations.

Ask specifically about:

Abuse and Molestation Liability

or equivalent coverage.

Check the Limit Carefully

Suppose your declarations page says:

General Liability: $1 million

but your abuse-related coverage has:

$250,000 sublimit.

Those aren’t equivalent.

For sensitive liability exposures, operators should identify:

Per-claim limit

Aggregate limit

Sublimit

Deductible/retention

Defense-cost treatment

Exclusions

The headline general-liability limit doesn’t tell the entire story.

Background Checks Are Part of Risk Management

Insurance is only one layer of protection.

Federal requirements make staff screening particularly important.

Childcare.gov says states and territories must ensure staff in licensed child care programs undergo required state and federal criminal background checks. These include an FBI fingerprint-based criminal history check, the National Sex Offender Registry, and specified state criminal, sex-offender, and child-abuse-and-neglect registry searches.

Required background checks generally must be requested before employment and repeated at least every five years.

But:

Background check ≠ complete risk management.

Centers also need appropriate:

supervision + training + policies + reporting procedures.

Staff Training Matters

Licensed child care programs operate under state or territory requirements concerning staff qualifications and training.

Childcare.gov notes that requirements vary by jurisdiction and can depend on the care setting and ages of children served.

Training may address areas such as:

  • CPR
  • First aid
  • Safe sleep
  • Emergency procedures
  • Medication
  • Child supervision
  • Sanitation
  • Emergency response

A center should maintain records showing required training has actually been completed.

Create Clear Supervision Procedures

Many serious incidents begin with a simple question:

“Who was supposed to be watching the child?”

Your center should have clear procedures covering:

Classrooms

Playgrounds

Bathrooms

Nap periods

Field trips

Pickup and drop-off

Transportation

Transitions between rooms.

Childcare.gov emphasizes that licensed programs must maintain sufficient adult supervision consistent with applicable requirements.

Staff-to-Child Ratios Matter

States and territories establish their own licensing requirements.

Don’t rely on a generic internet recommendation.

Verify:

your state’s required ratios

and whether those ratios change according to:

child age + activity + facility type.

Insurance does not replace regulatory compliance.

Professional Liability May Be Relevant

Daycare operators may hear:

“You need liability insurance.”

But which liability?

General liability usually focuses heavily on bodily injury and property-damage exposures.

Professional liability can address certain allegations involving professional services.

For some child care and social-service organizations, professional liability may be important where staff provide services such as:

  • Counseling
  • Case management
  • Behavioral support
  • Educational services
  • Assessments
  • Social services

The need depends heavily on the organization.

Social-Service Organizations Can Face Broader Risks

A daycare and a social-service agency aren’t identical.

A social-service organization might provide:

foster-care services

residential services

counseling

youth programs

community support

case management.

These activities can create substantially different liability exposures.

The NAIC’s 2026 Child Care Insurance Working Group specifically includes insurance issues involving child-placing agencies, group foster homes and other child social-service organizations in its work.

This is one reason a generic small-business insurance package may be inadequate.

Commercial Property Insurance

Now consider the physical center.

You may need to protect:

  • Building
  • Furniture
  • Computers
  • Classroom equipment
  • Toys
  • Kitchen equipment
  • Outdoor equipment
  • Supplies
  • Security systems

Imagine a fire damages several classrooms overnight.

Property insurance may help repair or replace covered property, subject to policy terms.

But don’t stop there.

Ask:

How will we pay expenses while the center is closed?

Business Interruption Insurance

Suppose a covered fire closes your daycare for eight weeks.

Children cannot attend.

Parents stop paying tuition.

But you still have:

rent + payroll + insurance + loan payments + other continuing expenses.

Business-income coverage can potentially help with qualifying lost income and continuing expenses following a covered loss.

Review:

Covered causes of loss

Waiting period

Business-income limit

Period of restoration

Extra expense

Exclusions.

Extra Expense Can Be Particularly Important

For a daycare, reopening quickly can be critical.

Imagine your building suffers serious water damage.

Instead of closing for three months, you temporarily relocate to another properly approved facility.

That might create expenses for:

temporary rent + equipment + transportation + communications.

Depending on the policy, extra expense coverage may help with qualifying additional costs incurred to continue operations.

Playground Liability

The playground deserves its own risk review.

Check:

  • Equipment condition
  • Surface condition
  • Age appropriateness
  • Inspection procedures
  • Maintenance records
  • Supervision
  • Fencing
  • Gates
  • Fall hazards

Childcare.gov says building-safety requirements for licensed programs include attention to structures, outdoor play spaces, playgrounds and fire safety.

Keep documented inspection and maintenance records.

Food and Allergy Risks

Many centers provide:

breakfast + lunch + snacks.

That creates additional exposure.

A child may have:

  • Peanut allergy
  • Milk allergy
  • Egg allergy
  • Other dietary restriction

An employee accidentally serves the wrong food.

The child experiences a severe reaction.

Centers should have clear procedures for:

allergy documentation + food preparation + staff communication + emergency response + medication.

Childcare.gov notes that licensed child care health and safety requirements address children’s health, illness and the storage and administration of medication.

Medication Administration Creates Another Risk

Some children need medication during the day.

Potential problems include:

wrong child

wrong medication

wrong dose

wrong time.

Your center should follow applicable licensing requirements and maintain written medication procedures.

Check whether your insurance program appropriately addresses allegations arising from medication administration.

Transportation Can Change Your Insurance Needs

Does your daycare operate:

a van?

Perhaps you transport children:

from school → daycare

or:

daycare → field trip.

Now you have a commercial auto exposure.

Potential claims could involve:

  • Vehicle accidents
  • Passenger injuries
  • Loading/unloading
  • Driver negligence
  • Children left in vehicles
  • Vehicle maintenance

A personal auto policy should not be assumed to cover daycare transportation operations.

Hired and Non-Owned Auto Exposure

Maybe your daycare doesn’t own a vehicle.

But employees occasionally use:

their own cars

for business activities.

That can create a different exposure commonly addressed through:

Hired and Non-Owned Auto Liability, depending on circumstances and policy structure.

Discuss actual transportation practices with your insurance professional rather than saying:

“We don’t own a van, so we don’t have auto exposure.”

Workers’ Compensation

Daycare employees can be injured too.

A worker might:

hurt their back lifting a child

slip on a wet floor

suffer an injury moving equipment

be injured during an emergency.

Workers’ compensation requirements vary by state, but employers should evaluate applicable obligations and coverage.

Don’t focus exclusively on injuries to children.

Your employees are an important part of the risk picture.

Employment Practices Liability

A daycare is also an employer.

Employees may allege:

  • Discrimination
  • Harassment
  • Retaliation
  • Wrongful termination
  • Other employment-related misconduct

Employment Practices Liability Insurance (EPLI) can potentially address qualifying employment claims.

As your center grows from:

5 employees → 20 → 50,

employment-related exposure can increase substantially.

Cyber Insurance Is Increasingly Relevant

Modern child care centers store significant information electronically.

That may include:

  • Parent names
  • Addresses
  • Children’s information
  • Employee information
  • Payment information
  • Emergency contacts
  • Medical or allergy information
  • Attendance records
  • Photos

Many centers also use:

parent apps + digital payment systems + cloud software + electronic enrollment systems.

A cyber incident could expose sensitive information or disrupt operations.

Cyber insurance may therefore be worth considering.

Think About Ransomware

Imagine arriving Monday morning and seeing:

Your daycare-management system is inaccessible.

You cannot easily access:

attendance records

parent contacts

billing information

or other operational data.

Cyber insurance may potentially address qualifying:

incident response + data restoration + business interruption + privacy liability

costs, depending on the policy.

But insurance should accompany good cybersecurity—not replace it.

Protect Parent and Child Information

Basic safeguards can include:

Multi-factor authentication

Unique employee accounts

Strong passwords

Regular software updates

Restricted access

Secure backups

Employee cybersecurity training.

Employees shouldn’t have access to sensitive records simply because they work at the center.

Use:

need-to-know access.

Emergency Planning Is More Than an Insurance Issue

Licensed child care programs must meet minimum emergency-planning requirements.

A center should plan for situations such as:

  • Fire
  • Severe weather
  • Power failure
  • Medical emergency
  • Security incident
  • Evacuation
  • Shelter-in-place situations

Your plan should identify:

Who supervises which children?

Who contacts parents?

Where do children go?

How is attendance verified?

How are medications handled?

Who calls emergency services?

Document Incidents Properly

Suppose a child falls and receives a minor cut.

It seems insignificant.

Six months later, the parents make a claim alleging a more serious injury.

What records do you have?

Maintain appropriate incident documentation consistent with legal and licensing requirements.

A useful incident record may capture:

Date + time + location + people involved + factual description + witnesses + immediate response + parent notification.

Avoid speculation.

Document facts.

Parent Agreements Matter

Written agreements can help establish expectations.

Childcare.gov recommends clear contracts covering matters such as:

  • Schedule
  • Fees
  • Hours
  • Services
  • Closures
  • Termination
  • Authorized pickup adults

It also notes that providers should maintain written policies addressing illness, discipline, emergencies, field trips and transportation.

These policies support both good operations and risk management.

Authorized Pickup Procedures Are Critical

Imagine someone arrives and says:

“I’m the child’s uncle. I’m picking her up today.”

Should the employee release the child?

Not without following your procedures.

Maintain clear records identifying:

authorized pickup persons.

Train employees to follow the process consistently—even when someone becomes impatient.

Field Trips Create Additional Exposure

Taking children outside the center can change the risk environment.

A field trip may involve:

transportation + public locations + unfamiliar hazards + larger crowds + supervision challenges.

Before field trips:

  • Obtain required permissions
  • Verify staffing
  • Review transportation
  • Carry emergency information
  • Establish head-count procedures
  • Review insurance implications

Again, applicable state requirements should be followed.

Umbrella or Excess Liability

Suppose your center has:

$1 million general liability coverage.

Is that enough?

There is no universal answer.

A serious child-injury claim can potentially become expensive.

An umbrella or excess-liability policy can provide additional limits above specified underlying policies, subject to its terms.

But verify which underlying exposures the umbrella actually follows.

Don’t assume it automatically extends every specialized coverage.

One of the Biggest Questions: Does the Umbrella Cover Abuse Claims?

Suppose:

General Liability: $1 million

Abuse & Molestation: $1 million

Umbrella: $5 million.

It may be tempting to conclude:

Total abuse protection = $6 million.

Not necessarily.

Check whether the umbrella follows the abuse-related coverage.

Specialized exclusions can create unexpected gaps.

Directors & Officers Insurance for Nonprofit Centers

Some child care and social-service organizations operate as nonprofits.

They may have:

boards + directors + officers + donors + grants.

Directors & Officers (D&O) liability can potentially address certain claims involving management decisions and governance.

This can be particularly relevant for larger nonprofit organizations.

Crime and Employee Dishonesty

Daycares also handle:

tuition payments + payroll + bank accounts + purchasing.

That creates financial crime exposure.

Commercial crime coverage can potentially address qualifying losses involving:

  • Employee theft
  • Forgery
  • Funds-transfer fraud
  • Certain computer fraud

Again, coverage depends on policy terms.

Why Insurance Availability Matters in 2026

This topic is particularly timely.

The NAIC’s Child Care Insurance Working Group has a specific 2026 mandate to evaluate cost drivers and limitations negatively affecting the availability of liability insurance products for child care services in both admitted and non-admitted markets.

The group is also examining potential ways to:

expand insurer participation + improve availability + address liability-market limitations.

That tells operators something important:

Child care insurance availability is currently a genuine regulatory concern—not merely a marketing talking point.

Don’t Choose Insurance Based Only on Premium

Imagine two quotes.

Policy A

$6,000/year

Policy B

$9,000/year

Policy A appears better.

But then you discover:

Policy A

has a major abuse exclusion.

Policy B

includes specialized abuse coverage with meaningful limits.

The cheaper policy isn’t necessarily the better value.

Compare:

coverage → exclusions → limits → deductibles → endorsements → insurer → premium.

Not premium alone.

Ask About Claims-Made Coverage

Certain professional or specialized liability coverages may be written on a:

claims-made basis.

If so, understand:

Retroactive date

Policy period

Reporting requirements

Extended reporting period.

A claim involving a child or former client could potentially emerge long after the alleged event.

Don’t cancel claims-made coverage without understanding the consequences.

Daycare Insurance Checklist for 2026

Before purchasing or renewing coverage:

  • Confirm general liability coverage.
  • Review abuse and molestation coverage.
  • Check abuse-related sublimits.
  • Review professional liability.
  • Confirm commercial property coverage.
  • Review business-income protection.
  • Check extra-expense coverage.
  • Review workers’ compensation requirements.
  • Consider EPLI.
  • Review cyber liability.
  • Confirm commercial auto where applicable.
  • Consider hired/non-owned auto exposure.
  • Review umbrella/excess liability.
  • Determine whether umbrella coverage follows specialized liabilities.
  • Review crime/employee-dishonesty coverage.
  • Confirm background-check procedures.
  • Review staff training.
  • Document playground inspections.
  • Review medication procedures.
  • Review food-allergy procedures.
  • Maintain emergency plans.
  • Review authorized-pickup procedures.
  • Document incidents.
  • Review field-trip procedures.
  • Verify compliance with state and local licensing rules.

Frequently Asked Questions

What insurance does a daycare center need?

Needs vary by location and operation, but commonly considered coverages include general liability, property, workers’ compensation, abuse and molestation liability, professional liability, commercial auto, cyber insurance, EPLI and umbrella/excess liability.

Does general liability cover child injuries?

It may cover qualifying bodily-injury claims, subject to policy terms. However, certain allegations or activities may be excluded or covered separately. Review the actual policy.

Does daycare insurance cover abuse allegations?

Specialized abuse and molestation coverage may be available, but it should never be assumed to be included automatically in general liability. Check the limits, exclusions and endorsements.

Are background checks required for daycare workers?

For licensed child care programs, federal requirements call for specified criminal background checks. Childcare.gov says checks generally must be requested before employment and at least every five years thereafter.

Does a daycare need commercial auto insurance?

If the business owns or operates vehicles to transport children or conduct business, commercial auto coverage should be evaluated. Hired and non-owned auto exposure may also exist when employees use personal or rented vehicles for business purposes.

Does a daycare need cyber insurance?

It’s worth evaluating when the center stores personal information or relies on digital systems. A breach or ransomware attack could create privacy, restoration and interruption expenses.

Is daycare insurance required by law?

Requirements vary by state, territory, facility type and licensing status. Child care centers are commonly subject to state or territory licensing and minimum health and safety standards, but specific insurance requirements must be checked locally.

Why is daycare liability insurance becoming an issue in 2026?

The NAIC has established a Child Care Insurance Working Group whose 2026 mandate includes examining cost drivers and limitations affecting the availability of liability insurance for child care and related social-service organizations.

Final Thoughts

Daycare insurance isn’t simply:

“general liability for a building where children happen to be present.”

The real risk picture is much broader:

Children

Employees

Supervision

Facilities

Transportation

Sensitive information

Professional responsibilities.

And in 2026, the availability and cost of child care liability coverage have attracted enough regulatory attention that the NAIC is actively examining the market.

For child care centers and social-service organizations, a stronger strategy is:

Insurance + licensing compliance + background checks + staff training + documented supervision + emergency planning + incident documentation.

Insurance helps finance certain covered losses.

Good risk management aims to prevent those losses from happening in the first place.