Health insurance can help protect you from high medical expenses, but understanding how costs are shared between you and your insurance company is essential. One of the most important concepts in any health insurance plan is the deductible.
What you’ll understand
- Health Plan Cost-Sharing Estimator
- What Is a Health Insurance Deductible?
- Why Health Insurance Deductibles Matter
Many people mistakenly believe that once they have health insurance, the insurer immediately pays all medical expenses. In reality, most plans require policyholders to pay certain healthcare costs before the insurance company begins sharing covered expenses. This amount is known as the health insurance deductible.
Understanding how deductibles work can help you compare health insurance plans, estimate potential healthcare costs, and make informed decisions when selecting coverage for yourself or your family.
This guide explains what health insurance deductibles are, how they work, how they interact with copayments and coinsurance, and what factors to consider when choosing a plan.
Health Plan Cost-Sharing Estimator
See how a deductible and coinsurance can interact in a simplified example.
Simplified educational estimate. Real health-plan costs can also depend on copays, network status, negotiated rates, exclusions, out-of-pocket maximums and plan-specific rules.
What Is a Health Insurance Deductible?
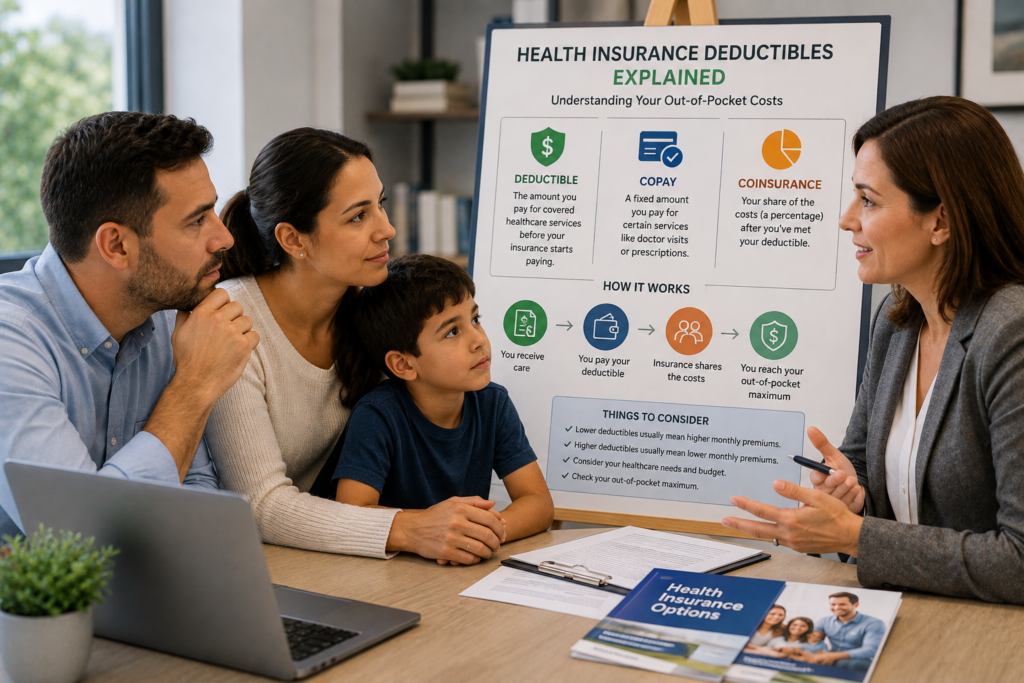
A health insurance deductible is the amount you generally pay out of pocket for covered healthcare services before your health insurance plan begins paying its share of eligible costs, subject to the policy’s terms, network requirements, and exclusions.
For example, if your annual deductible is $2,000, you typically pay eligible covered medical expenses until you reach that amount. After the deductible has been met, your insurer may begin sharing covered costs according to your plan’s coinsurance or copayment structure.
Not every healthcare service is necessarily subject to the deductible. Coverage varies by plan.
Why Health Insurance Deductibles Matter
Deductibles play an important role in how health insurance plans are priced and how medical costs are shared.
Understanding your deductible helps you:
- Estimate annual healthcare expenses.
- Compare health insurance plans.
- Prepare for unexpected medical costs.
- Choose a plan that fits your budget.
- Better understand when insurance begins sharing eligible costs.
How a Health Insurance Deductible Works
The process generally follows these steps:
Step 1: Enroll in a Health Insurance Plan
You choose a health insurance policy that includes:
- Annual deductible
- Monthly premium
- Copayments
- Coinsurance
- Out-of-pocket maximum
- Provider network
Step 2: Receive Covered Medical Care
When you receive eligible healthcare services, you may initially pay certain costs yourself until your deductible has been satisfied.
Depending on your plan, some preventive care services may be covered before you meet the deductible.
Step 3: Pay Toward Your Deductible
Each eligible medical expense you pay generally counts toward your annual deductible.
Examples may include:
- Doctor visits (depending on the plan)
- Laboratory services
- Diagnostic imaging
- Hospital services
- Prescription medications (if subject to the deductible)
Not every expense counts toward the deductible, so review your policy documents carefully.
Step 4: Reach Your Deductible
Once you’ve paid the required deductible amount for covered services, your insurance company generally begins paying its share of additional covered expenses according to your plan.
You may still be responsible for copayments, coinsurance, or non-covered services.
Step 5: Out-of-Pocket Maximum
Many health insurance plans include an annual out-of-pocket maximum.
Once you reach this limit through eligible out-of-pocket costs, the insurer generally pays 100% of covered healthcare expenses for the remainder of the plan year, subject to the policy’s terms.
Deductible vs. Copayment
Although both involve out-of-pocket costs, they are different.
| Deductible | Copayment |
|---|---|
| Amount paid before insurance begins sharing many covered costs | Fixed amount paid for certain covered services |
| Usually accumulated over the plan year | Paid at the time of service |
| Often higher | Usually a smaller fixed amount |
Some plans require copayments even after the deductible has been met.
Deductible vs. Coinsurance
Coinsurance is another important cost-sharing feature.
| Deductible | Coinsurance |
|---|---|
| Paid before many insurance benefits begin | Percentage of covered costs shared after the deductible is met |
| Fixed annual amount | Percentage of eligible medical expenses |
For example:
- Annual deductible: $1,500
- Coinsurance: 20%
After meeting the deductible, you may pay 20% of covered costs while the insurer pays the remaining eligible percentage until your out-of-pocket maximum is reached.
Individual vs. Family Deductibles
Health insurance plans may include:
Individual Deductible
Applies to one covered person.
Family Deductible
Applies to all covered family members combined.
Some family plans also include embedded individual deductibles that apply before the overall family deductible is reached.
High-Deductible Health Plans (HDHPs)
Some health insurance plans feature higher deductibles in exchange for lower monthly premiums.
These plans may appeal to individuals who:
- Are generally healthy.
- Rarely need medical care.
- Want lower monthly premium costs.
- Wish to pair eligible coverage with a Health Savings Account (HSA), where permitted.
Before selecting an HDHP, consider whether you could comfortably afford the deductible if unexpected medical expenses arise.
Low Deductible vs. High Deductible Plans
Choosing between a low deductible and a high deductible health insurance plan depends on your healthcare needs, financial situation, and risk tolerance.
| Low Deductible Plan | High Deductible Plan |
|---|---|
| Higher monthly premiums | Lower monthly premiums |
| Lower out-of-pocket costs before insurance begins sharing expenses | Higher out-of-pocket costs before insurance begins sharing expenses |
| May be suitable for individuals who expect regular medical care | May be suitable for individuals who rarely need healthcare services |
There is no one-size-fits-all solution. The best option depends on your expected healthcare usage and ability to pay unexpected medical expenses.
How to Choose the Right Deductible
When comparing health insurance plans, consider the following factors.
Your Expected Medical Needs
Think about how often you and your family typically use healthcare services.
Consider:
- Routine doctor visits
- Prescription medications
- Specialist appointments
- Planned surgeries
- Chronic medical conditions
- Ongoing treatments
Individuals with higher expected medical expenses may prefer plans with lower deductibles.
Your Monthly Budget
Lower deductibles usually come with higher monthly premiums.
Choose a balance between monthly affordability and potential out-of-pocket expenses.
Emergency Savings
A high deductible means you may need to pay more before insurance begins sharing eligible costs.
Make sure you have sufficient savings to cover unexpected healthcare expenses if you choose a higher deductible plan.
Total Annual Costs
Don’t focus only on the deductible.
Review the plan’s:
- Monthly premium
- Copayments
- Coinsurance
- Out-of-pocket maximum
- Provider network
- Prescription drug coverage
Looking at the total potential annual cost provides a more complete picture.
Common Mistakes to Avoid
Assuming Every Medical Expense Counts Toward the Deductible
Not all healthcare costs apply to the deductible. Coverage varies by plan and policy.
Choosing a Plan Based Only on the Lowest Premium
Lower premiums often come with higher deductibles. Consider your overall financial exposure before selecting a plan.
Ignoring the Out-of-Pocket Maximum
The deductible is only one part of your healthcare costs. Understanding the annual out-of-pocket maximum is equally important.
Not Reviewing Provider Networks
Receiving care from out-of-network providers may result in higher costs or reduced coverage, depending on your plan.
Forgetting Annual Plan Changes
Health insurance plans may change deductibles, premiums, provider networks, and covered benefits each year. Review your plan during each enrollment period.
Frequently Asked Questions
Do I have to meet my deductible every year?
In most cases, yes. Health insurance deductibles generally reset at the beginning of each new plan year unless otherwise specified in your policy.
Does preventive care count toward my deductible?
Many health insurance plans cover certain preventive care services before the deductible is met, but coverage varies by plan and applicable regulations.
Is a deductible the same as a copay?
No. A deductible is the amount you generally pay before your insurance begins sharing many covered costs, while a copayment is a fixed amount paid for certain healthcare services.
What happens after I meet my deductible?
After meeting your deductible, your insurance company generally begins paying its share of covered medical expenses according to your plan’s coinsurance or copayment rules until you reach your out-of-pocket maximum.
Is a higher deductible always better?
Not necessarily. A higher deductible usually reduces monthly premiums but increases your potential out-of-pocket expenses if you require medical care.
Final Thoughts
Understanding your health insurance deductible is one of the most important steps in managing healthcare costs and selecting the right insurance plan. While deductibles can seem confusing at first, they simply represent the amount you generally pay toward covered medical services before your insurance begins sharing eligible expenses.
Before choosing a plan, compare deductibles alongside premiums, copayments, coinsurance, provider networks, prescription drug coverage, and out-of-pocket maximums. Evaluating the complete cost structure rather than focusing on a single feature can help you select coverage that aligns with your healthcare needs and financial goals.
Key terms in this guide
Tap a term to review the plain-English meaning while you read.
Premium
The amount charged for insurance coverage, usually paid monthly, quarterly or annually.
Deductible
The amount you may need to pay toward a covered loss before the insurer pays under the policy, subject to the policy terms.
Exclusion
A policy provision that removes specified situations, causes, property, people or losses from coverage.
Coinsurance
A percentage of eligible healthcare costs a health-plan member may pay after applicable plan rules such as the deductible are met.
Copay
A fixed amount a health-plan member may pay for a covered healthcare service, subject to plan terms.
Network
The group of healthcare providers or facilities that contract with a health plan under specified payment arrangements.
Did the guide make sense?
Answer two quick questions. Your score stays in this browser.
Verify Current Rules
Insurance rules, benefits and product terms can change. These official resources are useful starting points for checking current requirements; they do not replace your policy documents or jurisdiction-specific advice.
Thanks — your response is saved in this browser.
Continue learning, not just scrolling
Follow a practical path from understanding the idea to comparing options and preparing for real-world decisions.
 StartCopays vs. Coinsurance Explained: What’s the Difference and Which Costs You More?Build the foundation →
 CompareInvisible and Autoimmune Disability Claims: Building Evidence Around FunctionCompare your options →
 PlanMedicare Advantage 2026: A Plan-Comparison Checklist for Networks, Drugs, and CostsUnderstand the numbers →
 ActFAIR Act and Disability Claims: How to Verify the Exact Law Before Changing a Claim StrategyBe ready for a claim →
Leave a Comment
Share a helpful question or experience. Your email address will not be published.