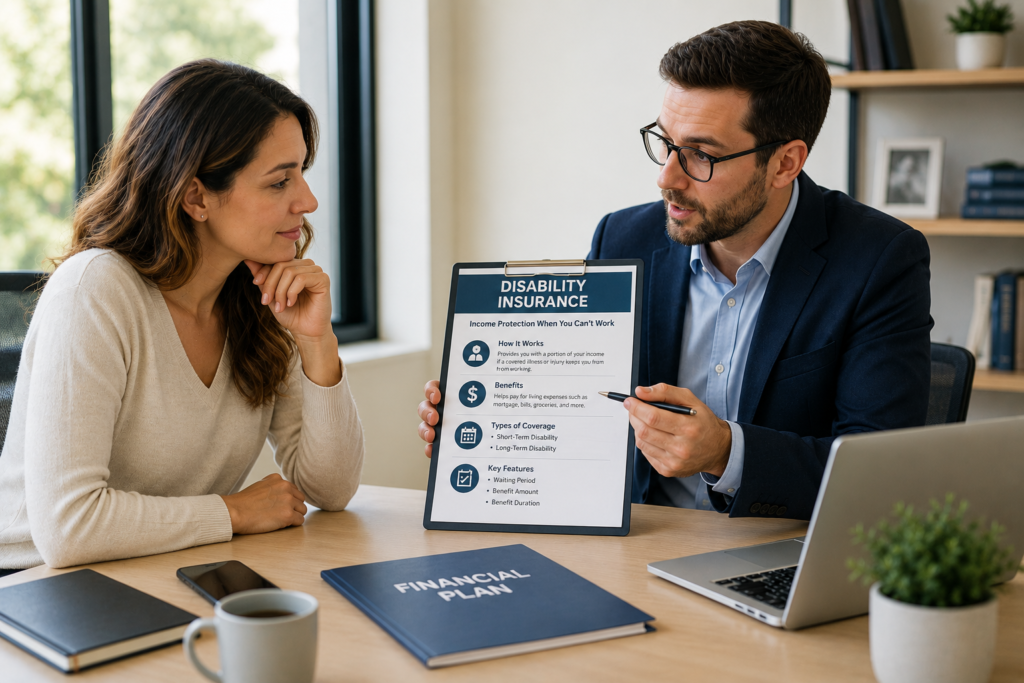
Most people insure valuable possessions such as their home, vehicle, and health, yet one of their greatest financial assets is often overlooked—the ability to earn an income. If an illness or injury prevents you from working, your regular paycheck may stop while your household expenses continue.
What you’ll understand
- What Is Disability Insurance?
- Disability Income Gap Calculator
- Why Disability Insurance Is Important
Disability insurance is designed to replace a portion of your income if a covered medical condition prevents you from performing your job. Unlike health insurance, which helps pay medical expenses, disability insurance focuses on helping you meet everyday financial obligations while you’re unable to work.
Whether you’re an employee, self-employed professional, freelancer, or business owner, understanding how disability insurance works can help you make informed decisions about protecting your financial future.
What Is Disability Insurance?
Disability insurance is a type of income protection insurance that provides periodic benefit payments if a covered illness or injury prevents you from working.
Disability Income Gap Calculator
Estimate the monthly gap between essential expenses and available disability income.
Planning illustration only. Benefit eligibility, taxation, offsets, waiting periods and policy definitions can materially change the result.
Benefits are intended to help with ongoing living expenses such as:
- Mortgage or rent
- Utility bills
- Groceries
- Car payments
- Insurance premiums
- Childcare expenses
- Loan repayments
- Other essential household costs
Coverage depends on the policy’s terms, conditions, exclusions, and benefit limits.
Why Disability Insurance Is Important
Many families depend on one or two primary incomes to cover monthly expenses. If that income suddenly stops because of a disability, financial pressure can build quickly.
Disability insurance may help:
- Replace part of your lost income.
- Reduce reliance on emergency savings.
- Help maintain your standard of living.
- Keep up with recurring bills.
- Support long-term financial goals during recovery.
- Provide financial stability while you focus on your health.
How Disability Insurance Works
Although policies vary, the general process is similar.
Step 1: Purchase a Policy
You select a disability insurance policy based on factors such as:
- Desired monthly benefit
- Waiting period
- Benefit duration
- Occupation
- Income
- Budget
Some employers also provide disability coverage as part of their employee benefits package.
Step 2: Pay Premiums
To keep the policy active, you pay premiums according to the policy schedule.
Premium amounts depend on factors such as:
- Age
- Occupation
- Income
- Health history
- Smoking status
- Benefit amount
- Waiting period
- Benefit period
Step 3: A Covered Disability Occurs
If a covered illness or injury prevents you from working, you may become eligible to file a claim.
Examples may include:
- Serious injuries
- Surgery recovery
- Cancer
- Stroke
- Back disorders
- Neurological conditions
- Pregnancy-related disabilities (where covered)
- Certain mental health conditions, depending on the policy
Eligibility depends on the policy definition of disability.
Step 4: File a Claim
You generally submit:
- Claim forms
- Medical records
- Physician statements
- Employment information
- Income verification
- Other documentation requested by the insurer
Providing complete information can help the claim move more efficiently.
Step 5: Waiting Period Begins
Most disability insurance policies include a waiting period (also called an elimination period).
This is the amount of time you must remain disabled before benefits begin.
Common waiting periods vary by policy. Choosing a longer waiting period may reduce premiums but means relying on your own savings for a longer time.
Step 6: Claim Review
The insurer reviews:
- Medical documentation
- Policy coverage
- Occupational duties
- Income information
- Eligibility requirements
Additional medical information may be requested before a decision is made.
Step 7: Benefits Begin
If the claim is approved and the waiting period has been satisfied, the insurer begins paying benefits according to the policy.
Benefits are typically paid on a regular schedule, such as monthly, while you remain eligible under the policy terms.
Types of Disability Insurance
Short-Term Disability Insurance
Short-term disability insurance provides income replacement for temporary disabilities.
It may help during recovery from:
- Surgery
- Broken bones
- Pregnancy and childbirth recovery
- Temporary illnesses
- Short-term injuries
Benefits generally last for weeks or several months, depending on the policy.
Long-Term Disability Insurance
Long-term disability insurance is designed for illnesses or injuries that prevent you from working for an extended period.
Depending on the policy, benefits may continue:
- For several years
- Until a specified age
- Until retirement age
- For another selected benefit period
This coverage is often intended to protect against long-lasting disabilities that significantly affect earning capacity.
Employer Disability Insurance vs. Individual Disability Insurance
| Feature | Employer Coverage | Individual Coverage |
|---|---|---|
| Offered through employer | ✔ | ✘ |
| Portable when changing jobs | Usually No | Often Yes |
| Coverage customization | Limited | Greater flexibility |
| Premium payer | Employer, employee, or both | Policyholder |
Many individuals choose to supplement employer coverage with an individual policy for additional protection.
What Is a Disability?
Every insurer defines disability differently.
Policies may evaluate:
- Your ability to perform your own occupation.
- Your ability to perform any occupation for which you are reasonably qualified.
- Medical evidence supporting the disability.
- Functional limitations caused by the illness or injury.
Understanding your policy’s definition of disability is one of the most important parts of choosing coverage.
How Much Income Does Disability Insurance Replace?
Disability insurance is designed to replace a portion of your income rather than your entire salary. The exact percentage depends on the policy, insurer, and other benefits you may receive.
The monthly benefit is typically based on factors such as:
- Your pre-disability income.
- The maximum benefit allowed under the policy.
- Any applicable offsets or coordination with other eligible benefits.
- Policy limits and terms.
Review your policy carefully to understand how benefits are calculated.
Benefit Periods
The benefit period is the length of time disability benefits may continue while you remain eligible.
Common benefit period options include:
- Several months
- Two years
- Five years
- Ten years
- To a specified retirement age
Longer benefit periods generally result in higher premiums but provide extended financial protection.
Common Policy Exclusions
Every disability insurance policy contains exclusions and limitations.
Examples may include:
- Intentionally self-inflicted injuries.
- Disabilities resulting from criminal activity.
- Conditions specifically excluded by the policy.
- Certain pre-existing conditions, subject to policy provisions.
- Disabilities occurring before the policy becomes effective.
Always read the policy wording to understand what is and is not covered.
Employer Disability Insurance vs. Individual Policies
Many employers offer disability insurance as part of an employee benefits package. While this can provide valuable protection, employer-sponsored coverage may not meet every family’s needs.
Employer-Sponsored Disability Insurance
Advantages:
- Often available at a lower cost.
- Convenient payroll deductions.
- Easy enrollment during benefits periods.
Potential limitations:
- Coverage may end if employment ends.
- Limited customization.
- Benefit amounts may not fully replace household income.
Individual Disability Insurance
Advantages:
- Coverage usually remains with you if you change jobs.
- Greater flexibility in choosing benefit amounts and policy features.
- Ability to tailor coverage to your financial goals.
Individual policies may be particularly valuable for self-employed professionals, business owners, or employees seeking additional protection.
How to Choose the Right Disability Insurance
When comparing policies, consider:
1. Monthly Income Needs
Estimate how much money your household would require each month if you could not work.
Include:
- Mortgage or rent
- Utility bills
- Food
- Transportation
- Childcare
- Insurance premiums
- Debt payments
2. Waiting Period
Choose a waiting period that aligns with your emergency savings.
A longer waiting period may reduce premiums, while a shorter waiting period can provide benefits sooner after a covered disability.
3. Benefit Duration
Consider how long your household could need income replacement if a disability lasts longer than expected.
4. Occupation
Some occupations have higher disability risks than others, which can affect both eligibility and premium costs.
5. Existing Employer Benefits
Review your workplace disability benefits before purchasing an individual policy to identify any gaps in coverage.
Common Mistakes to Avoid
Assuming Health Insurance Replaces Income
Health insurance helps pay for medical care, while disability insurance is designed to replace a portion of lost income.
Waiting Too Long to Purchase Coverage
Premiums generally increase with age, and certain medical conditions may affect eligibility or pricing.
Choosing the Lowest Premium Only
A less expensive policy may include longer waiting periods, shorter benefit durations, or lower monthly benefits.
Not Reviewing Coverage Regularly
Life events such as marriage, having children, buying a home, or changing careers may affect your disability insurance needs.
Ignoring Policy Definitions
Understanding how your policy defines “disability” is critical when evaluating coverage.
Frequently Asked Questions
Is disability insurance the same as health insurance?
No. Health insurance helps pay medical expenses, while disability insurance provides income replacement if a covered illness or injury prevents you from working.
Can self-employed individuals buy disability insurance?
Yes. Many insurers offer disability insurance policies designed specifically for self-employed professionals, freelancers, and business owners.
Does disability insurance cover every illness or injury?
No. Coverage depends on the policy’s terms, exclusions, waiting periods, and the insurer’s determination that the disability meets the policy definition.
Can I receive disability insurance benefits and still work?
Some policies include provisions for partial or residual disability benefits if you can work in a limited capacity. Eligibility varies by policy.
Is disability insurance worth it?
For individuals who depend on employment income, disability insurance can be an important part of a broader financial protection strategy by helping replace a portion of income during a covered disability.
Final Thoughts
Disability insurance helps protect one of your most valuable financial assets—your ability to earn an income. While no one expects to become unable to work because of illness or injury, having a well-chosen disability insurance policy can provide financial support when it’s needed most.
Before purchasing coverage, compare policy features, waiting periods, benefit durations, definitions of disability, and exclusions. Understanding how disability insurance works can help you select protection that supports your financial goals and provides greater peace of mind for you and your family.
Key terms in this guide
Tap a term to review the plain-English meaning while you read.
Premium
The amount charged for insurance coverage, usually paid monthly, quarterly or annually.
Policy Limit
The maximum amount an insurer may pay for a covered loss or category of loss under the policy.
Exclusion
A policy provision that removes specified situations, causes, property, people or losses from coverage.
Claim
A request for payment or benefits under an insurance policy after an event that may be covered.
Elimination Period
A waiting period in some disability or long-term-care policies before eligible benefits begin.
Waiting Period
A specified period that must pass before certain coverage or benefits become available.
Did the guide make sense?
Answer two quick questions. Your score stays in this browser.
Verify Current Rules
Insurance rules, benefits and product terms can change. These official resources are useful starting points for checking current requirements; they do not replace your policy documents or jurisdiction-specific advice.
Thanks — your response is saved in this browser.
Continue learning, not just scrolling
Follow a practical path from understanding the idea to comparing options and preparing for real-world decisions.
 StartWorkers’ Compensation Insurance Guide: Coverage, Benefits, Costs, and Employer ResponsibilitiesBuild the foundation →
 CompareOwn-Occupation vs. Any-Occupation Disability Insurance: How the Definitions Change a ClaimCompare your options →
 PlanMedicare Advantage 2026: A Plan-Comparison Checklist for Networks, Drugs, and CostsUnderstand the numbers →
 ActInvisible and Autoimmune Disability Claims: Building Evidence Around FunctionBe ready for a claim →
Leave a Comment
Share a helpful question or experience. Your email address will not be published.