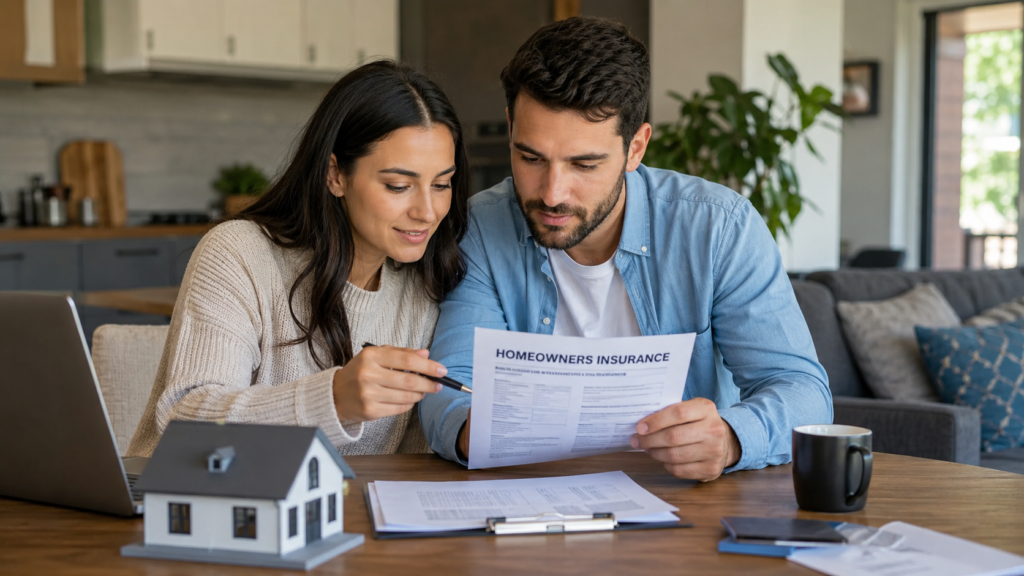
Buying your first home is a major milestone and one of the biggest financial investments you’ll ever make. Along with choosing the right property and arranging a mortgage, protecting your home with homeowners insurance is an important step.
What you’ll understand
- What Is Homeowners Insurance?
- Home Contents Quick Estimator
- Why Do First-Time Buyers Need Homeowners Insurance?
If you’re buying a home for the first time, insurance terms like deductibles, dwelling coverage, and liability protection can seem confusing. This guide explains the basics of homeowners insurance in simple language so you can understand how it works and choose coverage with confidence.
What Is Homeowners Insurance?
Homeowners insurance is a policy that helps protect your home and personal belongings against certain covered risks. It can also provide liability protection if someone is injured on your property or if you accidentally cause damage to someone else’s property.
Coverage varies by insurer and policy, so it’s important to review the details before purchasing insurance.
Home Contents Quick Estimator
Add your own rough estimates to see how quickly household contents can add up.
This is a rough inventory aid, not a valuation or coverage recommendation. High-value items can have separate limits and documentation requirements.
Why Do First-Time Buyers Need Homeowners Insurance?
Your home is likely one of your most valuable assets. Unexpected events such as fire, storms, theft, or vandalism can result in costly repairs or replacements.
Homeowners insurance may help:
- Protect your home’s structure
- Cover personal belongings
- Provide liability protection
- Help pay for temporary living expenses if your home becomes uninhabitable due to a covered event
- Offer financial peace of mind
Many mortgage lenders also require homeowners insurance before approving a home loan.
How Does Homeowners Insurance Work?
Understanding the process makes buying insurance much easier.
Choose a Policy
Compare different insurance companies and select a policy that fits your home’s value, location, and budget.
Pay Your Premium
You’ll pay a monthly or annual premium to keep your coverage active.
File a Claim
If a covered event damages your home or belongings, you can file a claim with your insurance company.
Claim Review
The insurance company reviews your claim and determines what is covered according to your policy.
Receive Payment
Once approved, the insurer helps pay covered repair or replacement costs, subject to deductibles and policy limits.
What Does Homeowners Insurance Typically Cover?
Most standard homeowners insurance policies include several types of protection.
Dwelling Coverage
Helps repair or rebuild your home’s structure after covered damage.
Other Structures Coverage
Protects detached garages, sheds, fences, and similar structures on your property.
Personal Property Coverage
Helps replace personal belongings such as furniture, electronics, clothing, and appliances if they’re damaged or stolen due to covered events.
Liability Coverage
Provides financial protection if you’re legally responsible for injuries or property damage involving another person.
Additional Living Expenses (ALE)
If a covered event makes your home temporarily uninhabitable, this coverage may help pay for hotel stays, meals, and other eligible temporary living expenses.
What Isn’t Usually Covered?
Most standard policies have exclusions.
Common exclusions may include:
- Flood damage
- Earthquake damage
- Normal wear and tear
- Pest damage
- Intentional damage
- Certain high-value collectibles unless additional coverage is purchased
Separate insurance may be available for some excluded risks.
Factors That Affect Insurance Costs
Insurance companies consider several factors when calculating premiums.
These may include:
- Home location
- Home age
- Construction materials
- Roof condition
- Replacement cost
- Claims history
- Deductible amount
- Coverage limits
- Security systems
Tips for First-Time Homebuyers
Before purchasing homeowners insurance:
- Compare quotes from multiple insurers.
- Understand what your policy covers.
- Choose a deductible you can comfortably afford.
- Create a home inventory with photos.
- Review coverage annually.
- Ask about available discounts.
Common Mistakes to Avoid
Many first-time buyers make avoidable mistakes.
Avoid:
- Buying coverage based only on price.
- Underinsuring your home.
- Ignoring policy exclusions.
- Forgetting to update coverage after renovations.
- Not keeping records of valuable belongings.
Conclusion
Homeowners insurance is an important part of protecting your investment and your financial future. Understanding how policies work, what they cover, and what they exclude can help first-time buyers make informed decisions.
Key terms in this guide
Tap a term to review the plain-English meaning while you read.
Premium
The amount charged for insurance coverage, usually paid monthly, quarterly or annually.
Deductible
The amount you may need to pay toward a covered loss before the insurer pays under the policy, subject to the policy terms.
Policy Limit
The maximum amount an insurer may pay for a covered loss or category of loss under the policy.
Exclusion
A policy provision that removes specified situations, causes, property, people or losses from coverage.
Claim
A request for payment or benefits under an insurance policy after an event that may be covered.
Liability
Legal responsibility for injury, damage or loss suffered by another person or organization.
Did the guide make sense?
Answer two quick questions. Your score stays in this browser.
Verify Current Rules
Insurance rules, benefits and product terms can change. These official resources are useful starting points for checking current requirements; they do not replace your policy documents or jurisdiction-specific advice.
Thanks — your response is saved in this browser.
Continue learning, not just scrolling
Follow a practical path from understanding the idea to comparing options and preparing for real-world decisions.
 StartWorkers’ Compensation Insurance Guide: Coverage, Benefits, Costs, and Employer ResponsibilitiesBuild the foundation →
 CompareBehavioral Health Riders in Disability Insurance: Limits, Definitions, and What to CompareCompare your options →
 PlanMedicare Advantage 2026: A Plan-Comparison Checklist for Networks, Drugs, and CostsUnderstand the numbers →
 ActInvisible and Autoimmune Disability Claims: Building Evidence Around FunctionBe ready for a claim →
Leave a Comment
Share a helpful question or experience. Your email address will not be published.